Yield curve strategies represent one of the most critical active frameworks for fixed-income portfolio managers seeking to generate alpha, optimize risk-adjusted returns, and manage balance sheet liabilities.
Executing effective yield curve strategies requires a granular understanding of benchmark yield movements, forward rate dynamics, structural duration positioning, and multi-currency yield differentials.
This comprehensive guide examines the core analytical drivers of fixed-income portfolio returns, portfolio positioning under market-consensus and divergent interest rate views, volatility management, key rate duration risk modeling, cross-currency strategies, and integrated return-risk evaluation frameworks.
Factors Affecting Fixed-Income Portfolio Returns Due to Changes in Benchmark Yields
To structure yield curve strategies effectively, fixed-income managers must break down total return into its fundamental drivers. Total return over a specified holding period is driven by yield income, price movement due to benchmark yield changes, spread dynamics, credit losses, and currency shifts.
Total Return Decomposition
The expected total return of a fixed-income portfolio over a given investment horizon can be expressed through five key components:
- Yield Income: The cash flow generated by coupon payments and reinvestment returns over the investment period.
- Rolldown Return: The capital appreciation realized as a bond approaches maturity along an upward-sloping yield curve, assuming the yield curve shape remains constant.
- Price Change from Benchmark Yield Changes: The valuation impact driven by movements in risk-free benchmark yields, modeled through duration and convexity.
- Price Change from Spread Changes: Value fluctuations caused by shifts in credit spreads, liquidity premiums, or sector-specific risk margins.
- Currency Gains or Losses: The impact of exchange rate movements on unhedged foreign currency bond holdings.
The benchmark price change component is estimated using the standard Taylor series approximation:
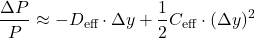

Where 


Decomposition of Benchmark Yield Movements
Benchmark yield changes rarely occur as clean, parallel shifts across all maturities. Empirical research demonstrates that yield curve movements are driven by three principal factors:
| Yield Curve Factor | Structural Movement | Portfolio Valuation Impact |
| Shift (Level) | Parallel move in yields across all maturities | Primary driver of portfolio return variance; managed via aggregate portfolio duration. |
| Twist (Slope) | Non-parallel shift changing the spread between short-term and long-term rates | Alters the steepness of the curve; managed via bullet versus barbell allocation. |
| Curvature (Shape) | Movement in intermediate rates relative to short and long maturities | Alters the degree of curve humpedness; managed through butterfly trade structures. |
Leading asset management firms such as BlackRock utilize factor models to decompose yield curve changes into level, slope, and curvature components, allowing portfolio managers to isolate specific market risks.
Portfolio Positioning Strategy Given Forward Rates and a Market-Coincident View
When a portfolio manager’s interest rate forecast aligns with the forward curve implied by current market prices, the market is priced efficiently according to the manager’s view. In this scenario, generating excess return requires capitalizing on structural yield curve features rather than taking directional duration bets.
Buy and Hold Strategy
Under a buy-and-hold approach, the manager purchases bonds with maturities extending beyond the investment horizon to lock in higher yield. If the yield curve is upward-sloping and rates evolve as implied by forward rates, holding longer-dated paper provides higher coupon income without active trading overheads.
Rolling Down the Yield Curve
When the yield curve is upward-sloping, a bond’s yield decreases and its price increases as it approaches maturity over time. This capital gain is known as the rolldown return.
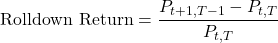

Where 


Institutional investors like PIMCO frequently position portfolios at segments of the yield curve where the slope is steepest to maximize total roll-down gain.
Repo Carry Trades
A carry trade involves borrowing funds in the short-term money market at lower repurchase agreement (repo) rates and investing the proceeds in higher-yielding, longer-term benchmark securities.
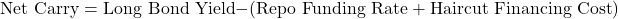

This strategy generates positive net interest margin provided the yield curve does not shift upward by more than the implied break-even rate.
Selling Volatility via Options and Swaptions
If interest rates move strictly in line with market expectations, realized rate volatility will be lower than option-implied volatility. Managers can harvest the volatility risk premium by selling call and put options, writing covered calls on benchmark holdings, or selling interest rate swaptions to earn option premium income.
Portfolio Positioning Strategy Given a Divergent Interest Rate View
When a portfolio manager’s interest rate expectations diverge from consensus forward rates, active strategies must be structured to exploit mispricings in rate level, curve slope, or curve shape.
Divergent View on Interest Rate Level
- Bullish View (Rates expected to fall faster than implied by forwards): Extend portfolio duration relative to the benchmark. Long-duration assets deliver superior price gains when yields drop.
- Bearish View (Rates expected to rise faster than implied by forwards): Shorten portfolio duration relative to the benchmark, or increase cash allocations and floaters to shield capital from price depreciation.
Divergent View on Yield Curve Slope
Yield curve slope positioning involves choosing between bullet, barbell, and ladder structures based on expected steepening or flattening:
| Market View | Yield Curve Shift | Optimal Portfolio Strategy | Execution Mechanics |
| Bullish Steepener | Short rates drop faster than long rates | Barbell / Long Short-End | Overweight short-duration bonds using leverage or receiver swaps on the short end. |
| Bearish Steepener | Long rates rise faster than short rates | Bullet / Underweight Long-End | Underweight long-maturity bonds; pay fixed on long-end interest rate swaps. |
| Bullish Flattener | Long rates drop faster than short rates | Long Long-End | Overweight long-duration bonds to capture capital appreciation as long-end yields decline. |
| Bearish Flattener | Short rates rise faster than long rates | Barbell / Short Short-End | Underweight short-to-intermediate maturities; receive fixed on long end while shortening front end. |
Investment banks such as Goldman Sachs execute these structural views using interest rate swaps, swaptions, and Treasury futures to tailor exposure without taking outright balance-sheet risk.
Divergent View on Yield Curve Curvature
Curvature trades target non-linear changes in the yield curve shape using three-part structures called butterflies. A butterfly consists of short-term bonds (wing 1), intermediate-term bonds (body), and long-term bonds (wing 2).
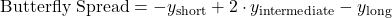

- Positive Butterfly (Expecting Curve to Become Less Humped / Flatten in Intermediate Rates):
- Positioning: Long Wings (short and long maturities) and Short Body (intermediate maturities).
- Outcome: Benefits when intermediate yields rise relative to short and long yields, causing the belly of the curve to perform poorly compared to the wings.
- Negative Butterfly (Expecting Curve to Become More Humped):
- Positioning: Short Wings (short and long maturities) and Long Body (intermediate maturities).
- Outcome: Benefits when intermediate yields decline relative to the wings, maximizing price appreciation in the intermediate section.
Portfolio Positioning Strategy Based on Expected Changes in Interest Rate Volatility
Interest rate volatility directly impacts the value of embedded options in fixed-income securities and dictates the performance of non-linear portfolio structures.
Expecting Higher Interest Rate Volatility
When market uncertainty is anticipated to drive interest rate volatility above currently priced levels, portfolio managers adopt strategies that benefit from sharp rate swings regardless of direction:
- Long Option Positions: Purchase interest rate caps, floors, swaptions, or options on Treasury futures. As realized volatility increases, the vega component of options yields positive capital returns.
- Maximizing Portfolio Convexity: Rebalance the portfolio into a wide barbell structure. Convexity measures the rate of change of duration. High-convexity portfolios capture greater price upside when yields drop than price downside when yields rise by an equivalent magnitude.
- Holding Callable Bond Protection: Avoid holding callable agency or corporate bonds, as higher rate volatility increases the probability of call execution, capping upside gains.
Expecting Lower Interest Rate Volatility
When economic conditions stabilize and interest rate volatility is expected to decline:
- Selling Option Premiums: Sell covered calls, write cash-secured puts, or sell interest rate swaptions to capture high implied volatility premiums before option prices decline.
- Minimizing Portfolio Convexity: Shift from barbell structures to concentrated bullet structures. Bullet portfolios sacrifice convexity in exchange for higher current yield.
- Overweighting Mortgage-Backed Securities (MBS): Institutional managers buy agency MBS issued by entities like Fannie Mae. These securities carry negative convexity due to homeowner prepayment options; when volatility declines, prepayment risk stabilizes, and investors capture attractive option-adjusted spreads (OAS).
Evaluating Portfolio Sensitivity Using Key Rate Durations
While effective duration measures portfolio value sensitivity to a uniform parallel shift in the yield curve, it fails to capture risks stemming from non-parallel movements, such as curve twisting or changing curvature. To overcome this limitation, fixed-income risk managers utilize Key Rate Duration (KRD).
Key Rate Duration Defined
Key Rate Duration measures the sensitivity of a portfolio’s total value to a change in the benchmark yield at a single specific maturity point (e.g., 2-year, 5-year, 10-year, 30-year), keeping all other key rates constant along the yield curve.
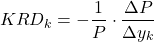

Where 


Portfolio vs. Benchmark Key Rate Duration Sensitivity Analysis
Consider a benchmark index with an effective duration of 6.0 years, compared against two active portfolios—Portfolio A (Bullet Strategy) and Portfolio B (Barbell Strategy)—each structured to match the benchmark’s total effective duration of 6.0 years:
| Key Rate Maturity | Benchmark KRD | Portfolio A (Bullet) KRD | Portfolio B (Barbell) KRD | Active Variance (Port B vs. Bmk) |
| 2-Year Key Rate | 0.80 | 0.10 | 2.50 | +1.70 |
| 5-Year Key Rate | 1.50 | 0.20 | 0.50 | -1.00 |
| 10-Year Key Rate | 2.20 | 5.40 | 0.50 | -1.70 |
| 30-Year Key Rate | 1.50 | 0.30 | 2.50 | +1.00 |
| Total Effective Duration | 6.00 | 6.00 | 6.00 | 0.00 |
Risk Evaluation Analysis
- Parallel Shift Sensitivity: If yields across all key rates rise uniformly by 100 basis points (+1.00%), all three portfolios experience a price decline of approximately 6.00%. Effective duration accurately predicts this result.
- Steepening Shift Sensitivity: If the 2-year key rate drops by 50 basis points (-0.50%) while the 30-year key rate rises by 50 basis points (+0.50%), aggregate effective duration indicates zero net impact. However, KRD reveals significant divergence:
- Portfolio A (Bullet): Suffers minimal impact because its exposure is concentrated in the 10-year segment.
- Portfolio B (Barbell): Gains on its heavy 2-year position (
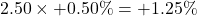
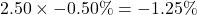


Quantitative risk managers at global investment banks like JPMorgan Chase & Co. mandate strict KRD bandwidths around benchmark indices to prevent unhedged curve twist exposures.
Yield Curve Strategies Across Currencies
Global bond managers routinely deploy yield curve strategies across foreign markets to capture yield differentials, exploit relative value mispricings, and manage currency-adjusted total returns.
Unhedged vs. Hedged Foreign Fixed-Income Investing
Investing in foreign government bonds exposes the portfolio to benchmark yield movements, local yield curve shape shifts, and foreign exchange fluctuations.
- Unhedged Strategy: The return is equal to the local bond return plus the spot exchange rate movement:
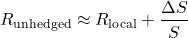
- Hedged Strategy: Foreign currency risk is hedged using forward FX contracts. According to Covered Interest Rate Parity (CIP), the hedged return approximates the domestic risk-free rate plus any credit, liquidity, or yield curve roll-down spreads:
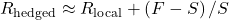


Cross-Currency Carry Trades
In a cross-currency carry trade, an investor borrows capital in a low-interest-rate currency (e.g., Japanese Yen or Swiss Franc) and invests in higher-yielding sovereign debt (e.g., US Treasuries or Australian Government Bonds).
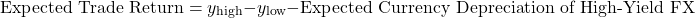

While this strategy offers attractive yield pickup, it is exposed to tail risk if market volatility spikes, causing low-yielding funding currencies to appreciate rapidly as investors unwind risk positions.
Cross-Currency Yield Curve Relative Value Trades
Global institutions like BNP Paribas construct relative value trades by identifying structural misalignments between sovereign yield curve steepness across markets:
- Cross-Border Curve Trade: Pay fixed on a 10-year Euro interest rate swap while receiving fixed on a 10-year US Dollar interest rate swap, currency-hedged back to the home currency.
- Driver: Exploits divergences in central bank monetary policy cycles, inflation trajectories, and sovereign debt issuance volumes.
Evaluating Expected Return and Risks of Yield Curve Strategies
To ensure robust risk-adjusted return generation, managers must systematically calculate expected total returns while measuring tail risks across market regimes.
Mathematical Formulation of Expected Strategy Return
The expected total return of an active yield curve strategy over horizon 

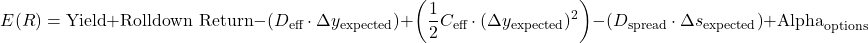

Where:
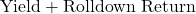


Core Risks Associated with Yield Curve Strategies
While active positioning can generate substantial excess returns, managers must continuously model four primary risk vectors:
+-----------------------------------------------------------------------------------+
|                        CORE FIXED-INCOME STRATEGY RISKS                           |
+--------------------------+--------------------------+-----------------------------+
|    Yield Curve Twist     |    Financing & Leverage  |     Liquidity Mismatch      |
|         Risk             |          Risk            |            Risk             |
+--------------------------+--------------------------+-----------------------------+
| Unexpected non-parallel  | Borrowing cost spikes on | Inability to unwind secondary|
| shifts (e.g., sharp      | repo facilities erode    | wings or derivatives during |
| curve flattening during  | carry trade margins      | market dislocation events   |
| barbell executions)      | during liquidity shocks  |                             |
+--------------------------+--------------------------+-----------------------------+
- Yield Curve Twist and Curvature Risk: Unanticipated shifts in yield curve shape can impair strategy returns even when rate level forecasts prove correct. For example, a barbell strategy designed for a parallel rate drop will suffer losses if intermediate rates fall while short and long rates spike.
- Financing and Leverage Risk: Strategies reliant on repo markets face rollover risk. If short-term borrowing rates rise sharply or haircuts increase during systemic stress, the cost of carry can quickly turn negative, forcing premature liquidation.
- Liquidity Risk: Complex butterfly wings or off-the-run Treasury issues may experience widening bid-ask spreads during market disruptions, eroding projected returns when positions are unwound.
- Model Risk and Breakdown of Correlations: Historical correlations between key interest rate points or global yield curves can break down during macroeconomic regime shifts or unprecedented central bank interventions.
Key Summary of Portfolio Positioning Across Market Regimes
To assist portfolio managers in aligning yield curve strategies with macro conditions, the table below summarizes the optimal implementations based on market views:
| Market Rate View | Expected Curve Shift | Optimal Portfolio Strategy | Primary Instrument Execution |
| Rates Falling Faster Than Forwards | Parallel Downshift | Extend Duration | Buy Long-Term Sovereign Bonds / Receive Fixed Swaps |
| Rates Rising Faster Than Forwards | Parallel Upshift | Shorten Duration | Increase Cash / Pay Fixed Swaps / Short Bond Futures |
| Yield Curve Steepening Expected | Spread Between Long/Short Widens | Barbell / Short Long-End | Long Short-End Debt + Underweight Long-End |
| Yield Curve Flattening Expected | Spread Between Long/Short Narrows | Bullet / Long Long-End | Overweight Long-End Debt + Underweight Short-End |
| Intermediate Yields Rising vs. Wings | Curvature Decreases | Positive Butterfly | Long Wings (2Y & 30Y) + Short Body (10Y) |
| Intermediate Yields Falling vs. Wings | Curvature Increases | Negative Butterfly | Short Wings (2Y & 30Y) + Long Body (10Y) |
| Interest Rate Volatility Rising | Increased Rate Dispersion | Increase Convexity | Buy Barbells / Buy Swaptions, Caps, & Floors |
| Interest Rate Volatility Declining | Stable Rate Environment | Sell Volatility / Capture Yield | Buy Bullets / Sell Options / Overweight MBS |
Conclusions
Yield curve strategies provide a structured framework for managing risk and driving excess performance in fixed-income portfolios. By decomposing benchmark yield movements into level, slope, and curvature factors, portfolio managers can construct positions targeted to specific market expectations.
When market views align with forward rates, strategies such as curve roll-down, repo carry trades, and option writing allow managers to extract structural return premiums without taking directional bets. Conversely, when views diverge from consensus forward rates, duration adjustments, steepener or flattener structures, and key rate duration management enable funds to capture alpha from non-parallel curve shifts.
Ultimately, successful execution requires integrating rigorous duration and convexity modeling, key rate sensitivity analysis, multi-currency relative value assessment, and strict liquidity stress testing. By balancing carry, rolldown, and active shape exposures against twist, leverage, and volatility risks, institutional investors can achieve consistent, superior risk-adjusted outcomes across changing economic cycles.

