Yield and yield spread measures for floating-rate instruments and money market instruments provide essential analytical frameworks for fixed-income investors, corporate treasurers, and portfolio managers navigating interest rate volatility.
Understanding how to calculate and interpret the quoted margin, discount margin, bank discount yield, and bond-equivalent yield allows market participants to accurately price, compare, and manage risk across diverse debt securities.
This article explores the core mechanics, mathematical formulations, and practical applications of these vital financial metrics, offering actionable insights for institutional and retail investors alike.
Understanding Floating-Rate Instruments and Their Yield Mechanics
Floating-rate instruments, commonly referred to as floating-rate notes or FRNs, represent debt securities whose coupon payments adjust periodically based on a reference benchmark interest rate. Unlike fixed-rate bonds, which expose investors to substantial market risk when interest rates rise, floating-rate instruments mitigate duration risk by resetting their coupons in alignment with prevailing market conditions.
Anatomy of a Floating-Rate Note
A standard floating-rate note consists of a reference rate—such as the Secured Overnight Financing Rate (SOFR) or the Euro Interbank Offered Rate (Euribor)—plus a fixed spread known as the quoted margin. The formula governing the periodic coupon payment of an FRN can be expressed as:
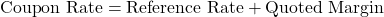
Because the reference rate fluctuates with macroeconomic cycles, the coupon rate changes at each reset date. However, the market price of the FRN may still deviate from its par value if credit spreads or liquidity conditions shift after issuance. When market required margins diverge from the quoted margin embedded in the note, the FRN will trade at a discount or a premium relative to its par value.
The Quoted Margin and Discount Margin
The quoted margin (QM) is the fixed spread over the reference rate that the issuer promises to pay the bondholder. Conversely, the discount margin (DM) is the yield spread over the reference rate that the market requires, given the current price of the floating-rate note and its credit risk profile.
When evaluating an FRN, financial analysts compare the quoted margin to the discount margin:
- If the quoted margin equals the discount margin, the FRN trades exactly at par value (USD100 per USD100 of face value).
- If the quoted margin is less than the discount margin, the FRN offers lower compensation than what the market currently demands, causing it to trade at a discount to par.
- If the quoted margin exceeds the discount margin, the FRN provides superior returns relative to market requirements, resulting in a premium price.
Calculating and Interpreting Yield Spread Measures for Floating-Rate Instruments
Calculating the discount margin requires solving for the spread over the reference rate that equates the present value of all future cash flows (coupon payments and the final principal repayment) to the current market price of the floating-rate note. Because future reference rates are unknown, analysts typically project future benchmark rates using current forward rates derived from the yield curve.
The Quoted Margin vs. Required Margin
To illustrate the valuation dynamics of floating-rate instruments, consider a corporate bond issued by a multinational institution such as JPMorgan Chase. Suppose an FRN has a par value of USD1,000, pays interest quarterly, and has a remaining maturity of two years (eight payment periods). The reference rate is currently 4.00% per annum (or 1.00% per quarter), and the quoted margin is 125 basis points (1.25% per annum, or 0.3125% per quarter).
If the market requires a total margin of 150 basis points over the reference rate for this level of credit risk, the quarterly discount margin rate applied to future cash flows will exceed the quoted coupon rate. Consequently, investors will purchase the instrument at a discount below USD1,000.
Real-World Example of Floating-Rate Valuation
Global financial institutions manage extensive portfolios of floating-rate assets and liabilities to insulate net interest margins from monetary policy shifts. Corporations such as HSBC routinely issue and invest in floating-rate notes linked to interbank lending rates across multiple currencies.
| Metric | Scenario A (At Par) | Scenario B (At Discount) | Scenario C (At Premium) |
| Par Value | USD1,000 | USD1,000 | USD1,000 |
| Current Market Price | USD1,000 | USD985 | USD1,012 |
| Quoted Margin | 100 bps | 100 bps | 150 bps |
| Required Discount Margin | 100 bps | 135 bps | 120 bps |
| Valuation Status | Par | Discount | Premium |
In Scenario B, because the required discount margin (135 basis points) exceeds the quoted margin (100 basis points), the security trades below par at USD985. Portfolio managers interpret this discount as an opportunity to capture capital appreciation as the bond approaches maturity, alongside regular quarterly coupon resets.
Yield Measures for Money Market Instruments
Money market instruments are short-term debt securities with maturities of one year or less. Examples include Treasury bills, commercial paper, certificates of deposit, and banker’s acceptances. Because these instruments typically do not pay periodic coupons and are issued at a discount to par, special yield conventions are required to calculate and interpret their returns accurately.
Discount-Basis Yield vs. Add-On Yield
The Bank Discount Yield (BDY) measures the annualized percentage discount from the face value of a money market instrument based on a 360-day year. The formula is:
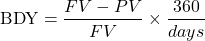
Where  represents the face value,
 represents the purchase price, and
 is the number of days remaining until maturity. While widely used in institutional quoting conventions, the bank discount yield underestimates the true investor return because it divides the discount by the face value rather than the actual purchase price, and it assumes a 360-day year instead of a 365-day calendar year.
To correct these distortions, financial analysts rely on the Add-On Yield and the Money Market Yield. The add-on yield for a 360-day year is calculated as:
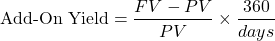
Money Market Yield and Bond-Equivalent Yield
The Money Market Yield (MMY), also known as the coupon-equivalent yield, converts a discount-basis security’s return into an annualized yield that can be directly compared with interest-bearing instruments calculated on a 360-day basis. The formula is:
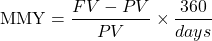
When comparing money market instruments directly to bonds that pay semi-annual coupons, the Bond-Equivalent Yield (BEY) is utilized. BEY adjusts the return to a 365-day year basis using the following conversion:
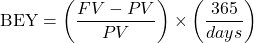
For corporate treasuries managing short-term cash reserves, accurately calculating BEY ensures that returns on commercial paper issued by corporations like Microsoft can be rigorously benchmarked against yields on US Treasury bills or bank deposits.
Practical Applications in Corporate Finance and Banking
Mastery of yield and yield spread measures is indispensable for treasury operations, asset-liability management, and investment analysis. Financial professionals must navigate different compounding conventions and spread metrics to optimize liquidity portfolios.
Managing Interest Rate Risk at Major Financial Institutions
Commercial banks and investment firms utilize floating-rate instruments to match floating-rate liabilities (such as customer deposits) with floating-rate assets (such as corporate loans). By monitoring the discount margin across floating-rate portfolios, risk managers can identify mispriced assets, assess credit migration risks, and adjust portfolio duration accordingly.
Corporate Liquidity Management
Multinational corporations maintain substantial short-term investment portfolios to fund ongoing operational expenses. Corporate treasurers evaluate money market instruments using bond-equivalent yields to ensure maximum risk-adjusted return on idle cash balances. Understanding the mathematical differences between bank discount yields and money market yields prevents misinterpretation of short-term returns and supports optimal capital allocation strategies.
Conclusions
Evaluating yield and yield spread measures for floating-rate and money market instruments requires precision, mathematical rigor, and an understanding of institutional conventions. Floating-rate notes protect investors against rising interest rate environments through periodic coupon resets, while discount margins reveal whether an instrument trades at par, discount, or premium relative to market requirements. Similarly, money market instruments demand careful conversion between bank discount yields, money market yields, and bond-equivalent yields to enable valid cross-instrument comparisons. By applying these quantitative frameworks, financial professionals can effectively manage liquidity, optimize portfolio performance, and navigate complex debt markets.
