Mastering Yield and Yield Spread Measures for Fixed-Rate Bonds is essential for institutional investors, portfolio managers, corporate treasurers, and financial analysts navigating the global fixed-income markets.
This comprehensive guide explores how to calculate annual yields across varying compounding frequencies, evaluate core yield metrics, and interpret critical yield spreads—such as G-spreads, I-spreads, and Z-spreads—using real-world examples from global corporate giants like Apple, Microsoft Corporation, and Toyota Motor Corporation.
The Fundamentals of Fixed-Rate Bond Yields
Fixed-rate bonds represent debt obligations where the issuer promises to pay a fixed coupon payment at regular intervals throughout the life of the instrument, returning the principal amount at maturity. Understanding the yield on these instruments requires moving beyond the nominal coupon rate to evaluate how cash flows, market prices, and time horizons interact.
Coupon Rate versus Current Yield and Yield to Maturity
The nominal coupon rate of a bond dictates the annual cash interest paid relative to its par value. However, because bonds trade at premiums or discounts relative to their par value in secondary markets, the actual return realized by an investor varies significantly.
Current yield measures a bond’s annual coupon payment relative to its current market price rather than its par value. While useful for income-focused investors, current yield fails to account for the capital gain or loss realized when the bond reaches maturity at par. Yield to Maturity (YTM) resolves this limitation by treating the bond’s price as the present value of all future cash flows—both coupon payments and the final principal repayment—discounted at a single internal rate of return.
The Time Value of Money in Bond Pricing
At the core of fixed-income valuation lies the time value of money. The price of a fixed-rate bond is the sum of the present values of all future cash flows. When market interest rates rise, the present value of future cash flows decreases, causing existing bond prices to fall. Conversely, falling market rates increase bond prices. Calculating the precise annualized yield requires accounting for the exact timing and frequency of these cash flows, which brings compounding periods into sharp focus.
Calculating Annual Yield Across Varying Compounding Periods
Fixed-income instruments often quote rates based on different compounding frequencies, such as annual, semi-annual, quarterly, or monthly payments. Comparing bonds directly requires standardizing these rates into comparable annualized metrics, such as the Effective Annual Yield (EAY) or Bond Equivalent Yield (BEY).
Understanding Periodic Rates and Compounding Frequency
When a bond pays interest  times per year, the periodic rate is calculated by dividing the stated annual rate by the number of compounding periods per year (). For instance, a bond with a stated annual rate of
 paid semi-annually has a periodic rate of
 per half-year (
 ).
To convert a periodic rate into an annual effective yield, compound the periodic rate over the number of periods in a year:
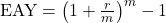
Where  is the stated annual interest rate and is the number of compounding periods per year. For a semi-annual bond, the Effective Annual Yield is:
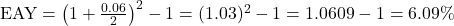
Converting Between Stated Rates and Effective Annual Rates
Institutional markets frequently compare instruments with differing payment frequencies. For example, US corporate bonds typically pay coupons semi-annually, whereas many money market instruments or floating-rate notes utilize quarterly or monthly compounding.
To convert an Effective Annual Yield back into a nominal rate with a different compounding frequency  , use the following relationship:
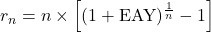
This conversion ensures that financial analysts at institutions like Apple or Microsoft Corporation can accurately evaluate debt financing costs across different international currency zones and debt markets.
Practical Calculation Examples Using Corporate Issuers
Consider a hypothetical corporate bond issued by Toyota Motor Corporation with a par value of USD1,000, paying a coupon of  annually, but compounded quarterly. The quarterly periodic rate is
 (
 ).
To find the Effective Annual Yield for this quarterly compounding structure:
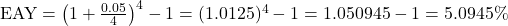
If another bond issued by Microsoft Corporation offers a semi-annual coupon of  , its EAY is:
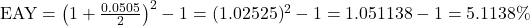
Comparing the EAY values ( versus
 ) reveals that the Microsoft Corporation bond provides a slightly higher true annual return despite the differing coupon structures and compounding frequencies.
Comparative Analysis of Yield Spread Measures
While Yield to Maturity provides an absolute measure of return, fixed-income investors rely heavily on yield spreads to assess relative value, credit risk, and market compensation over a risk-free benchmark. A yield spread is the difference between the yield of a specific bond and the yield of a benchmark reference rate, typically government securities or interest rate swaps.
Defining Yield Spreads and Benchmarks
Benchmarks serve as the foundation for pricing risk. In the United States, US Treasury securities serve as the benchmark risk-free rate across various maturities. In international markets, sovereign debt or benchmark swap rates fulfill this role.
Yield spreads are typically expressed in basis points (bps), where one basis point equals one-hundredth of a percentage point ( or
 ). Evaluating Yield and Yield Spread Measures for Fixed-Rate Bonds allows portfolio managers to isolate credit risk, liquidity risk, and structural optionality from general interest rate movements.
Nominal Spread and Zero-Volatility Spread (Z-Spread)
The nominal spread is the simplest spread measure. It is calculated as the difference between the yield to maturity of a corporate bond and the yield to maturity of a benchmark government bond with a similar maturity.
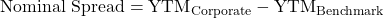
While straightforward, the nominal spread has a major limitation: it assumes a flat yield curve and discounts all cash flows at a single discount rate, ignoring the term structure of interest rates.
To overcome this, analysts utilize the Zero-Volatility Spread (Z-spread). The Z-spread is the constant spread that must be added to each spot rate on the benchmark zero-coupon yield curve so that the present value of the bond’s cash flows equals its current market price. Mathematically, it discounts each individual cash flow  at the spot rate
 plus the Z-spread (
 ):
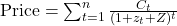
Interpreting Interpolated Spread (I-Spread) and Government Spread (G-spread)
Two other widely utilized spread measures in institutional trading desks are the G-spread and the I-spread:
- G-Spread (Government Spread): Measures the yield spread over the actual interpolated government benchmark yield matching the bond’s maturity. It assumes the benchmark yield curve is linear between adjacent Treasury maturities.
- I-Spread (Interpolated Spread): Measures the spread over the swap rate curve (such as SOFR swap rates) rather than government bonds. Because swap curves reflect interbank lending and credit conditions, I-spreads are heavily favored in corporate and financial institution bond trading.
Real-World Application and Corporate Issuer Case Studies
To understand how these metrics operate in professional settings, examine how multinational corporations issue debt and how markets price their credit risk.
Evaluating Microsoft Corporation Debt Issuances
Microsoft Corporation maintains a pristine credit rating, frequently issuing multi-tranche senior unsecured notes in global capital markets. Because of its exceptional financial strength and robust balance sheet, its bonds trade at very tight spreads relative to US Treasuries.
When an analyst evaluates a 10-year senior note issued by Microsoft Corporation yielding  when the 10-year US Treasury yields
 , the nominal spread is calculated as:
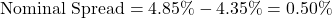 or
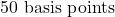
If the spot-rate adjusted Z-spread for the same bond is calculated at 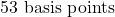 , the slight divergence reflects the upward-sloping nature of the spot rate curve over the 10-year horizon, providing a more rigorous measure of compensation for credit and liquidity risk.
Analyzing Toyota Motor Corporation Fixed-Rate Instruments
Toyota Motor Corporation operates extensive financing arms globally, issuing significant volumes of fixed-rate corporate bonds across multiple currencies. When evaluating international issuances, treasury analysts must reconcile different compounding conventions and benchmark curves.
For instance, a USD-denominated 5-year bond issued by Toyota Motor Corporation might be benchmarked against both the 5-year US Treasury yield (for G-spread analysis) and the 5-year USD swap rate (for I-spread analysis). Because swap rates typically trade higher than government bond yields due to banking sector credit risk, the I-spread for a corporate bond is generally lower than its G-spread.
Tables and Comparative Metrics of Fixed-Rate Yield Measures
To synthesize the various yield and spread measures discussed, the following table outlines their core definitions, benchmark references, and primary analytical use cases.
| Yield or Spread Measure | Benchmark Reference | Compounding Treatment | Primary Analytical Application |
| Effective Annual Yield (EAY) | None (Absolute Return) | Annualized compounding based on payment frequency () | Comparing annual returns of bonds with differing coupon frequencies |
| Nominal Spread | On-the-run government bond of similar maturity | Simple difference between YTM figures | Quick relative value screening for retail and institutional investors |
| Government Spread (G-Spread) | Interpolated government yield curve | Matches bond cash flow timing to interpolated benchmark | Standardized evaluation of credit risk against sovereign debt |
| Interpolated Spread (I-Spread) | Swap rate curve (e.g., SOFR swaps) | Interpolated swap rates matching maturity | Institutional trading and relative value pricing in corporate bond markets |
| Zero-Volatility Spread (Z-Spread) | Entire zero-coupon benchmark spot curve | Applied across all individual spot rates along the term structure | Pricing bonds with embedded options or non-flat yield curves |
Conclusion
Analyzing Yield and Yield Spread Measures for Fixed-Rate Bonds is fundamental to navigating the complexities of modern fixed-income markets.
By mastering the calculation of annual yields across varying compounding frequencies, financial professionals can accurately compare instruments regardless of their payment structures.
Furthermore, utilizing advanced spread measures such as G-spreads, I-spreads, and Z-spreads enables investors to precisely quantify credit risk, benchmark performance, and relative value across corporate issuers such as Apple, Microsoft Corporation, and Toyota Motor Corporation.
