Fixed-income instruments frequently feature embedded structural options that alter their cash flows based on prevailing market interest rates or equity performance.
Evaluating these hybrid securities requires advanced quantitative frameworks—such as backward induction on interest rate trees, arbitrage-free valuation models, and option-adjusted measures—to disaggregate the embedded derivative components from the host bond.
Fixed-Income Securities with Embedded Options
An embedded option is a structural provision written into a bond’s indenture that grants either the issuer or the bondholder the right to take specific actions affecting the instrument’s cash flows, maturity, or underlying asset structure. Unlike stand-alone financial derivatives, embedded options trade as an inseparable package with the underlying bond and cannot be severed or traded independently.
Fixed-income instruments with embedded options are broadly categorized by the holder of the option and the nature of the underlying trigger event:
- Callable Bonds: Grant the issuer the right—but not the obligation—to redeem (call back) the bond prior to its scheduled maturity date at a predetermined price (the call price), usually set at par or a slight premium to par. Issuers exercise this option when interest rates decline, allowing them to refinance existing higher-coupon debt at lower market yields. Callable bonds frequently include a call protection period (a lock-out period during which the bond cannot be called) and may feature deferred, discrete (European or Bermudan style), or continuous call schedules.
- Putable Bonds: Grant the bondholder the right to sell the security back to the issuer at a designated exercise price (the put price) on specified dates before maturity. Bondholders exercise this right when interest rates rise, enabling them to reinvest the returned principal into higher-yielding debt, or when the issuer’s credit quality degrades substantially.
- Estate Options (Survivor’s Options): Grant the estate of a deceased bondholder the right to put the bond back to the issuer at par value, providing liquidity to satisfy tax or estate obligations.
- Sinking Fund Provisions: Require the issuer to retire a specified portion of the outstanding bond issue periodically prior to maturity. If structured with an option to purchase bonds in the open market or call them at par, it represents an embedded option benefiting the issuer.
- Capped and Floored Floating-Rate Notes: Floating-rate notes (FRNs) where the coupon rate is subject to an upper bound (cap) or a lower bound (floor). A capped FRN contains an embedded option where the investor has sold a series of interest rate options (caplets) to the issuer, limiting the coupon ceiling. A floored FRN contains an embedded option purchased by the investor (floorlets) ensuring a minimum interest payout even if market reference rates collapse.
- Convertible Bonds: Grant the bondholder the right to exchange the bond for a specified number of shares of the issuer’s common stock at a predetermined conversion ratio. This structure grants equity upside potential while retaining fixed-income downside protection.
Price Relationships of Option-Embedded Bonds
The theoretical price of a bond containing an embedded option can be decomposed into two distinct components: the value of an underlying option-free (straight) bond with identical coupon, payment frequency, and maturity structure, and the economic value of the embedded derivative option.
Because the rights under these options belong to different parties in the contract, their values enter the balance equation with opposing algebraic signs.
Callable Bonds
In a callable bond structure, the investor buys the underlying straight bond and simultaneously sells (writes) a call option to the issuer. The issuer holds the right to call the bond, meaning the value of the option reduces the price the investor is willing to pay for the security.
The pricing relationship for a callable bond is expressed as:
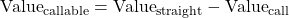

Where:


Isolating the value of the call option yields:
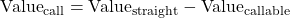

Because option values are non-negative (

Putable Bonds
In a putable bond structure, the investor buys the underlying straight bond and simultaneously purchases a put option from the issuer. Because the right to put the bond belongs to the investor, the embedded derivative increases the economic value of the security above that of a straight bond.
The pricing relationship for a putable bond is expressed as:
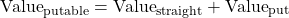
Where:


Isolating the value of the put option yields:
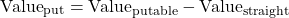
Because the put option protects the holder against price depreciation caused by rising interest rates, 
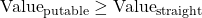


The table below summarizes these foundational relationships across varying market interest rate environments:
| Security Type | Structural Formula | Behavior in Low Interest Rate Environment | Behavior in High Interest Rate Environment |
| Callable Bond | 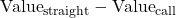 | Capped near Call Price ( | Behaves like Straight Bond (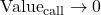 |
| Putable Bond | 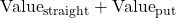 | Behaves like Straight Bond (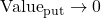 | Floored near Put Price ( |


Arbitrage-Free Framework for Bond Valuation
Standard discounted cash flow techniques relying on a single yield-to-maturity (YTM) are mathematically invalid for valuing bonds with embedded options. Yield-to-maturity assumes that future cash flows are fixed and independent of the path of interest rates. However, for option-embedded debt, future cash flows depend explicitly on whether the embedded option is exercised, which in turn depends on the short-term interest rate prevailing at each node in time.
To address path-dependent cash flows and prevent pricing arbitrage, practitioners use arbitrage-free binomial interest rate trees. An arbitrage-free framework models short-term interest rate volatility such that the model correctly reproduces the benchmark yield curve (zero-coupon spot rate curve) observed in the market.
Principles of the Binomial Interest Rate Tree
- Nodal Structure: Time is discretized into equal periods (
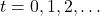


- Lattice Calibration: The rate tree is calibrated such that discounting the par values and coupon payments of benchmark risk-free instruments along every path generates theoretical values that match their current market prices.
- Lognormal Distribution & Volatility: Short rates are assumed to follow a lognormal distribution, preventing negative interest rates and modeling volatility as a constant percentage of rates. The relationship between upper and lower nodes at time


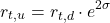

- Backward Induction: Valuations begin at maturity (


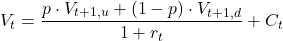

Where 


Incorporating Embedded Options in the Tree
To value bonds with embedded options, the standard backward induction algorithm is modified at each node by applying the decision rule corresponding to the structural option:
- Callable Bond Rule: At any node


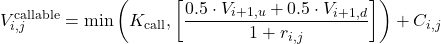

- Putable Bond Rule: At any node


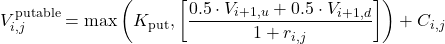

Impact of Interest Rate Volatility
The value of an embedded option—like any derivative option—is a positive function of the volatility of the underlying state variable (interest rates). Higher assumed interest rate volatility increases the probability that future interest rates will reach extreme high or low levels, expanding the expected payoff of the option.
                     ┌─────────────────────────────────────────┐
                      │   Interest Rate Volatility Increases    │
                      └────────────────────┬────────────────────┘
                                           │
                   ┌───────────────────────┴───────────────────────┐
                   ▼                                               ▼
     ┌───────────────────────────┐                 ┌───────────────────────────┐
     │  Issuer Call Option Value │                 │ Investor Put Option Value │
     │         Increases         │                 │         Increases         │
     └─────────────┬─────────────┘                 └─────────────┬─────────────┘
                   │                                               │
                   ▼                                               ▼
     ┌───────────────────────────┐                 ┌───────────────────────────┐
     │   Callable Bond Value     │                 │    Putable Bond Value     │
     │         DECREASES         │                 │         INCREASES         │
     └───────────────────────────┘                 └───────────────────────────┘
Callable Bonds and Volatility
Because a call option is held by the issuer, an increase in option value acts as a value transfer from the investor to the issuer.
- As interest rate volatility (
- Since
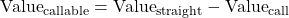
- Conversely, if interest rate volatility approaches zero, the call option value drops toward zero, and the callable bond value approaches the value of an equivalent straight bond.
Putable Bonds and Volatility
Because a put option is held by the bondholder, an increase in option value represents direct economic gain to the investor.
- As interest rate volatility (
- Since
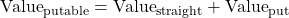
Impact of Yield Curve Level and Shape
Changes in the yield curve’s position (level) and slope (shape) significantly alter the intrinsic value of embedded options by shifting the probability distribution of early exercise.
Level Shifts in the Yield Curve
- Declining Interest Rates:
- Callable Bonds: As the yield curve shifts downward, straight bond prices rise. However, the probability of the issuer calling the bond increases dramatically, driving
- Putable Bonds: A declining yield curve depresses the probability that the investor will exercise the put option (
- Callable Bonds: As the yield curve shifts downward, straight bond prices rise. However, the probability of the issuer calling the bond increases dramatically, driving
- Rising Interest Rates:
- Callable Bonds: As the yield curve shifts upward, the probability of the bond being called falls to near zero (
- Putable Bonds: Rising interest rates depress straight bond prices, but cause the embedded put option to go deep into the money (
- Callable Bonds: As the yield curve shifts upward, the probability of the bond being called falls to near zero (
Yield Curve Flattening and Steepening
- Yield Curve Steepening: An upward-sloping or steepening yield curve implies higher forward interest rates in the future. Higher forward rates reduce the probability that future spot rates will fall below call prices, reducing the value of call options. Conversely, higher forward rates increase the likelihood that future spot rates will breach put strike levels, increasing the value of put options.
- Yield Curve Flattening/Inversion: A flattening or inverted yield curve implies lower future forward rates. This elevates the intrinsic value of call options (benefiting callable bond issuers) while suppressing the intrinsic value of put options.
Valuing an Option-Embedded Bond via an Interest Rate Tree
To illustrate the quantitative process, consider a 2-year, 5.00% annual coupon bond with a par value of 

Assume the calibrated 1-period short-rate tree (under an assumed volatility 

- Year 0 (


- Year 1 (

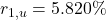
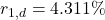


                       [Year 1]
                      / r_1,u = 5.820%
       [Year 0]      /
       r_0 = 4.000%
                     \
                      \ r_1,d = 4.311%
Step 1: Valuation of a Straight 5.00% Bond
We first compute the value of the option-free straight bond using backward induction from Year 2 maturity cash flows (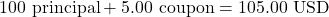

At Year 1 (
- Upper Node (


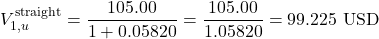

- Lower Node (

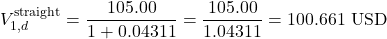

At Year 0 (
Add the Year 1 coupon (


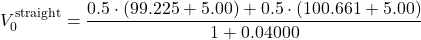

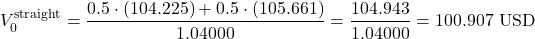

Step 2: Valuation of the Callable 5.00% Bond (Call Price = 100.00 USD)
We repeat backward induction, applying the issuer exercise decision rule 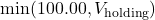

At Year 1 (
- Upper Node (

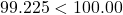
- Lower Node (

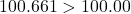


At Year 0 (
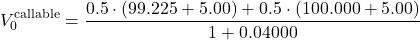

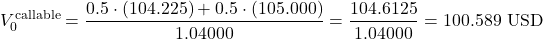

Step 3: Deriving Embedded Call Option Value
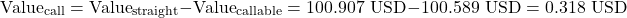

Option-Adjusted Spread (OAS)
When credit risk, liquidity risk, or structural options exist, a bond’s theoretical value derived purely from benchmark spot rates will differ from its observed market price.
The Option-Adjusted Spread (OAS) is the constant basis point spread added to every short-term rate in an interest rate tree such that the model’s theoretical value for the bond equals its observed market price.
   Benchmark Spot Rate Tree
              +
   Option-Adjusted Spread (OAS)
              │
              ▼
   Calibrated Interest Rate Tree  ──► Apply Option Exercise Rules  ──► Model Price = Market Price
Calculation of OAS
The OAS is solved iteratively using backward induction:
- Construct an arbitrage-free interest rate tree matching the benchmark yield curve.
- Add an initial constant spread estimate (


- Value the option-embedded bond via backward induction incorporating option decision rules.
- Compare the calculated model value to the actual market price.
- Adjust


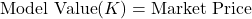

The final value of
Interpreting Spreads: Nominal Spread, Zero-Volatility Spread, and OAS
To isolate option risk from credit and liquidity risk, analysts evaluate three distinct spread metrics:
- Nominal Spread: The simple difference between the bond’s Yield to Maturity (YTM) and the YTM of an equivalent-maturity benchmark Treasury. It ignores yield curve shape and option risk.
- Zero-Volatility Spread (Z-Spread): The equal basis point spread added to each benchmark spot rate along a static spot yield curve to match the bond’s market price, assuming zero interest rate volatility. The Z-spread captures total compensation for credit risk, liquidity risk, and option risk.
- Option-Adjusted Spread (OAS): The spread component remaining after removing the financial value of the embedded option. OAS measures purely the compensation for credit risk and liquidity risk.
The operational mathematical relationship between these measures is:
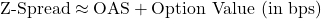

- For Callable Bonds: Since the option favors the issuer, the option value in basis points is positive. Thus:
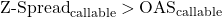

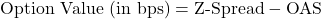
- For Putable Bonds: Since the option favors the investor, the option value in basis points is negative relative to required yield. Thus:
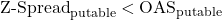

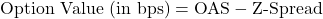

Interest Rate Volatility and Option-Adjusted Spreads
The OAS of a security is directly linked to the volatility assumption (
       Volatility Assumption (σ) Increases in Pricing Model
                               │
            ┌──────────────────┴──────────────────┐
            ▼                                     ▼
   Embedded Call Value                   Embedded Put Value
        Increases                             Increases
            │                                     │
            ▼                                     ▼
      Calculated OAS                        Calculated OAS
        DECREASES                             INCREASES
 (Less spread needed to               (More spread needed to
   match market price)                  match market price)
Impact on Callable Bonds
- If the analyst increases the interest rate volatility assumption in the model, the model calculates a higher value for the embedded call option (
- To maintain the target equation where the modeled bond value matches the fixed market price, the model must apply a lower spread over benchmark rates.
- Therefore, as assumed volatility increases, the calculated OAS of a callable bond decreases.
- Risk of Mis-specification: If an analyst assumes an incorrectly low volatility, the model underestimates call option value, causing the calculated OAS to be artificially inflated, falsely suggesting the bond is cheap (undervalued).
Impact on Putable Bonds
- If the analyst increases the interest rate volatility assumption in the model, the model calculates a higher value for the embedded put option (
- To pull the higher theoretical bond value back down to match the fixed market price, the model must apply a higher spread over benchmark rates.
- Therefore, as assumed volatility increases, the calculated OAS of a putable bond increases.
The table below contrasts these relationships across bond structures:
| Metric / Scenario | Callable Bond | Putable Bond |
| Formula for Option Cost (bps) | 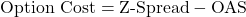 | 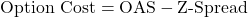 |
| Spread Hierarchy | 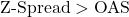 | 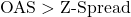 |
Effect of Higher Volatility ( | Option Value Increases | Option Value Increases |
| Effect of Higher Volatility ( | OAS Decreases | OAS Increases |


Effective Duration of Option-Embedded Bonds
Standard Macaulay duration and Modified duration assume that cash flows are fixed and independent of interest rate movements. Because embedded options cause cash flows to alter dynamically when rates shift, traditional duration measures fail for callable and putable debt.
To accurately evaluate rate sensitivity, analysts use Effective Duration (

Calculation of Effective Duration
Effective duration is calculated numerically using a binomial interest rate tree model through the following procedure:
- Shift the benchmark yield curve down by a small parallel amount (


- Shift the benchmark yield curve up by the same parallel amount (

- Apply the effective duration formula:


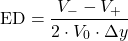

Where:


Interpreting Effective Duration
Effective duration quantifies exposure to parallel yield curve risk. An effective duration of 


Comparison of Effective Durations: Callable, Putable, and Straight Bonds
The presence of embedded options reduces the effective duration of fixed-income instruments relative to equivalent straight debt, but the mechanisms and regions of duration reduction differ.
    Bond Price
        ▲
        │                               / Putable Bond Floor
        │                             /
        │                           / ── Straight Bond
        │   Callable Price  ──────/ /
        │        Ceiling  ───────/ /
        │                       / /
        │                      / /
        └─────────────────────┴─┴────────────────────────►
                             Interest Rates
1. Callable Bonds vs. Straight Bonds
- When Rates Are High (Out-of-the-Money Call): The call option is deep out-of-the-money. The probability of early call is negligible. The cash flows behave like an option-free debt structure, making:
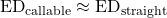

- When Rates Are Low (In-the-Money Call): As rates drop, the price approaches the call price ceiling (
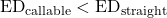
As a result, 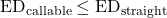
2. Putable Bonds vs. Straight Bonds
- When Rates Are Low (Out-of-the-Money Put): The put option is deep out-of-the-money. Investors will hold the bond to maturity. The security behaves like a straight bond:
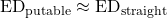
- When Rates Are High (In-the-Money Put): As rates rise, the straight bond depreciates, but the put option approaches exercise value (
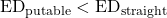
As a result, 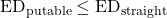
Summary inequality across all rate states:
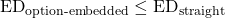

One-Sided Durations and Key Rate Durations
While effective duration summarizes price sensitivity to a single, symmetrical parallel yield curve shift, complex option-embedded bonds exhibit non-linear and non-parallel sensitivities that require specialized diagnostic duration metrics.
One-Sided Durations
Because embedded options induce asymmetrical price responses, a
One-Sided Durations measure price sensitivity to upward and downward rate shifts separately:
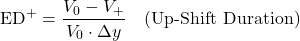

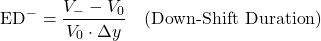

- For Callable Bonds near the Call Price:


- For Putable Bonds near the Put Price:

Key Rate Durations
Key Rate Duration (or partial duration) measures a bond’s price sensitivity to a change in a single specific benchmark market rate (e.g., 2-year, 5-year, 10-year, 30-year spot rates) while keeping all other key rates along the yield curve constant.
Key rate duration is essential for valuing bonds with embedded options because option exercise decisions depend on specific short-to-intermediate rates on the call/put date rather than overall yield curve shifts:
- Non-Parallel Yield Curve Shifts: Yield curves frequently twist, steepen, or flatten. Key rate duration highlights where along the curve the bond holds interest rate concentration risk.
- Maturity Realignment: For a callable bond trading near its call price, the key rate duration corresponding to the call date spikes, while key rate durations corresponding to post-call maturities collapse to zero.
Effective Convexity of Option-Embedded Bonds
Convexity measures the rate of change of duration with respect to interest rates (the second derivative of price with respect to yield). For an option-free straight bond, convexity is always positive (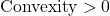

When options are embedded, the price-yield relationship becomes non-linear and can exhibit Negative Convexity.
    Price
      ▲
      │                      Negative Convexity Region (Callable Bond)
      │                   .─'─.
      │               .─'      `─.
      │           .─'             `─.
      │       .─'                    `─. Straight Bond (Positive Convexity)
      │   .─'                           `─.
      └───────────────────────────────────────────────────► Yield
Effective Convexity Formula
Like duration, effective convexity (

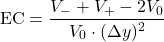

Convexity Profiles Comparison
1. Straight Bonds (Always Positive Convexity)
For straight debt, 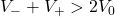

2. Callable Bonds (Negative Convexity Region)
When interest rates fall to levels where the call option goes deep into the money, the pricing dynamics reverse:
- The price curve turns concave (
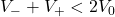
- In a negative convexity regime, as interest rates fall, duration shortens (price gains flatten out). As interest rates rise, duration lengthens (price losses accelerate).
- Investors demand a yield premium (higher yield-to-maturity) on callable debt to compensate for holding this unfavorable negative convexity profile.
3. Putable Bonds (Enhanced Positive Convexity)
- When rates are high and the put option is near or in the money, the pricing curve exhibits Enhanced Positive Convexity.
- As interest rates rise, duration shortens rapidly toward the put exercise date, truncating downside losses. As rates fall, duration lengthens toward final maturity, capturing maximum price appreciation.
- This favorable profile means putable bonds maintain higher positive convexity than straight bonds when interest rates rise.
| Security Type | Low Interest Rates | High Interest Rates |
| Straight Bond | Positive Convexity ( | Positive Convexity ( |
| Callable Bond | Negative Convexity ( | Positive Convexity ( |
| Putable Bond | Positive Convexity ( | Enhanced Positive Convexity ( |


Floating-Rate Bonds with Caps and Floors
Floating-rate notes (FRNs) reset their coupon periodically based on a reference rate (such as 180-day SOFR) plus a margin (

Capped Floating-Rate Notes
A capped FRN sets a maximum allowable coupon rate (

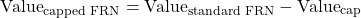

- Valuation via Trees: At each reset node in a binomial interest rate tree, the coupon payment for the upcoming period is capped:
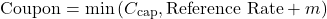

- Impact of Volatility: When interest rate volatility increases, the value of the embedded interest rate cap (

Floored Floating-Rate Notes
A floored FRN sets a minimum allowable coupon rate (

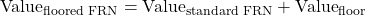

- Valuation via Trees: At each reset node in the tree, the coupon payment is floored:
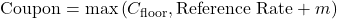

- Impact of Volatility: When interest rate volatility increases, the value of the embedded interest rate floor (


Convertible Bonds: Defining Features
A convertible bond gives the bondholder the right to exchange the bond for a specified number of shares of the issuer’s common stock. Convertible debt is a hybrid security combining fixed-income downside protection with equity market upside participation.
Key Terminology and Structural Definitions
- Conversion Ratio (


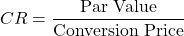

- Conversion Price (

- Conversion Value (Parity Value): The current market value of the equity shares into which the bond can be converted:
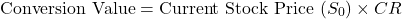

- Straight Value (Investment Value): The value of the convertible bond strictly as a fixed-income instrument, calculated as the present value of its coupons and principal repayment discounted at market yields for non-convertible debt of equivalent credit quality.
- Minimum Value of a Convertible Bond: A convertible bond cannot trade below the greater of its straight bond value or its conversion value without creating an immediate risk-free arbitrage opportunity:
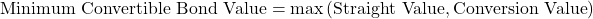

Components of Convertible Bond Value
To analyze a convertible bond, analysts evaluate several valuation components and yield spreads:
1. Market Conversion Price
The actual price an investor pays for equity exposure when purchasing the convertible bond in the market:
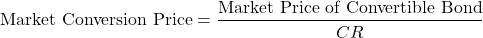

2. Market Conversion Premium per Share
The excess price paid per share over the current spot stock price:
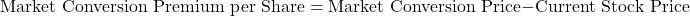

Expressed as a percentage:
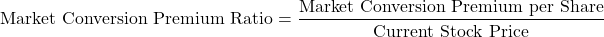

3. Premium Payback Period (Breakeven Time)
The time (in years) required for the extra coupon yield earned from holding the convertible bond rather than the underlying equity shares to recover the conversion premium paid:
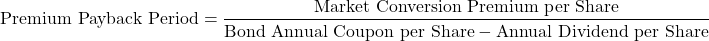

Where:

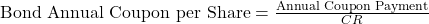
4. Premium Over Straight Value
The percentage excess of the convertible bond’s market price over its straight investment value:
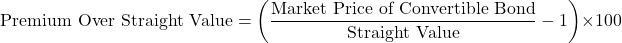

This metric measures downside protection. A low premium indicates that the straight value provides an immediate floor; a high premium indicates that the straight bond floor is distant and the convertible behaves primarily like stock.
Valuation of Convertible Bonds in an Arbitrage-Free Framework
Convertible bonds often contain additional embedded features, such as issuer call options (used to force conversion) and investor put options. Valuing a complex convertible bond requires an integrated framework combining stock price dynamics and interest rate trees.
Combined Interest Rate and Equity Trees
Because a convertible bond depends on two underlying stochastic variables—interest rates and the underlying common stock price—practitioners use two-factor binomial lattices or Monte Carlo simulation:
- Equity Dynamics: The stock price is modeled as a lognormal random walk across nodes.
- Interest Rate Dynamics: At each node, default probabilities and term-structure discount factors are mapped.
- Backward Induction with Multi-Option Exercise Rules: At every lattice node
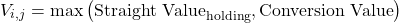

If the bond is also callable by the issuer at
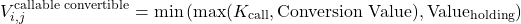

Risk-Return Characteristics of Convertible Bonds
Convertible bonds exhibit a non-linear risk-return profile that shifts dynamically between fixed-income and equity characteristics based on the performance of the underlying stock.
    Convertible Price
          ▲
          │                                  / Equity Equivalent Zone
          │                                /  (High Sensitivity to Stock)
          │                              /
          │       Hybrid Region        /
          │       (Asymmetric)       /
          │                       .─'
          │   Straight Value   .─'
          │       Floor      .─'
          │ ─────────────────
          └─────────────────────────────────────────► Stock Price
Profile Across Stock Price Regimes
- Deep Out-of-the-Money (“Busted” Convertibles):
- When the underlying stock price is far below the conversion price, the conversion value is near zero.
- The convertible bond trades almost purely on its Straight Value.
- Behavior: High sensitivity to interest rates and credit spreads; near-zero correlation with stock price movements.
- At-the-Money (Hybrid Region):
- When the stock price is close to the conversion price, the bond operates in a hybrid state.
- Behavior: Asymmetric risk-return profile. As the stock price rises, the bond participates in equity gains; as the stock price falls, downside losses are cushioned by the straight bond floor.
- Deep In-the-Money (Equity Equivalents):
- When the stock price is far above the conversion price, the conversion value dominates the pricing structure.
- The bond trades at a near-zero conversion premium.
- Behavior: Near 1.0 delta sensitivity with the underlying common stock; interest rate risk becomes negligible.
Risk-Return Trade-Off Matrix
The following table summarizes the comparative performance of convertible debt relative to straight bonds and common equity:
| Performance / Risk Attribute | Straight Bond | Common Equity | Convertible Bond |
| Primary Value Driver | Interest Rates / Credit Spreads | Earnings Growth / Macroeconomy | Combination of Equity Price & Interest Rates |
| Downside Risk | Credit Default / Rate Rises | Unlimited (down to zero) | Bounded by Straight Investment Value Floor |
| Upside Participation | Capped at Par / Yield | Unlimited | High (tracks Equity less Conversion Premium) |
| Yield / Income | Highest Fixed Income Coupon | Lowest (Variable Dividends) | Moderate (Lower than straight bond, higher than dividend) |
| Capital Structure Priority | Senior / Subordinated Debt | Common Equity (Lowest Priority) | Senior / Subordinated Debt (Higher priority than equity) |
| Convexity Profile | Modest Positive Convexity | Linear Equity Delta | Enhanced Asymmetric Positive Convexity |

