Mastering Trade Strategy and Execution is a critical determinant of long-term investment performance for institutional asset managers, hedge funds, corporate treasuries, and sovereign wealth entities.
This comprehensive analysis evaluates the underlying motivations driving market orders, details the structural inputs required to select optimal trading strategies, compares primary execution benchmarks, provides a real-world institutional trade recommendation, breaks down algorithmic trading classes, contrasts asset class market microstructures, presents rigorous trade cost measurement methodologies, and establishes robust corporate governance frameworks for trade execution.
Introduction to Trade Strategy and Execution
In modern global financial markets, portfolio management decisions do not generate investment returns in a vacuum. The transformation of investment ideas into portfolio performance requires passing through the operational conduit of trade implementation. Global investment managers such as BlackRock and Vanguard manage trillions of dollars in client capital, where even a minor inefficiency of a few basis points during execution can erode billions of dollars in realized portfolio value over time.
Trade implementation represents the friction point between theoretical strategy and real-world market dynamics. Financial markets are characterized by varying degrees of liquidity, bid-ask spreads, venue fragmentation, dealer networks, and price volatility. Consequently, institutional investors must view trading not as a mechanical administrative task, but as an active risk management discipline. A structured trading strategy aligns the portfolio manager’s urgency, risk tolerance, and information speed with market liquidity to minimize transaction costs and prevent market signaling.
Motivations to Trade and Their Relationship to Trading Strategy
Understanding the underlying motivation for entering the market is the foundational step in formulating an effective execution strategy. Trading motivations dictate the trader’s level of urgency, tolerance for market impact, and acceptable risk profile.
Profit Seeking and Alpha Capture
When a trade is driven by short-term tactical information or fundamental research indicating an mispriced security, the primary objective is rapid execution to capture temporary alpha. Information decays quickly once market participants absorb new information. In these scenarios, the trader exhibits high urgency and is willing to accept higher implicit trading costs—such as crossing the bid-ask spread or incurring market impact—to ensure immediate order completion before price discovery moves against the position.
Risk Management and Asset Allocation Rebalancing
Portfolio managers frequently trade to realign portfolio exposures with targeted strategic asset allocations, manage factor risk, adjust duration in bond portfolios, or adhere to strict risk constraints. Because the goal is risk control rather than short-term profit capture, execution urgency is typically moderate. Strategies focus on minimizing transaction costs through scheduled liquidity algorithms or opportunistic trading across multiple execution venues.
Cash Flow Management and Liquidity Needs
Liquidity-driven trading occurs when funds experience client inflows or outflows, mandate dividend payments, or settle debt obligations. In mutual funds and exchange-traded funds (ETFs), daily subscriptions and redemptions require prompt portfolio rebalancing. For inflows, managers may deploy cash patient-driven algorithms or equity index futures to maintain market exposure; for redemptions, managers must liquidate securities systematically to meet liquidity requirements while mitigating adverse selection.
Regulatory, Mandate, and Structural Drivers
Index reconstitutions, credit rating downgrades, leverage adjustments, and tax-loss harvesting create obligatory trading mandates. In index rebalancing—such as changes to the S&P 500 or MSCI World indices—massive institutional capital flows move simultaneously into or out of specific securities. Trading strategies in these contexts prioritize benchmark matching (such as executing at the market close) to reduce tracking error relative to the index.
Key Inputs Guiding the Selection of a Trading Strategy
Selecting the appropriate trading strategy requires evaluating multiple quantitative and qualitative inputs across order characteristics, market conditions, and institutional constraints.
Order Characteristics and Relative Size
The magnitude of an order relative to normal market liquidity is the most critical determinant of execution risk. Order size is commonly measured as a percentage of Average Daily Volume (ADV). Small orders (under 1% of ADV) generally pose minimal market impact and can be executed via direct market access or simple algorithms. Conversely, large block orders (exceeding 10% to 15% of ADV) require multi-day execution, dark pool routing, or capital commitment from broker-dealer desks to avoid moving the market.
Market Liquidity and Asset Fragmentation
Market microstructure varies significantly across global venues. Traders must assess liquidity availability, quote size, bid-ask spreads, and venue fragmentation. In highly fragmented equity markets across illuminated exchanges and alternative trading systems (ATS), liquidity seeking strategies rely on Smart Order Routers (SORs) to capture dispersed depth. In quote-driven or dealer markets, liquidity depends on dealer inventory and balance sheet availability.
Price Volatility and Alpha Decay Rate
High market volatility elevates price risk during the execution window. If a security exhibits significant price volatility alongside a high alpha decay rate, prolonged execution exposes the trade to substantial timing risk. The trader must calculate the trade-off between the certainty of immediate market impact costs versus the uncertain risk of adverse price movement over time.
User Constraints and Risk Tolerance
Portfolio managers establish explicit guidelines regarding maximum participation rates in the market (e.g., capping trading at 10% of total volume), execution time horizons, allowed venues, credit counterparty limits, and explicit commission budgets.
Comparing Benchmarks for Trade Execution
To evaluate execution quality and measure transaction costs objectively, institutional investors compare trade execution prices against standardized market benchmarks. Benchmarks are categorized by their temporal relationship to the trading process.
| Benchmark Category | Benchmark Type | Primary Purpose & Mechanics | Key Advantages | Key Limitations | Optimal Scenario |
| Pre-Trade | Decision Price / Arrival Price | Captures the prevailing market price at the exact moment the portfolio manager makes the investment decision or transmits the order. | Measures total transaction cost, including market movement and delay cost during execution. | Can penalize traders for broad market price movements outside their control. | High-urgency alpha trades where speed of execution is critical. |
| Pre-Trade | Previous Day’s Close | Uses the closing price of the prior trading session as the price reference. | Completely fixed and known prior to market open; immune to intra-day gaming. | Obsolete if overnight news or market gap-opens significantly alter valuation. | Index funds tracking daily benchmark performance or quantitative models. |
| Post-Trade | Closing Price | Compares execution prices against the official market closing auction price. | Guarantees benchmark matching; eliminates tracking error against index valuation. | Vulnerable to closing auction volatility; exposes trades to full intraday price movement. | Index rebalancing, daily fund NAV pricing, and mutual fund cash flows. |
| In-Flight / Interval | Volume-Weighted Average Price (VWAP) | Calculates the volume-weighted average trading price across the entire trading horizon. | Measures execution against average market liquidity; easy to verify and standardize. | Can be gamed by brokers; does not penalize execution delays during trending markets. | Low-urgency, liquidity-seeking trades representing moderate volume relative to ADV. |
| In-Flight / Interval | Time-Weighted Average Price (TWAP) | Calculates the unweighted arithmetic average price over a specified time interval. | Simple to implement; prevents over-participation during end-of-day market spikes. | Ignores natural intraday volume distributions (such as U-shaped liquidity curves). | Securities with flat intraday volume profiles or illiquid, thinly traded assets. |
Recommending and Justifying a Trading Strategy: Institutional Case Study
To illustrate the application of trade selection principles, consider the following institutional scenario:
An equity portfolio manager at a global asset management firm decides to purchase 500,000 shares of Apple as part of a fundamental portfolio realignment. The average daily volume for Apple is 50,000,000 shares, meaning the order represents exactly 1% of ADV. The security trades across highly fragmented illuminated exchanges and dark pools with tight bid-ask spreads. The portfolio manager’s fundamental investment horizon is six months, indicating low short-term alpha decay, but overall broad market volatility is elevated due to macroeconomic announcements.
Strategy Recommendation and Justification
The recommended execution strategy is a low-urgency, algorithmic implementation utilizing an Implementation Shortfall (IS) / Liquidity-Seeking Algorithm paired with dark pool aggregation across a four-hour trading horizon.
- Low Market Impact Risk: At 1% of ADV, a 500,000 share buy order in Apple is modest relative to overall liquidity. Executing the trade over four hours implies participating at less than 3% to 5% of average volume during that window, minimizing market footprint.
- Mitigation of Timing Risk: Given elevated macro volatility, an Implementation Shortfall algorithm dynamically adjusts participation rates—accelerating execution when favorable liquidity is present or when price moves away, and slowing down when market impact rises.
- Dark Pool Routing: Routing non-displayed parent order child blocks into high-quality dark pools allows the desk to interact with institutional midpoint liquidity, capturing price improvement (saving half the bid-ask spread) while avoiding market signaling.
- Avoidance of Static VWAP: A static VWAP strategy would blindly push child orders into the market regardless of price momentum. The IS algorithm offers superior adaptation to intraday price trends.
Factors Determining the Selection of Algorithmic Trading Classes
Algorithmic trading automates order routing and execution based on pre-programmed parameters. Institutional trading desks choose algorithm classes based on specific market drivers, order urgency, and liquidity conditions.
                        ┌──────────────────────────────────────────┐
                        │        Institutional Order Input          │
                        └────────────────────┬─────────────────────┘
                                             │
                        ┌────────────────────▼─────────────────────┐
                        │      Evaluate Urgency & Order Size       │
                        └──────┬────────────────────────────┬──────┘
                               │                            │
             ┌─────────────────▼──────────┐      ┌──────────▼─────────────────┐
             │ High Urgency / High Alpha  │      │ Low Urgency / Large Size  │
             └─────────────────┬──────────┘      └──────────┬────────────────┘
                               │                            │
       ┌───────────────────────▼─────────┐        ┌─────────▼────────────────────────┐
       │ Implementation Shortfall (IS)   │        │ Scheduled / Liquidity Seeking    │
       │   - Minimizes total shortfall   │        │   - VWAP, TWAP, POV              │
       │   - Dynamic participation rate  │        │   - Dark pool MIDPOINT execution │
       └─────────────────────────────────┘        └──────────────────────────────────┘
Impact-Driven / Scheduled Algorithms
Scheduled algorithms divide parent orders into smaller child orders distributed over time based on mathematical schedules.
- Volume-Weighted Average Price (VWAP): Releases child orders matching the historical intraday volume profile (typically U-shaped). Best suited for orders under 10% of ADV with low urgency where matching the market average price is the primary benchmark.
- Percentage of Volume (POV): Executes dynamically as a fixed percentage of real-time market volume (e.g., participating at 5% of traded volume). If market volume expands, execution accelerates; if market volume dries up, execution slows automatically.
- Time-Weighted Average Price (TWAP): Slices orders evenly across equal time intervals. Optimal for illiquid assets or markets without distinct volume patterns.
Cost-Driven / Opportunistic Algorithms
Cost-driven algorithms solve an optimization problem balancing execution risk against market impact cost.
- Implementation Shortfall (IS) Algorithms: Also known as arrival price algorithms, these dynamically trade to minimize total implementation shortfall. If the price moves adversely relative to the arrival price, the algorithm accelerates trading to prevent further slippage; if price movements are favorable, it trades more passively.
- Liquidity-Seeking Algorithms: Constantly scan lit exchanges and dark venues for block liquidity. These algorithms utilize Smart Order Routers (SOR) to sweep dark pools at midpoint prices before displaying child orders on public books, prioritizing venues with high fill rates and low toxic order flow.
| Algorithm Class | Core Mechanics | Primary Decision Inputs | Key Risk Managed |
| VWAP / Scheduled | Follows historical volume distributions over time. | Order size relative to ADV, baseline volume profiles. | Market impact cost and benchmark tracking error. |
| POV (Participation) | Trades as a dynamic ratio of real-time market volume. | Real-time market volume, target participation percentage. | Execution duration risk in variable volume environments. |
| Implementation Shortfall | Dynamically trades to minimize price slippage from arrival price. | Alpha decay rate, security volatility, risk aversion parameter. | Balance between market impact and timing/price risk. |
| Liquidity-Seeking / Dark | Sweeps dark venues and midpoint order books across fragmented markets. | Order size, venue fill rates, spread widths, adverse selection metrics. | Information leakage and market signaling. |
Contrasting Market Characteristics Across Asset Classes
Trade implementation strategies must adapt to the unique market microstructure, settlement procedures, and liquidity architecture of each major financial asset class. Institutional desks trading across multi-asset portfolios interface with distinct execution protocols.
Equity Markets
Equities trade primarily on centralized, order-driven electronic exchanges and alternative trading systems. Market structure features high quote transparency, continuous double auctions, order book visibility, and substantial fragmentation. Execution is highly automated through algorithmic routing, dark pool aggregation, and direct market access provided by major prime brokers such as Goldman Sachs and JPMorgan Chase.
Fixed Income Markets
Fixed income instruments—including corporate bonds, municipal bonds, and structured products—trade predominantly in decentralized, quote-driven Over-The-Counter (OTC) dealer markets. Liquidity is highly bifurcated: newly issued “on-the-run” sovereign bonds trade with high liquidity on electronic dealer platforms, whereas tens of thousands of corporate bond issues are illiquid “off-the-run” assets held to maturity by institutional investors. Trade implementation relies heavily on Request for Quote (RFQ) protocols across electronic platforms, direct dealer negotiation, and portfolio trading desks.
Options and Futures Markets
Exchange-traded derivatives trade on centralized futures and options exchanges such as CME Group. Markets feature high standardization, central counterparty (CCP) clearing, order book transparency, and substantial leverage. Options execution involves multi-leg strategies (e.g., straddles, delta-neutral spreads) where trade execution must account for underlying asset liquidity, implied volatility, options greeks, and margin requirements.
OTC Derivatives Markets
OTC derivatives—such as interest rate swaps (IRS), credit default swaps (CDS), and customized foreign exchange options—feature bilateral contract structures. Following post-financial crisis reforms (such as Dodd-Frank and EMIR), standardized OTC derivatives are subject to mandatory clearing through central counterparties and trading on Swap Execution Facilities (SEFs). Non-cleared customized derivatives remain reliant on bilateral International Swaps and Derivatives Association (ISDA) documentation, requiring careful evaluation of dealer counterparty credit risk and credit support annex (CSA) collateral requirements.
Spot Foreign Exchange (Forex) Markets
Spot forex is the world’s largest, most liquid financial market, operating continuously 24 hours a day across global financial hubs. Foreign exchange lacks a single centralized exchange; instead, it operates as an OTC interbank tiered network. Liquidity is aggregated through primary electronic broking platforms (EBS and Refinitiv Matching), major liquidity providers like Citadel Securities, and multi-dealer platforms. Spreads on major currency pairs (USD/EUR, USD/JPY) are extremely narrow, and trade execution relies on algorithmic order routing and direct API integration.
| Asset Class | Primary Market Architecture | Price Discovery Mechanism | Primary Execution Protocol | Primary Execution Challenge |
| Equities | Centralized & Fragmented Exchanges / ATS | Continuous Order-Driven Order Books | Algorithmic Routing, SOR, Dark Pools | Fragmented liquidity and information leakage |
| Fixed Income | Decentralized OTC Dealer Network | Quote-Driven / Dealer Inventory Quotes | Request for Quote (RFQ), Portfolio Trading | Extreme illiquidity in off-the-run corporate issues |
| Options & Futures | Centralized Derivatives Exchanges | Order-Driven Central Limit Order Books | Direct Market Access, Algorithmic Slicing | Managing delta hedging and multi-leg option execution |
| OTC Derivatives | Bilateral & Swap Execution Facilities (SEF) | Dealer Quotes / Central Clearing House | Negotiated Dealer RFQ, Electronic SEFs | Counterparty credit risk and collateralization cost |
| Spot Currency | Global Decentralized Interbank Network | Continuous ECN / Aggregated Dealer Spreads | Electronic Aggregators, Direct API, Algorithmic | Managing multi-venue latency and top-of-book phantom depth |
Measuring Trade Costs and Determining Total Cost of Trade
Evaluating trade cost requires breaking down transaction expenses into explicit and implicit components. Explicit costs are readily observable and contractual, whereas implicit costs are hidden and derived from market friction and price movements.
                                  ┌──────────────────────────────────────────┐
                                  │           Total Trade Cost               │
                                  └────────────────────┬─────────────────────┘
                                                       │
                      ┌────────────────────────────────┴────────────────────────────────┐
                      │                                                                 │
        ┌─────────────▼─────────────┐                                     ┌─────────────▼─────────────┐
        │       Explicit Costs      │                                     │       Implicit Costs      │
        └─────────────┬─────────────┘                                     └─────────────┬─────────────┘
                      │                                                                 │
    ┌─────────────────┴─────────────────┐                       ┌───────────────────────┼───────────────────────┐
    │ - Commissions                     │                       │                       │                       │
    │ - Exchange & Clearing Fees        │             ┌─────────▼─────────┐   ┌─────────▼─────────┐   ┌─────────▼─────────┐
    │ - Financial Transaction Taxes     │             │ Bid-Ask Spread    │   │ Market Impact     │   │ Delay / Slippage  │
    └───────────────────────────────────┘             └───────────────────┘   └───────────────────┘   └───────────────────┘
                                                                                                      │ Opportunity Cost  │
                                                                                                      └───────────────────┘
Explicit Costs versus Implicit Costs
- Explicit Costs: Direct payments including broker commissions, exchange access fees, clearing and settlement charges, and statutory financial transaction taxes.
- Implicit Costs: Indirect economic costs resulting from market dynamics during trade execution:
- Bid-Ask Spread: The cost of crossing the market spread between the highest buyer bid and lowest seller ask.
- Market Impact (Price Impact): The upward price movement caused by a buy order (or downward movement caused by a sell order) due to consuming market liquidity.
- Delay Cost (Slippage): Adverse price movements occurring between the time the investment decision is finalized and the time the order is submitted to the market.
- Opportunity Cost: The unrealized profit foregone (or loss avoided) on the unexecuted portion of an order if the market moves away and the trade remains incomplete.
The Implementation Shortfall Framework
Implementation Shortfall (IS) measures the total friction of trade execution by comparing the actual return of a real portfolio against the theoretical return of a hypothetical “paper portfolio” executed instantly at the decision price with zero transaction fees.
The explicit formula for Implementation Shortfall is expressed as:
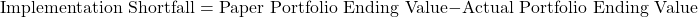

To decompose Implementation Shortfall into its underlying cost components for a Buy Order, we utilize the formal mathematical model:
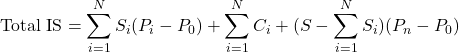

Where:


Worked Numerical Calculation Example
An asset manager decides to purchase 

The trading timeline unfolds as follows:
- Order decision made at

- Order transmitted to the broker when market price (Arrival Price,

- The broker executes


- Total explicit commissions and fees (

- The remaining


Step-by-Step Calculation
1. Paper Portfolio Cost:
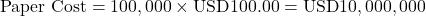

2. Actual Portfolio Cost & Terminal Value:
- Actual Executed Shares Value:
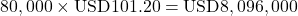
- Explicit Commissions:

- Cost of Unexecuted Shares evaluated at final price (
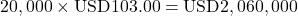
- Total Actual Cost Basis:
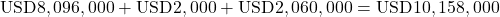


3. Total Implementation Shortfall:
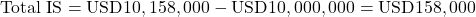

Expressing Total Implementation Shortfall in basis points relative to initial portfolio value:
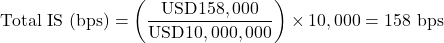

Decomposition of Shortfall Components
| Shortfall Component | Mathematical Formula | Calculation | USD Cost | Basis Points |
| Explicit Fees | | Direct broker commissions paid | USD2,000 | 2 bps |
| Delay Cost | 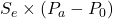 | 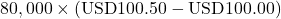 | USD40,000 | 40 bps |
| Realized Market Impact | 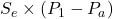 | 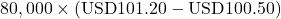 | USD56,000 | 56 bps |
| Opportunity Cost | 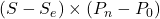 | 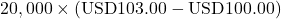 | USD60,000 | 60 bps |
| Total Implementation Shortfall | Sum of Components | USD2,000 + USD40,000 + USD56,000 + USD60,000 | USD158,000 | 158 bps |


This detailed attribution demonstrates that while explicit commissions were negligible (2 bps), implicit costs—specifically market impact (56 bps) and opportunity cost from incomplete execution (60 bps)—accounted for the vast majority of transaction friction.
Evaluating the Execution Performance of a Trade
Evaluating trade execution quality requires robust Transaction Cost Analysis (TCA). TCA assesses whether a trade met best execution standards given prevailing market conditions.
Transaction Cost Analysis (TCA) Framework
- Pre-Trade TCA: Econometric models estimate expected explicit and implicit costs prior to execution. Inputs include order size, volatility, ADV, and market depth. Pre-trade TCA helps select optimal algorithm parameters and trade horizons.
- In-Trade TCA: Real-time monitoring tracks active orders against benchmarks (e.g., arrival price, intraday VWAP curve). If execution slippage exceeds predetermined statistical thresholds, traders can intervene and modify routing parameters.
- Post-Trade TCA: Comprehensive reporting analyzes executed trade prices against arrival price, VWAP, TWAP, and market close benchmarks across brokers, venues, algorithms, and trading desks.
Evaluating Broker and Algorithm Performance
When evaluating broker performance, institutional desks must control for trade difficulty. Comparing a simple 0.1% ADV liquid trade against a 20% ADV illiquid trade without controlling for order difficulty distorts performance assessment. Asset managers aggregate trade execution metrics across peer groups over hundreds of trades to assess whether execution algorithms consistently deliver positive price improvement relative to arrival price.
Evaluating Governance, Trading Procedures, Disclosures, and Record Keeping
Regulatory bodies globally—such as the SEC in the United States and ESMA under MiFID II in Europe—mandate that institutional investment firms establish strict governance procedures to ensure Best Execution on behalf of investors.
Best Execution Policy and Oversight
Investment firms must establish a formalized, written Best Execution Policy approved by senior management. A dedicated Trade Governance Committee (comprising chief compliance officers, heads of trading, portfolio managers, and risk managers) must meet quarterly to review broker selection, algorithmic execution metrics, venue execution quality, counterparty credit risk, and TCA reports.
Order Allocation and Fair Treatment Policies
To prevent conflicts of interest and ensure fair treatment across client accounts, investment management firms must implement strict order allocation procedures:
- Pre-Trade Allocation: Portfolio managers must document target account allocations prior to submitting block orders to the trading desk.
- Pro-Rata Post-Trade Allocation: If a block trade is partially filled, executed shares and transaction costs must be allocated across participating client accounts on a systematic, non-discriminatory pro-rata basis based on initial order size. Allocation adjustments that favor performance-fee accounts or proprietary accounts over standard mandates are strictly prohibited.
Soft Dollars, Payment for Order Flow (PFOF), and Conflicts of Interest
Institutional governance policies must strictly govern broker compensation and soft dollar arrangements. Soft dollars occur when a portion of broker commission payments is used to purchase eligible investment research services. Governance frameworks require firms to separate research payments from execution charges (unbundling under MiFID II rules) to ensure execution venue routing is guided solely by execution quality rather than research access. Furthermore, payment for order flow (PFOF) arrangements that create structural conflicts between broker compensation and client price improvement must be prohibited or fully disclosed.
Record Keeping, Audit Trails, and Regulatory Compliance
Institutional trading desks must maintain complete, time-stamped audit trails for every order life cycle step—from portfolio decision generation, broker transmission, and child order algorithmic routing, to ultimate clearing and settlement. In accordance with MiFID II and SEC record-keeping guidelines, trade records, electronic communications, algorithmic decision trees, and venue disclosures must be archived for a minimum of five to seven years to ensure full trade reconstruction capabilities during regulatory examinations.
Conclusion
Optimizing Trade Strategy and Execution is an essential discipline within institutional portfolio management. Minimizing explicit and implicit transaction costs directly preserves portfolio performance, ensuring that investment ideas translate into realized investor gains. By aligning trade motivations with tailored algorithmic strategies, adjusting execution protocols to distinct asset class microstructures, conducting rigorous implementation shortfall analysis, and enforcing transparent governance and audit controls, asset managers establish a best-in-class trade execution engine capable of navigating complex modern global capital markets.

