The term structure of interest rates is a foundational concept in fixed-income analysis, corporate finance, and monetary economics. It reflects the relationship between interest rates (or yields) and the time to maturity of debt instruments.
Financial decision-makers—ranging from corporate chief executive officers and treasury managers to institutional investors, portfolio managers, and economic advisors—rely heavily on the term structure to value securities, manage portfolio duration, and forecast macroeconomic trends. Understanding how to navigate between spot rates, par rates, and forward rates is essential for pricing complex financial contracts and executing risk-management strategies.
This comprehensive analysis explores these core metrics, details their mathematical interrelationships, and compares the yield curves they generate.
Spot Rates, the Spot Curve, and Bond Pricing
Defining Spot Rates and the Spot Curve
A spot rate is the yield-to-maturity on a zero-coupon default-risk-free security (such as a zero-coupon government bond or Treasury STRIP) maturing at a specific point in time. Often referred to as zero rates, spot rates represent the true time-value of money for single cash flows occurring at distinct future dates, as they are free from reinvestment risk associated with intermediate coupon payments.
The spot curve (or zero curve) is a graphical representation or schedule of spot rates plotted against their respective maturities. Because spot rates discount individual cash flows directly back to the present without intermediate cash flow complications, the spot curve provides the theoretical benchmark for pricing all other fixed-income instruments under no-arbitrage conditions.
Calculating the Price of a Bond Using Spot Rates
Under the no-arbitrage principle, the price of a coupon-bearing bond must equal the present value of its future cash flows (coupon payments and the repayment of principal), with each cash flow discounted at its unique maturity-matched spot rate.
The general formula for the price ( ) of a bond with annual coupon payments is expressed as:
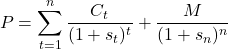
Where:
 = Coupon payment at time

 = Maturity value (par value) of the bond
 = Spot rate for maturity
 = Total number of periods to maturity
Practical Calculation Example
Consider a 3-year annual-pay corporate bond with a par value of USD 1,000 and a coupon rate of 5.00%. Suppose the prevailing spot rates for maturities 1, 2, and 3 years are:


The cash flows are:
- Year 1: USD 50
- Year 2: USD 50
- Year 3: USD 1,050 (USD 50 coupon + USD 1,000 principal)
Using the spot rates to discount each cash flow:
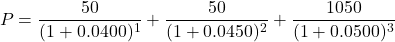
Computing each component:
- Year 1 present value:
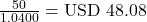
- Year 2 present value:
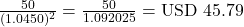
- Year 3 present value:
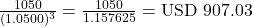
Summing these present values yields the no-arbitrage bond price:
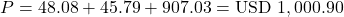
Par Rates, Forward Rates, and Inter-Curve Calculations
Defining Par and Forward Rates
- Par Rate: A par rate (or par yield) is the coupon rate that makes the price of a coupon-bearing bond equal to its par (face) value. On a par curve, every maturity point represents a hypothetical or actual benchmark bond trading precisely at par (typically 100% of face value). Par rates are derived from spot rates using a iterative pricing relationship where the market value equals par.
- Forward Rate: A forward rate (
 ) is the locked-in interest rate for a borrowing or lending transaction that will take place at a specified future date. Rather than discounting cash flows back to today, forward rates capture the incremental or marginal return required for extending an investment horizon across specific future periods. They reflect market expectations and the no-arbitrage pricing condition across different maturities.
Calculating Par Rates from Spot Rates
To compute a par rate ( ) for an -period bond, we leverage the condition that the bond’s price must equal its par value (e.g., USD 100). Given known spot rates (
 ), the coupon rate satisfies:
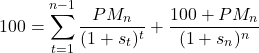
Rearranging terms allows us to isolate and solve for the par rate:
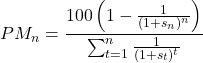
Calculating Forward Rates from Spot Rates
Forward rates are derived directly from spot rates under the no-arbitrage principle. The fundamental principle states that investing for years at the -year spot rate must generate the exact same terminal wealth as investing for  years at the -year spot rate and rolling over the proceeds at the forward rate from year to year .
The general formula for the annualized forward rate ( ) between time period and time period is:
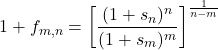
Or alternatively:
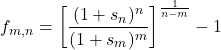
Forward Rate Calculation Example
Suppose the 1-year spot rate ( ) is 4.00% and the 2-year spot rate (
 ) is 5.00%. To find the 1-year forward rate one year from today (
 ):
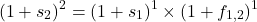
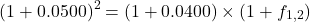
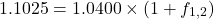
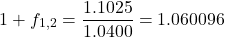

Calculating Spot Rates from Forward Rates
Conversely, spot rates can be reconstructed as the geometric mean of successive forward rates. For example, the 2-year spot rate () can be derived from the 1-year spot rate () and the 1-year forward rate starting in year 1 ():
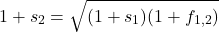
More generally, an -year spot rate is built from a sequence of single-period forward rates ( ):
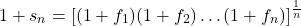
Calculating the Price of a Bond Using Forward Rates
Bonds can also be valued using forward rates by discounting each cash flow through its respective compounded forward path. For instance, the price of a 2-year coupon bond using forward rates utilizes the 1-year spot rate for the first cash flow and the product of the 1-year spot rate and the 1-year forward rate for the second cash flow. This approach guarantees identical pricing outcomes to spot-rate discounting because forward rates are mathematically synthesized from the spot curve.
Comparative Analysis of the Spot Curve, Par Curve, and Forward Curve
| Curve Type | Underlying Instrument / Metric | Primary Purpose | Sensitivity & Behavior |
| Spot Curve | Yields on zero-coupon bonds (e.g., Treasury STRIPS) | Theoretical benchmark for absolute valuation and discounting single cash flows. | Reflects pure time-value of money without coupon distortion. Serves as the master curve from which other curves are derived. |
| Par Curve | Yields on coupon bonds trading exactly at par value. | Market observation, pricing new debt issues at par, and baseline yield reporting. | Directly observable from market trading prices of benchmark government securities. |
| Forward Curve | Implied annualized interest rates for future lending/borrowing periods. | Assessing market expectations of future short-term rates, risk premia, and asset-liability management. | Exhibits the highest volatility and sensitivity to shifts in maturity structure. |
Geometric Relationships and Shape Dynamics
The relative positioning of the spot curve, par curve, and forward curve depends entirely on the prevailing slope of the term structure:
- Upward-Sloping (Normal) Yield Curve: When spot rates increase with maturity, coupon bonds carry blended yields, causing par rates to lie slightly below the spot curve. Because forward rates capture the marginal requirement for extending duration, the forward curve lies above both the spot and par curves. The ordering reads: Par Curve < Spot Curve < Forward Curve.
- Downward-Sloping (Inverted) Yield Curve: When spot rates decrease with maturity, the geometric mechanics reverse. Par rates lie above the spot curve, while the forward curve lies below both the spot and par curves. The ordering inverts to: Forward Curve < Spot Curve < Par Curve.
- Flat Yield Curve: When interest rates remain entirely constant across all maturities, the spot rate, par rate, and forward rate are identical at every maturity point.
Global Business Applications
Financial institutions and corporate treasuries worldwide utilize these yield curve dynamics to optimize financial management. For example, multinational enterprises such as Apple or JPMorgan Chase monitor the spread between spot and forward curves to time debt issuances across international capital markets. If forward curves signal rising short-term borrowing costs, corporate treasurers may accelerate fixed-rate debt offerings to lock in favorable long-term par yields. Conversely, institutional asset managers leverage forward curves to construct bullet or laddered bond portfolios that match future corporate liabilities, ensuring strict balance-sheet solvency across changing economic cycles.
