Swaps Forwards and Futures Strategies are essential frameworks utilized by institutional investors, corporate treasurers, and portfolio managers to navigate complex financial markets, optimize risk-adjusted returns, and protect multi-asset portfolios against adverse macroeconomic shocks.
As global capital markets experience heightened volatility across interest rates, foreign exchange rates, equity valuations, and commodity prices, mastering the application of derivatives has transitioned from a specialized trading tactic to a core competency of modern financial management.
This comprehensive guide explores how forward contracts, futures contracts, swaps, and volatility derivatives can be strategically deployed to restructure risk profiles, execute rapid asset allocation adjustments, and extract valuable forward-looking expectations embedded in market prices.
Introduction to Derivative-Driven Portfolio Optimization
Modern portfolio theory emphasizes the separation of asset allocation from security selection, yet traditional cash-market instruments often lack the liquidity, cost efficiency, and flexibility required to dynamically adjust risk exposures. Derivatives—financial instruments whose values depend on underlying assets, reference rates, or indices—offer a precision toolset for portfolio transformation. By utilizing derivatives, institutional funds can alter their duration, currency mix, equity beta, and volatility exposure without necessitating costly liquidations of underlying physical assets.
Corporations and financial institutions worldwide rely heavily on these instruments. For instance, global technology leader Microsoft actively manages its vast balance-sheet exposures and cash equivalents using sophisticated derivative overlays. Similarly, automotive multinational Toyota Motor Corporation employs comprehensive hedging programs involving forwards and swaps to neutralize currency volatility across global manufacturing hubs. Understanding the mechanics of these instruments allows decision-makers to engineer customized payout structures that align precisely with their institutional risk appetite and return objectives.
Modifying Risk and Return with Interest Rate Swaps Forwards and Futures
Interest rate risk is a primary driver of volatility for fixed-income portfolios, corporate balance sheets, and lending institutions. When macroeconomic conditions point toward shifting monetary policies, portfolio managers must proactively adjust their portfolio duration to either protect capital or capitalize on yield curve movements.
Interest Rate Swaps in Corporate Treasury Management
An interest rate swap is an agreement between two parties to exchange periodic interest rate cash flows based on a specific principal amount, known as the notional principal. Typically, this involves swapping a fixed interest rate for a floating interest rate, or vice versa.
For example, consider a corporate borrower holding a portfolio of floating-rate debt tied to Secured Overnight Financing Rate (SOFR) during an escalating interest rate cycle. To shield the organization from surging debt servicing costs, the treasury department can enter into a plain-vanilla interest rate swap where it pays a fixed rate (e.g., 4.50 percent) and receives a floating rate. Conversely, an institutional fixed-income portfolio manager holding long-term fixed-rate bonds who anticipates falling interest rates can enter a swap receiving fixed and paying floating, thereby transforming the portfolio’s fixed income stream into a synthetic floating-rate asset.
Futures and Forwards for Duration Adjustment
Treasury bond futures and forward rate agreements (FRAs) provide highly liquid mechanisms for altering portfolio duration over short-to-medium horizons. Duration measures a portfolio’s price sensitivity to interest rate changes. If a pension fund manager managing a portfolio valued at USD100,000,000 wishes to increase the portfolio’s duration from 5 years to 7 years due to an anticipated decline in benchmark interest rates, selling short-term instruments and buying long-term bonds incurs significant transaction costs and potential liquidity friction.
Instead, the manager can purchase Treasury bond futures contracts. By taking a long position in bond futures, the portfolio gains exposure to long-duration cash flows, effectively extending the aggregate duration of the portfolio. The required number of futures contracts is calculated using the basis point value (BPV) of the portfolio and the BPV of the futures contract:
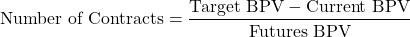
This mathematical precision allows managers to execute multi-million dollar risk reallocations instantaneously.
Currency Swaps Forwards and Futures for International Portfolios
Global diversification is a cornerstone of robust investment strategy, but exposure to foreign exchange (FX) fluctuations can introduce uncompensated volatility that swamps underlying asset returns. Currency derivatives—specifically forwards, futures, and currency swaps—provide the mechanics required to isolate foreign asset returns from currency risk or, conversely, to take active tactical bets on exchange rate movements.
Managing Foreign Exchange Risk
Forward contracts and foreign exchange futures lock in an exchange rate today for settlement at a specified future date. Global consumer goods giant Nestlé operates across hundreds of currency jurisdictions, making foreign exchange risk management paramount. By utilizing currency forwards, Nestlé locks in predictable cash flows for future cross-border transactions, effectively immunizing profit margins against sudden currency depreciations.
In portfolio management, a US-based global equity fund holding European equities denominated in EUR is exposed to EUR/USD exchange rate risk. If the portfolio manager believes the euro will weaken against the US dollar, hedging the currency exposure becomes vital. The manager can sell EUR forward against the USD, creating a synthetic hedged equity position.
Currency swaps go a step further by combining periodic interest rate exchanges in different currencies with an initial and final exchange of principal. These are frequently used by multinational corporations and international fixed-income funds to fund foreign operations or align asset cash flows with foreign liabilities, neutralizing currency risk over multi-year horizons.
Equity Swaps Forwards and Futures in Multi-Asset Portfolios
Equity derivatives allow investors to modify market beta, gain synthetic exposure to foreign stock indices, or rotate sector allocations without triggering capital gains taxes or incurring the administrative overhead of physical rebalancing.
Synthetic Exposure and Total Return Swaps
An equity swap is an agreement where one party exchanges the total return (dividends plus capital appreciation) of an equity index or single stock for a floating or fixed interest rate payment. Total return swaps (TRSs) are widely used by hedge funds and institutional asset managers to gain leveraged or unleveraged exposure to specific equity markets.
For instance, an institutional investor wanting exposure to the S&P 500 index without purchasing the underlying basket of 500 stocks can enter into a total return swap with a prime broker. The investor receives the total return of the S&P 500 and pays a floating rate such as SOFR plus a spread. This strategy minimizes custodial fees, optimizes capital efficiency, and permits exposure to restricted international markets where direct foreign ownership is legally constrained.
Equity index futures, such as E-mini S&P 500 futures, serve as the primary instrument for tactical asset allocation shifts. If a balanced multi-asset fund needs to rapidly reduce its equity weight from 60 percent to 40 percent due to impending geopolitical risks, selling equity index futures achieves this risk reduction instantly while the underlying physical stock portfolio remains undisturbed.
Harnessing Volatility Derivatives and Variance Swaps
Market volatility is a critical dimension of risk that traditional linear derivatives (forwards and futures) do not directly capture. Volatility derivatives, including Chicago Board Options Exchange (CBOE) Volatility Index (VIX) futures and options, alongside variance swaps, enable portfolio managers to trade and hedge market uncertainty directly.
Trading and Hedging Market Volatility
A variance swap is an over-the-counter derivative contract where two parties agree to exchange cash flows based on the difference between the realized variance of an underlying asset’s price returns and a strike variance agreed upon at inception. Unlike standard options, which are sensitive to both volatility and the underlying asset’s price level, a variance swap provides pure exposure to volatility.
Institutional portfolio managers deploy volatility derivatives primarily as tail-risk hedges. During stable market regimes, implied volatility tends to trade below realized or historical volatility, making volatility long positions relatively inexpensive insurance policies. When systemic shocks occur—such as sudden liquidity crunches or macroeconomic crises—implied volatility spikes exponentially. A portfolio hedged with VIX futures or variance swaps experiences a surge in derivative value that offsets drawdowns in core equity and credit holdings.
Targeted Equity and Interest Rate Risk Exposures
Achieving precise factor exposures requires combining swaps, forwards, and futures into cohesive multi-layered overlay strategies. Portfolio engineering often demands that interest rate risk and equity risk be decoupled and managed independently.
Immunization and Overlay Strategies
Consider a defined benefit pension fund with long-term liabilities that fluctuate with interest rates and asset values tied to global equities. To achieve liability-driven investing (LDI) targets, the fund implements an overlay strategy:
- Interest Rate Overlay: Utilizes interest rate swaps and long-duration Treasury futures to match the duration of the asset portfolio to the duration of the pension liabilities, insulating the surplus from interest rate volatility.
- Equity Overlay: Utilizes equity index futures to maintain a target equity beta of 0.80 relative to the global benchmark, ensuring the growth portfolio generates sufficient returns to meet actuarial targets.
This modular approach ensures that risk factors are isolated, measured, and controlled with mathematical rigor.
Asset Allocation Rebalancing and Inferring Market Expectations
Derivatives are indispensable tools for operational efficiency in asset allocation, tactical rebalancing, and extracting forward-looking market sentiment.
Tactical Asset Allocation and Market Signals
Rebalancing physical asset portfolios incurs substantial transaction costs, brokerage commissions, and tax consequences. By using liquid futures contracts, asset allocators can execute tactical shifts in seconds. For example, if an asset allocation model dictates increasing emerging market equity exposure by 5 percent, purchasing emerging market index futures achieves this exposure instantly while cash reserves earn risk-free rates in money market instruments—a strategy known as portable alpha.
Furthermore, prices in forward, futures, and swap markets serve as powerful indicators of market expectations. The slope of the interest rate swap curve or Eurodollar/SOFR futures pricing reveals market consensus regarding future central bank rate cuts or hikes. Similarly, currency forward points (the difference between spot and forward exchange rates) reflect interest rate differentials between two nations according to the uncovered interest rate parity theorem.
| Derivative Instrument | Primary Risk Managed | Typical Institutional Application | Cost & Liquidity Profile |
| Interest Rate Swaps | Interest Rate Risk / Duration | Corporate debt restructuring, LDI pension matching | High liquidity in major currencies, OTC flexibility |
| Currency Forwards | Foreign Exchange Risk | Hedging multinational revenues, international equity protection | Highly liquid, customized settlement dates |
| Equity Index Futures | Systematic Market Beta | Rapid portfolio rebalancing, tactical risk reduction | Standardized, exchange-traded, high liquidity |
| Variance Swaps | Market Volatility & Tail Risk | Downside protection, speculative volatility trading | Over-the-counter, customized notional amounts |
Conclusion and Strategic Implications
Swaps, forwards, and futures are powerful financial instruments that empower organizations and portfolio managers to engineer precise risk and return profiles.
By deploying interest rate swaps and bond futures, institutions seamlessly adjust duration and manage debt servicing costs.
Through currency forwards and swaps, multinational entities and international investors neutralize foreign exchange volatility.
Equity derivatives and variance swaps provide the flexibility required for synthetic exposure management and robust tail-risk mitigation.
Ultimately, integrating these derivative strategies into asset allocation and rebalancing frameworks enhances operational efficiency, reduces transaction friction, and equips decision-makers to navigate dynamic macroeconomic environments with confidence.
