The valuation of equity is one of the most fundamental tasks in corporate finance and investment management. While traditional valuation methods such as Dividend Discount Models (DDM) and Free Cash Flow (FCF) models focus on projected cash distributions or cash generation, they often fail to explicitly account for the cost of equity capital employed by the enterprise.
Residual income valuation addresses this shortfall by integrating modern corporate financial theory with accounting-based measures of performance.
This article provides an in-depth examination of the Residual Income Model (RIM), exploring its mechanics, underlying principles, relation to fundamental valuation metrics, implementation across single-stage and multistage contexts, accounting considerations, and comparative advantages over alternative valuation approaches.
1. Calculating and Interpreting Residual Income, Economic Value Added, and Market Value Added
Residual income represents the economic profit generated by a firm after charging for the total cost of capital used to generate those earnings. Under standard accounting frameworks, traditional net income reflects deductions for interest expenses (cost of debt), but omits the cost of equity capital. Residual income corrects this omission.
Residual Income (RI)
At its core, Residual Income ( ) for a given period
 is calculated as net income minus an equity charge:
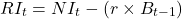
Where:
 = Net income in period
 = Required rate of return on equity (cost of equity)
 = Book value of equity at the beginning of period (end of period
 )
Alternatively, using Return on Equity (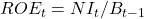 ):
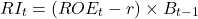
This formulation reveals that residual income is positive only when a firm earns a rate of return on its equity base that exceeds its required rate of return ( ).
Economic Value Added (EVA)
While residual income focuses purely on equity, Economic Value Added (EVA), pioneered by Stern Value Management (formerly Stern Stewart & Co.), measures total firm economic profit across both debt and equity providers:

Where:
 = Net Operating Profit After Taxes =
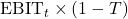
 = Weighted Average Cost of Capital
 = Total invested capital at the beginning of period
Alternatively:
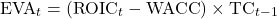
Where  is Return on Invested Capital (
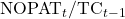 ).
To compute EVA accurately, financial analysts make adjustments to GAAP/IFRS financial statements (such as capitalizing research and development costs, adjusting for operating leases, and eliminating deferred tax liabilities) to reflect true economic capital and earnings.
Market Value Added (MVA)
Market Value Added (MVA) measures the cumulative total value created by a firm above the capital contributed by investors over its entire lifetime. It reflects the market’s expectation of current and future EVA generation:
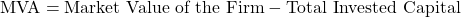
For equity specifically:
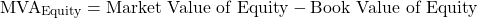
MVA is mathematically equivalent to the net present value (NPV) of all future expected EVA or Residual Income streams discounted at the appropriate cost of capital.
2. Uses of Residual Income Models
Residual income frameworks are applied across key domain areas in finance:
                          ┌─────────────────────────────────────┐
                          │     Residual Income Applications    │
                          └──────────────────┬──────────────────┘
                                             │
        ┌────────────────────────────────────┼────────────────────────────────────┐
        │                                    │                                    │
┌───────┴────────┐                   ┌───────┴────────┐                   ┌───────┴────────┐
│Equity Valuation│                   │ Performance    │                   │ Executive      │
│  & Analysis    │                   │ Measurement    │                   │ Compensation   │
└───────┬────────┘                   └───────┬────────┘                   └───────┬────────┘
        │                                    │                                    │
        • Intrinsic stock valuation          • Internal business unit evaluation  • Alignment of management
        • Identification of mispricing       • Economic profit tracking           │ incentives with shareholders
        • Companies paying no dividends      • Capital allocation decisions       • Capital efficiency focus
- Equity Valuation and Investment Analysis: Analysts utilize residual income models to establish intrinsic values for common stocks, identify mispriced equities, and value firms that do not pay dividends or generate negative free cash flows in early expansion phases.
- Corporate Performance Measurement: Internal management uses economic profit metrics (like EVA) to evaluate business unit performance, allocate capital efficiently toward value-accretive divisions, and eliminate value-destroying projects.
- Executive Compensation: Management incentives tied to EVA or residual income ensure executive alignment with shareholder returns, encouraging managers to optimize capital utilization rather than expanding accounting earnings via capital dilution.
3. Calculating Intrinsic Value using the Residual Income Model and Comparing Value Recognition
The Residual Income Valuation Formula
Under the Residual Income Model, the intrinsic value of a equity security ( ) equals current book value of equity plus the present value of all expected future residual income streams:
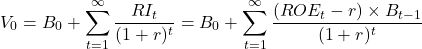
Where  is the current book value of equity.
Clean Surplus Relation
A key underlying assumption of the Residual Income Model is the Clean Surplus Relation. This condition requires that all changes in book value of equity between periods—excluding capital transactions with owners (e.g., share issuances, share repurchases, and dividends paid)—must pass through the income statement:
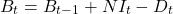
Where  represents dividends paid at time .
If items bypass net income and are recorded directly in Other Comprehensive Income (OCI)—such as foreign currency translation adjustments or unrealized gains/losses on available-for-sale securities—adjustments must be made to restore clean surplus accounting, or the model’s accuracy will be compromised.
Comparison of Value Recognition Across Present Value Models
All mathematically sound present value models—Dividend Discount Models (DDM), Free Cash Flow to Equity (FCFE) models, and Residual Income Models (RIM)—yield identical intrinsic value estimates when applied with consistent underlying assumptions.
However, the timing of value recognition varies across these models:
| Model | Primary Value Anchor | Timing of Value Recognition | Sensitivity to Terminal Value |
| Dividend Discount Model (DDM) | Present value of future dividends | Deferred until cash is distributed to shareholders | High (terminal value often represents 70%+ of total value) |
| Free Cash Flow to Equity (FCFE) | Present value of future cash flows | Deferred until cash generation occurs | High |
| Residual Income Model (RIM) | Current Book Value () + Present value of  | Front-loaded (Current book value represents a substantial portion of total intrinsic value) | Low (Terminal value plays a significantly reduced role) |
Because captures past recognized investments on the balance sheet immediately, RIM recognizes value significantly earlier in time than DDM or FCF models, making it far less sensitive to terminal value assumptions at distant forecast horizons.
4. Fundamental Determinants of Residual Income
To generate positive residual income, a firm must achieve a Return on Equity ( ) that exceeds its cost of equity capital (). The fundamental drivers of residual income can be decomposed using the DuPont Analysis framework:
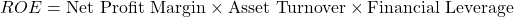
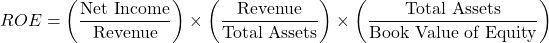
                                  ┌───────────────────────────┐
                                  │      Residual Income      │
                                  │     (ROE - r) × B_{t-1}   │
                                  └─────────────┬─────────────┘
                                                │
                       ┌────────────────────────┴────────────────────────┐
                       │                                                 │
          ┌────────────┴────────────┐                       ┌────────────┴────────────┐
          │ Return on Equity (ROE)  │                       │   Cost of Equity (r)    │
          └────────────┬────────────┘                       └─────────────────────────┘
                       │
     ┌─────────────────┼─────────────────┐
     │                 │                 │
┌────┴─────────┐ ┌─────┴────────┐ ┌──────┴─────────┐
│ Profit Margin│ │ AssetTurnover│ │ Leverage Ratio │
│ (Operating   │ │ (Capital     │ │ (Financial     │
│ Efficiency)  │ │ Efficiency)  │ │ Structure)     │
└──────────────┘ └──────────────┘ └────────────────┘
Strategic Determinants of Value Creation:
- Competitive Advantage & Economic Moats: Sustainable excess returns (
 ) require barriers to entry, pricing power, unique operational scale, or network effects.
- Capital Allocation Efficiency: Management’s capacity to reinvest retained earnings into projects that yield returns above .
- Cost of Equity (): Influenced by market risk factors, corporate debt levels, interest rates, and macroeconomic volatility.
5. Relation Between Residual Income Valuation and Justified Price-to-Book Ratio
The Residual Income Model provides the direct theoretical bridge linking a stock’s Price-to-Book ( ) ratio to its operational drivers.
Under a constant growth residual income framework, if residual income grows at a constant long-term rate  :
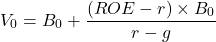
Dividing both sides by current book value ():
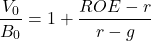
This relationship demonstrates that:
- If , the justified ratio is greater than 1.0 (the stock commands a market premium over book value).
- If
 , the justified ratio equals 1.0 (residual income is zero; firm value equals book value).
- If
 , the justified ratio is less than 1.0 (the firm destroys shareholder value; stock trades at a discount to book value).
6. Single-Stage and Multistage Residual Income Models
Single-Stage (Constant-Growth) Model
The single-stage RIM assumes that book value grows at a constant rate , and the spread between and remains constant indefinitely:
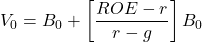
Where 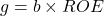 , and
 is the earnings retention ratio (
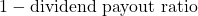 ).
Practical Calculation Example:
Consider a company with:
- Current Book Value per Share () = USD 25.00
- Forecasted Return on Equity () = 14%
- Required Return on Equity () = 10%
- Retention Rate () = 60%
- Growth rate () =
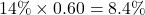
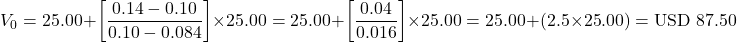
Multistage Model
In competitive markets, extraordinary returns ( ) tend to fade over time due to market competition. A multistage model forecasts explicit residual income over a discrete period
 , followed by a terminal value assumption for continuing residual income.
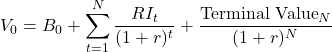
7. Implied Growth Rate in Residual Income
When the current market price equals intrinsic value ( ), the market price-to-book ratio implies a specific long-term residual income growth rate (). Rearranging the single-stage justified equation yields:
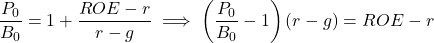
Solving explicitly for :
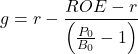
Interpretation
- If market is high relative to current , the market is pricing in accelerated future growth in the residual income base or expanding returns on capital.
- If market is low relative to operational , the market anticipates decaying competitive advantages or falling earnings efficiency.
8. Continuing Residual Income and Forecast Horizon Dynamics
At the forecast horizon , analysts must select an appropriate assumption regarding Continuing Residual Income. Five common persistence assumptions are utilized:
| Persistence Assumption | Description | Terminal Value Formula at Horizon N |
| 1. Indefinite Persistence | Residual income continues indefinitely at level  or grows at rate . |  |
| 2. Immediate Decay to Zero | Residual income drops to zero immediately at horizon ( drops to ). |  |
| 3. Linear Decay to Zero | Competition gradually erodes excess returns over  years following horizon . |  (where  is the persistence factor,  ) |
| 4. Convergence to Industry Average | slowly fades to match the long-term historical industry return. | Present value of declining stream toward average |
| 5. Value Premium Decay | ratio converges to 1.0 over time due to technological obsolescence or market forces. | 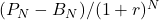 |
Justifying Persistence Factors ()
The choice of persistence factor (where  ) must reflect the strategic dynamics of the firm and industry:
- High Persistence (
 ): High entry barriers, strong brand loyalty, patents/proprietary technology, high switching costs (e.g., enterprise software, pharmaceuticals).
- Low Persistence (
 ): Low barriers to entry, highly cyclical or commoditized sectors, rapid technological disruption (e.g., retail, hardware manufacturing).
9. Comparing Residual Income Models to DDM and Free Cash Flow Models
The decision to choose a valuation model depends on company-specific factors and data availability.
                                  ┌───────────────────────────────────┐
                                  │      Valuation Model Selection    │
                                  └─────────────────┬─────────────────┘
                                                    │
        ┌───────────────────────────────────────────┼───────────────────────────────────────────┐
        │                                           │                                           │
┌───────┴────────┐                         ┌────────┴────────┐                         ┌───────┴────────┐
│      DDM       │                         │      FCFE       │                         │      RIM       │
└───────┬────────┘                         └────────┬────────┘                         └───────┬────────┘
        │                                           │                                           │
  Best used when:                             Best used when:                             Best used when:
  • Steady dividend policy                   • Leverage is stable                        • Non-dividend paying firms
  • Mature, stable earnings                  • Cash flows track profitability            • Negative free cash flows
  • Minority investment perspective          • Controlling perspective                   • High terminal value uncertainty
Standard Model Comparison Matrix
| Feature / Attribute | Dividend Discount Model (DDM) | Free Cash Flow to Equity (FCFE) | Residual Income Model (RIM) |
| Primary Driver | Cash distributions to shareholders | Cash generated after cap-ex & debt servicing | Economic profit ( ) on balance sheet capital |
| Applicability to Non-Dividend Stocks | Poor (requires dividend assumptions) | Strong | Strong |
| Sensitivity to Terminal Value | Very High | High | Low |
| Suitability for Financial Firms | Moderate | Poor (cash flow hard to define for banks) | Excellent |
| Accounting Dependency | Low (cash-focused) | Low (cash-focused) | High (requires clean balance sheets) |
10. Strengths and Weaknesses of Residual Income Models
Strengths
- Focus on Economic Value Creation: Explicitly charges for the cost of equity capital, ensuring value is recognized only when returns exceed investor hurdles.
- Reduced Dependence on Terminal Value: Because the anchor value () is derived directly from current audited balance sheets, a major portion of total intrinsic value is established immediately at
 .
- Applicability to Non-Dividend or Distressed Firms: Can evaluate unprofitable firms or zero-dividend growth stocks as long as future balance sheet paths and earnings can be modeled.
- Strong Alignment with Financial Institutions: Highly effective for banks and insurance providers where standard cash flows are difficult to isolate, but book values and regulatory capital are tracked closely.
Weaknesses
- High Dependence on Accounting Data: Vulnerable to accounting distortions, conservative or aggressive reporting practices, and management earnings manipulation.
- Violation of Clean Surplus Relation: Items reported in Other Comprehensive Income (OCI) can distort book value metrics if adjustments are omitted.
- Requirement for Capital Adjustments: Historical book value may not reflect modern economic reality if large off-balance-sheet assets (such as internally generated intellectual property) are omitted.
11. Accounting Issues in Applying Residual Income Models
Because the Residual Income Model relies directly on financial statements, analysts must evaluate accounting practices and adjust historical numbers when necessary.
Key Accounting Adjustments
1. Non-recurring Items and Earnings Quality
Temporary gains/losses (e.g., asset sales, restructuring charges, impairment losses) should be eliminated from base net income forecasts to prevent distorting ongoing return on equity expectations.
2. Clean Surplus Violations
Analysts must audit statement of comprehensive income entries. Items historically bypassing net income—such as foreign currency translations, derivative adjustments, and post-retirement benefit adjustments—must be integrated back into earnings forecasts or book value bases.
3. Off-Balance-Sheet Assets and Liabilities
- Operating Leases: Must be capitalized on the balance sheet (standardized under IFRS 16 / ASC 842).
- Research & Development (R&D): Standard accounting rules expense R&D immediately. To reflect economic reality, analysts should capitalize historical R&D costs as intangible capital assets and amortize them over their useful economic life, increasing both earnings and .
4. Accounting Conservatism
Conservative accounting choices (e.g., accelerated depreciation, immediate expensing of intangibles, aggressive inventory write-downs) artificially lower current book value (). While this reduces initial , it artificially inflates future , leaving total calculated intrinsic value () mathematically invariant—provided the clean surplus relation is preserved.
Real-World Corporate Example: Valuing Enterprise Financials
To observe how the Residual Income Model is implemented in practice, consider the valuation of JPMorgan Chase & Co. (NYSE: JPM) using corporate financial metrics:
Inputs & Financial Data
- Current Book Value per Share (): USD 105.00
- Required Rate of Return on Equity (): 9.0%
- Forecast Period: 3 years explicit explicit projection, followed by linear decay of excess returns.
Explicit Period Projections
| Year (t) | Beginning Book Value (Bt−1) | Projected ROEt | Forecasted NIt | Equity Charge (r×Bt−1) | Residual Income (RIt) | Discount Factor (1.09t) | PV of RIt |
| 1 | USD 105.00 | 16.0% | USD 16.80 | USD 9.45 | USD 7.35 | 1.0900 | USD 6.74 |
| 2 | USD 115.08 | 15.0% | USD 17.26 | USD 10.36 | USD 6.90 | 1.1881 | USD 5.81 |
| 3 | USD 125.44 | 14.0% | USD 17.56 | USD 11.29 | USD 6.27 | 1.2950 | USD 4.84 |
Note: Assumes a constant 40% dividend payout ratio ( ).
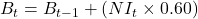 .
Summation of Value Components
- Current Book Value (): USD 105.00
- PV of Explicit Residual Income (Years 1–3):
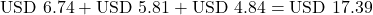
- Continuing Value Calculation (Assuming Persistence Factor
 ):
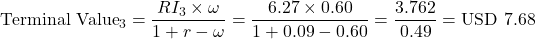
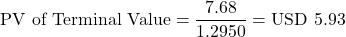
Final Intrinsic Value Determination
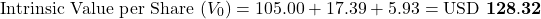
In this implementation, the current balance sheet book value () accounts for 81.8% of total intrinsic value (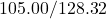 ), demonstrating the model’s stability and resistance to terminal value forecast errors relative to cash flow or dividend-based models.
