Relative valuation models are among the most widely utilized tools in financial analysis, investment management, and corporate finance. They allow analysts to determine the value of a target company or its equity by comparing its valuation multiples to those of peer companies or historical benchmarks.
This comprehensive analysis covers the dual methodological frameworks of relative valuation, the calculation and interpretation of price versus enterprise value multiples, peer group selection strategies, and the structural application of past, current, and projected future metrics.
The Process for Using Multiples: Method of Comparables vs. Method of Forecasted Fundamentals
Valuation multiples can be applied through two distinct methodologies: the method of comparables and the method of forecasted fundamentals.
1. The Method of Comparables
- Economic Rationale: The foundational economic rationale is the Law of One Price, which dictates that two identical assets or securities should sell at comparable prices.
- Process:
- Identify a set of comparable peer companies operating in the same industry or displaying similar fundamental characteristics (growth, risk, and cash flow return profile).
- Calculate specific valuation multiples (e.g., Price-to-Earnings, EV/EBITDA) for each peer.
- Determine a representative summary statistic across the peer group, such as the arithmetic mean, median, or harmonic mean.
- Multiply this peer group benchmark by the subject company’s corresponding fundamental variable (e.g., earnings, sales, or EBITDA) to compute an estimated value.
- Key Challenge: Differences in accounting methods, leverage, size, and growth profiles across peers require subjective adjustments or benchmarking normalization.
2. The Method of Forecasted Fundamentals
- Economic Rationale: This approach links a valuation multiple directly to the company’s underlying financial forecasts via discounted cash flow (DCF) models. A justified price multiple is derived mathematically rather than observed from market prices.
- Process:
- Formulate valuation formulas based on fundamental valuation models (such as the Gordon Growth Model or multi-stage dividend discount models). For example, the justified Price-to-Earnings (
 ) ratio from the Gordon Growth Model is expressed as:
where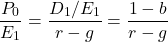
 is the dividend payout ratio,
 is the required rate of return on equity,
 is the retention ratio, and
 is the sustainable growth rate.
- Input the company’s expected growth rate, risk profile (required return), and payout policy into the theoretical formula.
- Calculate the “justified” multiple and compare it to the current market multiple to determine if the asset is overvalued, undervalued, or fairly valued.
- Formulate valuation formulas based on fundamental valuation models (such as the Gordon Growth Model or multi-stage dividend discount models). For example, the justified Price-to-Earnings (
Calculation, Interpretation, and Appropriate Uses of Multiples
Valuation multiples are broadly split into two categories: Equity Multiples (reflecting value to common shareholders) and Enterprise Value Multiples (reflecting total firm value available to all capital providers).
1. Price Multiples (Equity Multiples)
| Multiple | Formula | Interpretation & Appropriate Uses |
| Price-to-Earnings () | 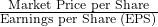 | Measures how much investors are willing to pay for every dollar of corporate earnings. Best used for stable, profitable firms across most industries, but less useful for firms with negative earnings. |
Price-to-Book Value ( ) | 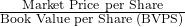 | Compares market value to accounting net asset value. Highly valuable for financial institutions, banks, and asset-heavy or liquidation-scenario firms where book values closely approximate fair market values. |
Price-to-Sales ( ) | 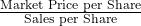 | Evaluates valuation relative to top-line revenue generation. Excellent for cyclical firms at cyclical troughs, startups, or early-stage technology companies that have not yet achieved positive net income. |
Price-to-Cash Flow ( ) | 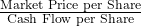 | Relies on cash flow rather than accounting earnings, mitigating distortions from non-cash depreciation and earnings management. Useful across general corporate valuations. |
2. Enterprise Value (EV) Multiples
Enterprise value represents the total economic claim on a firm:
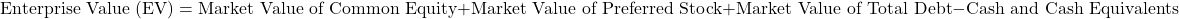
| Multiple | Formula | Interpretation & Appropriate Uses |
| EV / EBITDA | 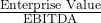 | Capital-structure neutral metric that assesses operating cash generation before interest, taxes, depreciation, and amortization. Widely used for capital-intensive industries (e.g., telecommunications, manufacturing, utilities) and cross-border comparisons with varying leverage ratios. |
| EV / Sales | 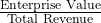 | Measures total firm value relative to sales. Ideal for comparing companies with differing capital structures within capital-light, high-growth sectors like biotechnology and software-as-a-service (SaaS). |
| EV / EBIT | 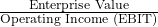 | Focuses on operating profitability while accounting for operating asset consumption through depreciation and amortization. Useful for capital-intensive firms where D&A is a genuine economic cost. |
Determining a Potential Peer Group
Selecting an appropriate peer group is the cornerstone of reliable multiples-based valuation. A peer group should consist of companies with underlying business models, cash flow patterns, growth trajectories, and risk profiles similar to the target firm.
1. Industry Classification Systems
Analysts typically begin by leveraging standardized industry classification frameworks to screen initial pools of candidate companies:
- Global Industry Classification Standard (GICS)
- Industry Classification Benchmark (ICB)
While these taxonomies provide a strong structural starting point, standard industry groupings can often be overly broad. For instance, two companies classified within the same broad technology sector may have vastly different business models (e.g., a hardware manufacturer versus a subscription cloud service provider), rendering direct multiple comparisons misleading.
2. Specific Drivers of Expected Return and Fundamental Characteristics
To refine the peer group beyond broad industry labels, analysts must filter candidates based on fundamental economic drivers:
- Expected Growth Rates: Companies exhibiting rapid organic growth command higher valuation multiples than stagnant firms. Peers should share similar consensus growth projections.
- Risk Profiles (Operating and Financial Leverage): Businesses with high operating leverage or volatile cash flows warrant lower valuation multiples. Financial leverage (debt-to-equity mix) heavily impacts equity multiples like , making Enterprise Value multiples necessary when peer leverage varies significantly.
- Profitability and Return on Invested Capital (ROIC): Firms generating superior margins and high returns on capital justify multiple expansions relative to lower-margin competitors.
- Competitive Environment and Geographic Reach: Companies operating in identical macroeconomic regulatory regions facing similar competitive pressures make superior comparables.
Use of Past, Current, and Projected Future Values in Estimating Multiples
When calculating multiples, analysts must choose the time horizon for the denominator (fundamental metric). Each approach offers distinct advantages and analytical trade-offs.
1. Trailing (Past) Multiples
- Definition: Computed using historical financial data from the most recent completed fiscal year or trailing twelve months (TTM) (e.g., Trailing using last year’s EPS).
- Advantages: Based on hard, audited historical data that requires no subjective forecasting assumptions.
- Disadvantages: Backward-looking; historical earnings or cash flows may not represent ongoing operational realities, particularly if the firm has recently restructured, experienced a structural shift, or is cyclical.
2. Current Multiples
- Definition: Computed using current market price combined with annualized current run-rate metrics or most recent quarterly data.
- Advantages: Readily available and reflects up-to-date market pricing.
- Disadvantages: Can be heavily distorted by temporary transitory items, seasonal variations, or extraordinary non-recurring gains/losses embedded in current operational results.
3. Leading / Forward (Projected Future) Multiples
- Definition: Calculated using current market price divided by forecasted operational metrics for future periods (e.g., Forward using consensus analyst estimates for next year’s earnings,
 ).
- Advantages: Highly relevant for valuation because equity value represents the present value of future cash flows. Forward multiples explicitly incorporate anticipated growth and structural business changes.
- Disadvantages: Dependent on analyst consensus forecasts, which can be prone to estimation errors, excessive optimism, or analyst bias.
Comparative Business Application
To visualize how relative valuation is synthesized across diverse global enterprises, consider the following structural comparison:
| Company / Entity | Primary Sector | Dominant Multiple | Analytical Rationale |
| Apple Inc. | Technology Hardware | Forward & EV/EBITDA | Mature technology leader with stable cash flows and predictable earnings expansion. |
| Amazon.com, Inc. | E-Commerce & Cloud | EV/Sales & EV/EBITDA | Captures rapid top-line scaling and capital-intensive fulfillment infrastructure expansion. |
| JPMorgan Chase & Co. | Financial Services | Price-to-Book () | Reflects net asset valuation where underlying financial asset values are marked closely to market value. |
Conclusion
Relative value equity valuation bridges market prices and fundamental performance.
Whether deploying the method of comparables via the Law of One Price or deriving theoretical values through forecasted fundamentals, an analyst must judiciously choose between equity and enterprise value multiples, build robust peer groups driven by fundamental characteristics rather than generic ticker classifications, and properly balance trailing historical data against forward-looking projections.
