A forward contract is a customized, over-the-counter (OTC) agreement between two parties to buy or sell an underlying asset at a specified future date for a price agreed upon today. Understanding the distinction between the price of a forward contract and its value is fundamental to derivative pricing:
- Forward Price (
 ): The fixed price set at initiation at which the underlying asset will be exchanged at maturity date
 . By convention, the forward price is chosen such that the contract has zero value to both parties at inception.
- Forward Value (
 ): The monetary worth of the contract to one of the parties at a specific point in time
 (
 ). While the value is zero at initiation, it changes continuously over the life of the contract as the spot price of the underlying asset fluctuates and time to maturity decreases.
Part 1: Determination of Forward Value and Price Across the Contract Lifecycle
The lifecycle of a forward contract spans three distinct phases: initiation ( ), during the life of the contract (
 ), and at expiration (
 ).
1. At Initiation ()
At contract initiation, no money changes hands between the long (buyer) and short (seller) positions. The forward price is calculated using the no-arbitrage principle and the cost-of-carry model.
No-Arbitrage Principle
The forward price must be set such that no risk-free arbitrage profit can be realized by simultaneously buying/selling the underlying asset in the spot market and entering into an opposing forward position.
Cost-of-Carry Model
For an asset with spot price  , continuous risk-free rate
 , storage/holding costs with present value
 , and monetary income/yield with present value
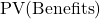 :
- Continuous Compounding Form:
If benefits and costs are expressed as continuous yields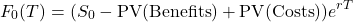
 (convenience yield/income) and
 (storage cost yield):
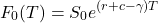
- Discrete Compounding Form:
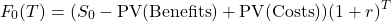
Initial Value
Because the forward price is set to balance the current spot price adjusted for carrying costs:

2. During the Life of the Contract ()
As time moves from to , the spot price changes to  , and the remaining time to maturity becomes
 . The original forward price remains fixed, but the value of the long contract fluctuates.
Determining Value
The value of a long forward contract at time is the difference between the current spot price (adjusted for remaining carry costs/benefits) and the present value of the fixed forward price :
- Continuous Compounding:
Alternatively, using the new forward price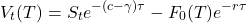
 prevailing in the market at time :
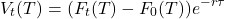
- Discrete Compounding:
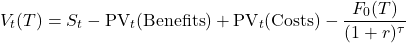
Value to the Short Position
The contract is a zero-sum game between the long and short positions:
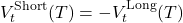
3. At Expiration ()
At maturity, time to expiration becomes zero ( ), and the present value discount factor becomes
 or
 .
Price and Value
- Forward Price:
 (the forward price converges to the final spot price).
- Value to Long Position:
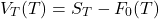
- Value to Short Position:
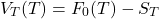
Lifecycle Summary
| Lifecycle Stage | Time (t) | Forward Price (F) | Value to Long Position (V) |
| Initiation | | 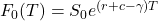 |  |
| During Life | | remains fixed | 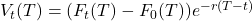 |
| Expiration | | | 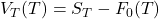 |
Part 2: Determination and Uses of Interest Rate Forward Rates
Interest rate forward contracts (including Forward Rate Agreements, or FRAs) allow market participants to lock in a borrow or lend rate today for a specified period starting at a future date.
1. Determination of Interest Rate Forward Rates
Forward interest rates are derived from current spot interest rates using the Implied Forward Rate formula, which rests on the principle that two alternative investment paths over the same total horizon must yield the same return under no-arbitrage conditions.
Mathematical Derivation
Consider two options for investing money over time period  :
- Path A: Invest for period at the spot rate
 .
- Path B: Invest for period
 at the spot rate
 , then roll over the proceeds into a forward rate
 covering the period between and .
Under annual compounding:
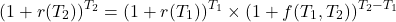
Solving for the implied forward rate :
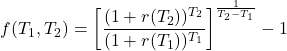
Under continuous compounding:
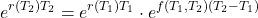
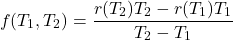
Forward Rate Notation Example ( FRA)
An “A  B FRA” (e.g.,
 FRA) indicates:
 months: The contract starts in 3 months (the loan period begins at month 3).
 months: The contract expires 9 months from today.
- Underlying Loan Duration:
 months.
2. Key Uses of Forward Rates
| Primary Use | Mechanism & Action | Target Audience | Key Objective |
| Hedging Borrowing Costs | Long position in an FRA locks in a maximum borrowing rate for future debt issuance. | Corporate treasurers, borrowers | Protection against rising interest rates |
| Hedging Lending Yields | Short position in an FRA locks in a minimum return rate on future cash inflows. | Institutional investors, lenders | Protection against declining interest rates |
| Rate Speculation | Taking directional positions based on whether future spot rates will differ from current implied forward rates. | Traders, hedge funds | Profit from anticipated rate shifts |
| Yield Curve Analysis | Extracting market expectations of future monetary policy, inflation, and growth from the forward rate curve shape. | Economists, central banks, analysts | Economic forecasting and term structure modeling |
| Derivative Pricing & Valuation | Using implied forward rates as building blocks to value interest rate swaps, caplets, and floorlets. | Quantitative analysts, financial engineers | Benchmark valuation of multi-period contracts |
A. Hedging Interest Rate Risk
- Borrowers: A corporation planning to issue debt in 6 months can buy an FRA (long position) to lock in a maximum borrowing rate, protecting against rising interest rates.
- Lenders/Investors: A financial institution expecting cash inflows to invest in 3 months can sell an FRA (short position) to lock in a lending rate, protecting against declining interest rates.
B. Speculation on Rate Movements
- Traders take long positions in forward contracts if they anticipate actual future spot rates will rise above the implied forward rate.
- Conversely, traders take short positions if they expect future spot rates to fall below the implied forward rate.
C. Yield Curve Construction and Interpretation
- Forward rates reflect market expectations regarding future monetary policy, inflation, and economic growth.
- The shape of the forward rate curve relative to the spot yield curve provides insights into term premium trends and potential yield curve shifts (e.g., steepening vs. flattening).
D. Pricing and Valuing Complex Derivatives
- Interest Rate Swaps: An interest rate swap can be viewed as a series (portfolio) of forward rate contracts. The swap rate is calculated directly from the sequence of implied forward rates.
- Caplets and Floorlets: Interest rate options (caps and floors) use implied forward rates as the primary underlying variable in pricing models such as Black’s model.
