Portfolio Performance Evaluation serves as the vital analytical framework through which institutional asset owners, portfolio managers, and fiduciaries evaluate whether investment returns meet established mandates, determine the underlying drivers of excess return, and verify whether outperformance stems from repeatable manager skill rather than uncompensated risk exposure.
In an institutional environment managing trillions of dollars globally, conducting a systematic portfolio performance evaluation enables organizations to align portfolio outcomes with long-term liabilities, risk budgets, and corporate governance standards.
Framework of Portfolio Performance Evaluation
Portfolio performance evaluation comprises three sequential, interdependent components: performance measurement, performance attribution, and performance appraisal. Understanding their individual functions and combined interplay is essential for institutional oversight.
+-----------------------------------------------------------------------+
|                   PORTFOLIO PERFORMANCE EVALUATION                    |
+-----------------------------------------------------------------------+
                                    |
                                    v
+-----------------------------------------------------------------------+
|                         PERFORMANCE MEASUREMENT                       |
|  - What was the portfolio's return over the period?                   |
|  - Calculates rates of return (TWRR vs. MWRR).                        |
+-----------------------------------------------------------------------+
                                    |
                                    v
+-----------------------------------------------------------------------+
|                         PERFORMANCE ATTRIBUTION                       |
|  - Why did the portfolio produce these specific returns?              |
|  - Deconstructs excess return into allocation, selection, etc.        |
+-----------------------------------------------------------------------+
                                    |
                                    v
+-----------------------------------------------------------------------+
|                         PERFORMANCE APPRAISAL                         |
|  - Was the outperformance driven by skill or risk/luck?               |
|  - Evaluates risk-adjusted metrics (Sortino, Appraisal Ratio, etc.).  |
+-----------------------------------------------------------------------+
The Three Pillars: Measurement, Attribution, and Appraisal
- Performance Measurement: The quantitative baseline that calculates the rate of return achieved by an investment portfolio over a specified timeframe. It addresses the fundamental question: What was the portfolio’s financial return? This phase calculates time-weighted returns (TWRR) to isolate manager performance from external capital flows, or money-weighted returns (MWRR) to capture internal rate of return dynamics when cash flows are under manager control.
- Performance Attribution: The analytical breakdown of return outcomes relative to a designated benchmark. It addresses the question: Why did the portfolio perform the way it did? Attribution decomposes excess returns into specific investment decisions, such as strategic asset allocation, sector weighting, security selection, and currency hedging.
- Performance Appraisal: The qualitative and quantitative evaluation of risk-adjusted outcomes. It addresses the critical question: Was the outperformance generated through superior investment skill, or was it the result of excess risk taking and market luck? Appraisal combines attribution data with risk-adjusted performance metrics to assess the consistency and sustainability of manager alpha.
Interrelationships Among Components
These three components form a continuous feedback loop. Measurement supplies the raw return data. Attribution ingests these returns alongside benchmark structure to isolate decision drivers. Appraisal takes the attributed excess returns, adjusts them for risk exposure, and determines manager skill. Without accurate measurement, attribution is flawed; without attribution, appraisal lacks contextual granularity; and without appraisal, measurement offers no insight into risk management. Institutional managers such as BlackRock utilize this triad to provide institutional clients with absolute clarity regarding portfolio results.
Attributes of an Effective Attribution Process
To provide actionable intelligence for asset owners and investment committees, an institutional performance attribution system must satisfy six core structural criteria:
- Reflective of the Investment Process: The attribution methodology must directly mirror how the portfolio manager actually makes decisions. If a manager utilizes a bottom-up stock selection process, the attribution model must emphasize security selection rather than forcing a top-down sector allocation structure.
- Completeness (Full Reconciliation): The attribution model must account for 100% of the portfolio’s return and excess return. Unexplained residual items, pricing mismatches, or unallocated cash flows undermine executive confidence in the analysis.
- Period Aggregatable: The attribution system must seamlessly link single-period attribution results across multi-period horizons (e.g., quarterly, annual, multi-year) using mathematically sound linking algorithms (such as the Carino or Menchero compounding algorithms) without introducing distortions.
- Symmetry and Transparency: The process must evaluate negative outcomes as objectively as positive outcomes. Calculations, formulas, and pricing sources must be clear, transparent, and reproducible across investment teams.
- Timeliness and Frequency: Attribution analyses must be generated with sufficient speed and frequency to allow portfolio managers and risk officers to identify unintended factor bets before they disrupt portfolio mandates.
- Reliable Data Baseline: The system must utilize synchronized portfolio and benchmark pricing, corporate action data, and FX rates to eliminate artificial pricing noise.
Dimensions of Attribution: Return vs. Risk and Macro vs. Micro
Performance attribution operates across multiple analytical dimensions depending on whether the primary focus is return generation or risk exposure, and whether decisions are evaluated at the fund sponsor or individual manager level.
Return Attribution vs. Risk Attribution
- Return Attribution: Deconstructs the realized total return or excess return of a portfolio into discrete active decision components (such as sector allocation or security selection). It measures where returns came from.
- Risk Attribution: Deconstructs the overall risk profile of the portfolio—measured as absolute volatility, Value at Risk (VaR), or active risk (tracking error variance)—into contributing sources. It measures where risk was taken and identifies whether return-generating segments consumed an appropriate share of the risk budget.
Macro vs. Micro Return Attribution
- Macro Return Attribution: Conducted at the asset owner or plan sponsor level (e.g., pension funds, endowments, sovereign wealth funds). It evaluates decisions made across multiple asset classes and multiple external managers. Macro attribution isolates the impact of fund-level policy asset allocation, tactical asset allocation shifts, benchmark selection, and manager selection. Sovereign institutions like Norges Bank Investment Management use macro attribution to evaluate how overall strategic allocation drives returns for fund portfolios valued at over USD1.5 trillion.
- Micro Return Attribution: Conducted at the individual portfolio manager level within a specific asset class mandate. It evaluates intra-portfolio choices against a specialized benchmark, dissecting active returns into sector weights, security selection, style factors, and execution effects.
Attribution Methodologies: Returns-Based, Holdings-Based, and Transactions-Based
Institutional performance attribution uses three distinct technical approaches, each offering a unique balance between data requirements, calculation complexity, and precision.
| Attribution Approach | Description | Primary Advantages | Primary Disadvantages | Best Institutional Application |
| Returns-Based (RBA) | Regresses historical portfolio returns against a set of factor indices or style benchmarks using statistical techniques (Sharpe’s style analysis). | Requires minimal underlying data (only total fund return series); low implementation cost; independent of portfolio holdings reporting. | Low timeliness; subject to statistical lag; cannot capture rapid tactical shifts within evaluation periods; vulnerable to multi-collinearity. | Fund-of-funds analysis, hedge fund manager screening, historical macro style verification. |
| Holdings-Based (HBA) | Evaluates portfolio holdings snapshot at beginning of each period (e.g., daily or monthly) and projects expected returns based on benchmark components. | High transparency; clear visibility into active factor bets and positions; eliminates need for trade execution timestamping. | Ignores intra-period trading activity; subject to “window dressing” distortion; creates phantom return residual if trading volume is high. | Low-turnover equity strategies, quarterly institutional reporting, fundamental long-only funds. |
| Transactions-Based (TBA) | Combines initial holdings snapshots with daily transaction logs, precise timestamps, execution prices, and trading costs. | Highest mathematical accuracy; accounts for intra-period trades and actual cash flows; captures transaction cost impact fully. | Highest computational complexity; extensive data integration requirements; high operational implementation cost. | High-turnover strategies, active quantitative funds, multi-asset absolute return mandates. |
Interpreting Sources of Portfolio Return: The Brinson Attribution Framework
The standard model for equity return attribution is the Brinson framework, developed by Brinson, Hood, and Beebower (BHB) and refined by Brinson and Fachler (BF). The Brinson-Fachler model evaluates active returns by comparing sector performance against overall benchmark performance.
For any given segment 


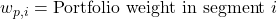

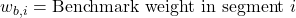

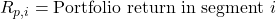

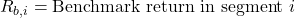

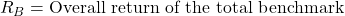
Brinson-Fachler Formulas
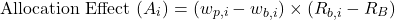

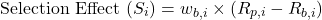

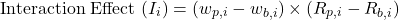

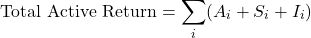

Numerical Institutional Attribution Example
Consider an institutional equity portfolio valued at USD500 million benchmarked against the S&P 500 Index. The overall benchmark return for the quarter is 

- Portfolio Weight (


- Benchmark Weight (


- Portfolio Sector Return (


- Benchmark Sector Return (


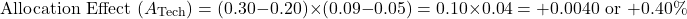

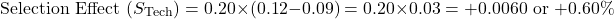

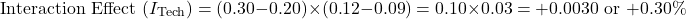

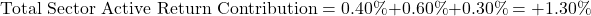

Interpretation: Overweighting the Technology sector contributed 


Fixed-Income Performance Attribution
Equity attribution frameworks cannot be directly applied to fixed-income portfolios due to the non-linear relationship between interest rates and bond prices, maturity decay, option embeddedness, and yield curve structural shifts. Institutional fixed-income attribution decomposes returns relative to specific yield curve and credit variables.
+-----------------------------------------------------------------------+
|                   FIXED-INCOME ATTRIBUTION COMPONENTS                 |
+-----------------------------------------------------------------------+
  |-- Income Return (Pass-through coupon yield & accrual)
  |-- Interest Rate Management (Duration & yield curve shift effects)
  |-- Yield Curve Structure (Slope / twist & curvature / butterfly shifts)
  |-- Sector & Credit Allocation (Option-adjusted spread / OAS changes)
  |-- Security Selection (Individual bond issue mispricing)
  `-- Currency / Derivative Overlay (FX fluctuations & swap hedges)
Core Components of Fixed-Income Attribution
- Income Return (Carry/Coupon): The base return derived from coupon accrual and amortization of discount or premium, assuming unchanged yield curves.
- Yield Curve Shift (Level Effect): The impact of parallel movements in the benchmark yield curve on portfolio price, driven by duration positioning (
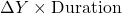
- Yield Curve Slope/Shape (Twist & Curvature): Performance impact resulting from non-parallel yield curve changes (steepening, flattening, or butterfly twists), evaluated via Key Rate Durations (KRD).
- Sector & Credit Spread Effect: Excess return generated by shifts in credit spreads across sectors (e.g., Investment Grade vs. High Yield) and individual spread dynamics, measured using Option-Adjusted Spread (OAS).
- Security Selection Effect: Return attributable to selecting individual issue bonds within a specific credit tier or sector relative to benchmark securities.
- Foreign Exchange / Derivative Overlay: The impact of currency fluctuations and hedging instruments (interest rate swaps, futures) on foreign currency bond holdings. Institutional bond managers like PIMCO utilize fixed-income attribution models to verify whether active returns stem from macro interest rate calls or micro credit analysis.

Selecting a Risk Attribution Approach
Selecting an appropriate risk attribution methodology requires balancing investment strategy structure, risk mandates, and reporting objectives. Fiduciaries must consider three core factors:
- Absolute Risk vs. Relative Risk: Absolute return strategies (e.g., global macro hedge funds) require risk attribution based on total volatility, Value at Risk (VaR), or Expected Shortfall. Benchmark-relative strategies (e.g., core index-plus funds) require relative risk attribution based on Tracking Error Variance (TEV) decomposition.
- Parametric vs. Factor-Based Models: Fundamental portfolios benefit from fundamental multi-factor risk attribution models (such as MSCI Barra), which decompose risk into macroeconomic factors, style factors (Value, Growth, Momentum, Size), and industry exposures. Highly concentrated portfolios require position-level marginal contribution to risk (MCR) attribution.
- Linearity of Asset Risk Profiles: Portfolios holding complex derivatives, mortgage-backed securities (MBS), or options require non-linear risk attribution methodologies (such as Monte Carlo simulation-based VaR decomposition) to capture gamma, vega, and tail-risk exposures accurately.
Asset Owner vs. Investment Manager Performance Attribution
Distinguishing outcomes created by the asset owner (sponsor) from those generated by external investment managers is a cornerstone of institutional governance.
Sponsor Decisions vs. Manager Decisions
- Asset Owner (Sponsor) Level: The sponsor establishes Strategic Asset Allocation (SAA), selects asset class benchmarks, implements Tactical Asset Allocation (TAA) tilts across major asset classes, sets currency hedging policies, and decides manager allocation weights. The return impact of these decisions is measured via macro attribution.
- Investment Manager Level: The hired external manager operates within a defined mandate (e.g., U.S. Large Cap Value Equity). The manager controls sector weights, stock selection, trading execution, and intra-portfolio cash holdings. Their performance is measured via micro attribution relative to the assigned mandate benchmark.
If a pension fund sponsor retains an overweight position in global real estate during a property downturn, the resulting loss represents sponsor-level asset allocation performance. If the underlying real estate manager outperforms the property benchmark during that period via property selection, the manager has demonstrated positive micro performance despite the sponsor’s negative allocation outcome.
Benchmarking Architecture: Liability-Based vs. Asset-Based
Selecting an appropriate benchmark is critical for meaningful performance measurement, attribution, and appraisal. Institutional benchmarks fall into two broad structural classes: liability-based and asset-based benchmarks.
Liability-Based Benchmarks
Liability-Based Benchmarks (LBB) are custom cash flow profiles or interest-rate sensitive targets designed to mirror specific future obligation structures.
- Primary Institutional Applications: Defined benefit pension plans, life insurance liability pools, nuclear decommissioning trusts, and structured wealth preservation accounts practicing Liability-Driven Investing (LDI).
- Strategic Objective: The primary goal is asset-liability matching rather than maximizing raw asset return. The benchmark tracks the present value changes of future liabilities using discount curves (such as corporate bond yield curves). Performance success is judged by surplus growth (Asset Growth


Asset-Based Benchmarks
Asset-Based Benchmarks represent tradable market indices or asset groupings used to evaluate investment portfolios focused on capital appreciation or income generation.
| Asset-Based Benchmark Type | Description | Key Strengths | Key Weaknesses |
| Absolute Return | Fixed target rate of return (e.g.,   | Simple to understand; aligns directly with target absolute wealth goals. | Ignores market opportunities and systematic regime changes; uninvestable. |
| Broad Market Index | Comprehensive market coverage index (e.g., MSCI World Index, Bloomberg U.S. Aggregate Bond Index). | Highly investable, transparent, objective, widely recognized by stakeholders. | May not reflect specific mandate constraints or specialized style tilts. |
| Broad Market Style Index | Segmented market index reflecting investment style/capitalization (e.g., Russell 2000 Value Index). | Aligns directly with specific manager mandate and investment universe. | Subject to index reconstitutions and style migration over time. |
| Factor-Based Benchmark | Benchmark constructed around explicit risk factors (e.g., Fama-French Quality, Low Volatility). | Directly isolates systemic factor exposure from true security selection alpha. | Complex to construct; requires specialized attribution risk engines. |
| Custom Asset Owner | Weighted combination of underlying indices reflecting strategic asset allocation (SAA). | Perfect fit for total institutional fund structure; tracks board-approved policy. | Requires disciplined rebalancing rules; complex performance tracking. |
| Manager Universe / Peer Group | Median performance of a peer group of managers operating in the same category (e.g., Morningstar Large Cap Peer Group). | Reflects real-world institutional manager competition and cash drag. | Subject to survivor bias, self-reporting bias, and non-investability. |


Tests of Benchmark Quality and the SAMURAI Criteria
To maintain analytical validity in portfolio performance evaluation, institutional benchmarks must satisfy the formal SAMURAI quality framework:
- Specified in Advance: The benchmark is explicitly defined prior to the evaluation period so the manager operates with full operational clarity.
- Appropriate: The benchmark aligns directly with the manager’s investment philosophy, style constraints, and asset mandate.
- Measurable: The benchmark return can be calculated reliably and frequently on a quantitative basis.
- Unambiguous: The identity and weights of benchmark constituent securities are clearly defined and publicly accessible.
- Reflective of Current Investment Opinions: The manager has deep knowledge of the benchmark components and can form active opinions on them.
- Accountable: The manager accepts responsibility for tracking differences relative to the benchmark.
- Investable: The benchmark consists of accessible, liquid assets that can be passively held as an alternative to active management (e.g., through low-cost index products offered by managers like Vanguard or State Street Global Advisors).
Impact of Benchmark Misspecification
Using an improper benchmark (e.g., benchmarking an active high-yield credit fund against a broad investment-grade treasury index) corrupts all three evaluation phases:
- Mislabeled Alpha (False Outperformance): The manager may appear to generate high excess return when they are simply taking uncompensated systemic risk factor bets (e.g., credit risk or illiquidity premiums).
- Invalid Risk Attribution: Risk attribution models will attribute tracking error variance to active manager skill rather than structural benchmark mismatch.
- Misaligned Fiduciary Incentives: Asset owners risk paying high active management fees for passive factor exposure, while managers may be improperly penalized or rewarded due to systemic benchmark drift.
Benchmarking Alternative Investments
Applying traditional performance evaluation techniques to alternative asset classes—such as Private Equity, Real Estate, Infrastructure, and Hedge Funds—presents severe operational and analytical challenges. Managers like Bridgewater Associates operate absolute-return hedge fund strategies that require specialized evaluation frameworks.
+-----------------------------------------------------------------------+
|              ALTERNATIVE INVESTMENT BENCHMARKING CHALLENGES           |
+-----------------------------------------------------------------------+
  |-- Valuation Smoothing / Lagged Pricing (Stale appraisal data)
  |-- Non-Normal Return Distributions (Extreme asymmetry, fat tails)
  |-- Survivorship & Selection Biases (Self-reported database noise)
  |-- Illiquidity Premium Contamination (Confounding risk with alpha)
  `-- Cash Flow Timing Sensitivity (IRR distortion vs. TWRR standards)
Key Benchmark Distortions in Alternatives
- Valuation Lags and Appraisal Smoothing: Private market assets rely on quarterly or annual appraisals rather than continuous market pricing. This introduces artificial serial autocorrelation, dampens measured volatility, and understates beta and tracking error.
- Cash Flow Timing Disconnects: Private equity investments use Internal Rate of Return (IRR) or Direct Alpha measures because managers dictate capital calls and distributions. Standard public market time-weighted returns (TWRR) fail when capital amounts fluctuate heavily.
- Non-Normal Distributions: Hedge funds and private market debt often exhibit high negative skewness and heavy kurtosis due to short-option profiles or default risk. Standard variance-based evaluation metrics understate tail risk.
- Peer Database Biases: Hedge fund and private equity peer group databases suffer from survivorship bias (failing funds drop out of historical records) and self-reporting bias (managers report data only when performance is favorable), inflating median peer returns by
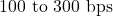

Quantitative Risk-Adjusted Appraisal Metrics
Performance appraisal quantifies whether excess returns compensate for the specific risks taken. Institutional analysis relies on five core metrics.
Sortino Ratio
The Sortino Ratio modifies the traditional Sharpe Ratio by substituting total standard deviation with downside risk (downside deviation), penalizing only returns that fall below a specified target return (
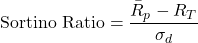

Where downside deviation (

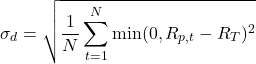

- Interpretation: A higher Sortino ratio indicates superior return generation per unit of bad volatility. It is ideal for asymmetric strategies, options portfolios, and private wealth accounts focused on capital preservation.
Appraisal Ratio
The Appraisal Ratio measures alpha generated per unit of unsystematic (specific) risk. Derived from the Single-Index Model, it isolates security selection efficiency.
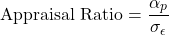

Where 


- Interpretation: The Appraisal Ratio measures a manager’s stock-picking ability independent of market exposure. An Appraisal Ratio above


Upside and Downside Capture Ratios
Capture ratios evaluate how a portfolio participates in market rallies versus market sell-offs.
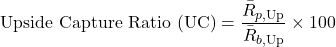

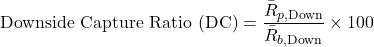

- Capture Asymmetry Ratio:


Maximum Drawdown and Drawdown Duration
- Maximum Drawdown (MDD): The maximum peak-to-trough percentage decline observed in portfolio value over a specified time window.
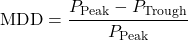

- Drawdown Duration: The total time elapsed from the initial peak to the recovery of that peak (Recovery Window = Trough to Break-Even).
Portfolio Value
  ^
  |      Peak
--|------/\------------------------------------ Base Line
  |     /  \                          /
  |    /    \    Drawdown            /   Recovery
  |   /      \    Phase             /     Phase
  |  /        \                    /
--|------------\------------------/------------
  |             \    Trough      /
  |              \______/_______/
  +---------------------------------------------> Time
  |<------------------------------------------>|
                 Total Drawdown Duration
Summary of Appraisal Metrics
| Appraisal Metric | Key Formula Focus | Target Benchmark / Denominator | Core Institutional Usage |
| Sortino Ratio | Excess return over target. | Downside Deviation ( | Asymmetric return strategies, tail-risk protection mandates. |
| Appraisal Ratio | Jensen’s Alpha ( | Unsystematic Risk ( | Fundamental equity stock-pickers, active alpha engines. |
| Upside Capture | Up-market return ratio. | Up-period Benchmark Return. | Evaluating growth participating capability. |
| Downside Capture | Down-market return ratio. | Down-period Benchmark Return. | Capital preservation analysis. |
| Maximum Drawdown | Peak-to-trough loss percentage. | Peak Portfolio Valuation. | Stress testing, risk tolerance limits, liquidity management. |
Limitations of Appraisal Measures and Risk Metrics
While quantitative appraisal metrics provide structured insights, institutional asset owners must be aware of their inherent analytical limitations:
- Assumption of Return Normality: Metrics such as the Sharpe Ratio and Appraisal Ratio assume returns are normally distributed (Gaussian). Non-linear strategies, credit portfolios, and derivative overlays violate this assumption, understating actual risk.
- Benchmark Dependency: Metrics reliant on market regressions (such as Jensen’s Alpha and the Appraisal Ratio) are sensitive to benchmark selection. Benchmark misspecification distorts calculated alpha and residual risk.
- Vulnerability to Metric Manipulation: Managers can artificially inflate risk-adjusted ratios over short horizons through specific trading practices—such as selling out-of-the-money index put options (which generates steady premiums but creates rare catastrophic tail risk).
- Time Horizon Sensitivity: Appraisal metrics calculated over short time horizons (e.g., less than 36 months) are dominated by market noise rather than manager skill, leading to high estimation variance.
Institutional Framework for Evaluating Investment Manager Skill
Separating repeatable investment skill from random fortune is the ultimate objective of institutional portfolio performance evaluation. Fiduciaries must implement a multi-step analytical review combining quantitative statistics with qualitative operational due diligence.
+-----------------------------------------------------------------------+
|                 MANAGER SKILL EVALUATION ARCHITECTURE                 |
+-----------------------------------------------------------------------+
  |-- Statistical Hypothesis Testing (t-stats on alpha > 2.0)
  |-- Multi-Period Attribution Consistency (Batting average & hit rate)
  |-- Style Drift & Active Share Analysis (Verifying true active management)
  |-- Return Distribution Resilience (Downside protection & low drawdown)
  `-- Qualitative Operational Verification (Team stability & risk controls)
Quantitative Verification Steps
- Statistical Significance of Alpha (


- Batting Average and Hit Rate Analysis: Evaluate consistency across market cycles. Batting average measures the percentage of periods in which the manager outperforms the benchmark, while hit rate measures the percentage of active security bets that generate positive excess return. Skillful managers exhibit structural consistency rather than reliance on a single speculative bet.
- Active Share and Tracking Error Alignment: Cross-evaluate Active Share alongside Tracking Error. High Active Share combined with low tracking error indicates inefficient factor exposure, whereas high Active Share paired with proportional tracking error indicates genuine high-conviction security selection.
- Return Persistence across Market Regimes: Conduct factor regression and style drift analysis across multiple market regimes (e.g., rising interest rate environments, high inflation, liquidity shocks). Skillful managers demonstrate thesis resilience across changing macroeconomic regimes.
Qualitative Operational Verification
Quantitative outperformance must be corroborated by qualitative evaluation:
- Investment Process Consistency: Verify that current portfolio holdings directly reflect the manager’s stated philosophy and risk guidelines.
- Organization and Team Stability: Assess key-person risk, compensation incentives, firm ownership structures, and turnover within the investment research team.
- Risk Governance Culture: Ensure independent risk management teams hold explicit veto power over position concentration limits and liquidity terms.
Conclusion
Institutional portfolio performance evaluation provides asset owners, fiduciaries, and investment managers with the tools required to measure outcomes accurately, attribute performance drivers cleanly, and appraise manager skill objectively. By establishing rigorous attribution systems, implementing high-quality SAMURAI benchmarks, evaluating downside risk metrics, and combining quantitative hypothesis testing with qualitative governance, institutions ensure that portfolio strategies remain aligned with long-term financial liabilities and fiduciary mandates.

