The Mortgage-Backed Security (MBS) Instrument and Market Features represent a fundamental pillar of modern global fixed-income markets, transforming illiquid individual residential and commercial real estate loans into standardized, highly liquid investment vehicles.
Securitization allows primary mortgage lenders to transfer credit and interest rate risk to secondary market investors, unlocking trillions of dollars in liquidity to fund housing and commercial property infrastructure worldwide.
Understanding the structural dynamics, prepayment mechanics, credit enhancement frameworks, and cash flow waterfalls of mortgage-backed instruments is essential for portfolio managers, corporate treasurers, and institutional investors seeking to optimize yield while navigating cash flow uncertainty.
Prepayment Risk and Time Tranching Structures in Securitization
A defining characteristic of fixed-income instruments backed by residential mortgage loans is cash flow uncertainty resulting from borrower prepayment behavior. Unlike traditional corporate or sovereign bonds that pay periodic interest and return principal at maturity, mortgage assets embed an implicit embedded call option held by the homebuyer.
Defining Prepayment Risk: Contraction versus Extension Risk
Prepayment risk refers to the uncertainty surrounding the timing of principal cash flows returned to investors from the underlying mortgage pool. Borrowers possess the legal right to pay off all or part of their outstanding mortgage principal prior to scheduled maturity through refinancing, home sales, or default liquidations. Prepayment risk bifurcates into two opposing market exposures:
- Contraction Risk: Occurs when prevailing market interest rates decline significantly below the contractual mortgage coupon. Homeowners refinance their debt at lower rates, causing prepayment speeds to accelerate. As principal is returned to security holders much faster than anticipated, the effective maturity and duration of the mortgage instrument shorten (contract). Investors receive lump-sum principal repayments exactly when market yields are lowest, forcing them to reinvest capital into lower-yielding assets—a phenomenon known as reinvestment risk.
- Extension Risk: Manifests when market interest rates rise substantially above the mortgage coupon. Homeowners retain their existing low-rate mortgages, drastically slowing prepayment speeds. Consequently, principal cash flows decline, and the effective maturity and duration of the mortgage instrument lengthen (extend). Investors remain trapped in below-market yield securities for longer periods precisely when higher yields are available elsewhere in the financial system.
To measure prepayment velocity across mortgage portfolios, market participants utilize standard metrics such as the Single Monthly Mortality (SMM) rate and the annualized Conditional Prepayment Rate (CPR). The relationship between monthly prepayment probability and annual CPR is expressed as:
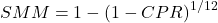
Securitization structures benchmark prepayment assumptions against the Public Securities Association (PSA) prepayment model, where 100 PSA assumes a prepayment rate of 0.2% CPR in month one, increasing by 0.2% CPR each month until reaching a constant 6.0% CPR at month 30.
Time Tranching Mechanisms and Structures
To mitigate the pervasive impact of prepayment risk on institutional portfolios, financial engineers design time tranching structures. Time tranching reorganizes the principal repayment cash flows generated by an underlying mortgage pool into distinct classes (tranches) with prioritized payment order, creating securities tailored to specific investor duration requirements.
+-------------------------------------------------------------------------+
|                    UNDERLYING MORTGAGE PASS-THROUGH POOL                |
+-------------------------------------------------------------------------+
                                     |
                                     v
+-------------------------------------------------------------------------+
|                  COLLATERALIZED MORTGAGE OBLIGATION (CMO)               |
+-------------------------------------------------------------------------+
       |                             |                             |
       v                             v                             v
+--------------+              +--------------+              +--------------+
|   Tranche A  |              |   Tranche B  |              |   Tranche C  |
| (Short Pay)  |              | (Intermediate|              |  (Long Pay)  |
| Receives     | -----------> | Receives     | -----------> | Receives     |
| Principal 1st|              | Principal 2nd|              | Principal 3rd|
+--------------+              +--------------+              +--------------+
- Sequential-Pay Tranches: The most straightforward time tranching structure divides the security into sequential classes (e.g., Tranche A, Tranche B, Tranche C). All scheduled interest is distributed to all tranches concurrently, but all principal repayments (both scheduled amortization and prepayments) are directed exclusively to Tranche A until its principal balance is fully retired. Once Tranche A is retired, principal cash flows sequentially flow to Tranche B, and finally to Tranche C. This structure insulates longer-duration tranches from contraction risk and shorter-duration tranches from extension risk.
- Planned Amortization Class (PAC) Tranches: Engineered to offer precise cash flow predictability, PAC tranches guarantee a fixed principal payment schedule, provided the underlying pool prepayment speed remains within a pre-specified range known as the PAC collar (e.g., 100 PSA to 300 PSA).
- Support or Companion Tranches: PAC cash flow predictability is made possible by support tranches. Companion tranches act as shock absorbers: if prepayments accelerate above the upper collar, excess principal is absorbed by the companion class; if prepayments decelerate below the lower collar, principal payments to companion classes are deferred to satisfy the PAC schedule. Consequently, companion tranches exhibit extreme contraction and extension risk.
- Targeted Amortization Class (TAC) Tranches: Similar to PAC tranches, TAC securities protect against contraction risk at a single specific prepayment speed (e.g., 150 PSA), but do not provide dual-sided protection against extension risk if prepayment rates slow down.
- Accrual Tranches (Z-Tranches): Receive no explicit cash flow (neither interest nor principal) during the initial phases of the securitization structure. Instead, accrued interest is added to the tranche’s principal balance, while the cash that would have been paid as interest is redirected to accelerate the payoff of earlier sequential tranches.
Strategic Purpose of Time Tranching for Institutional Investors
Time tranching does not eliminate the aggregate prepayment risk inherent in the underlying collateral; rather, it redistributes cash flow variability across different investor classes based on their liability profiles. Pension funds and life insurance companies seeking long-duration assets to match long-term liabilities invest in later sequential or PAC tranches. Conversely, commercial banks and money market managers requiring short-duration liquidity allocate capital to short sequential tranches. Global asset managers like BlackRock actively trade these tranches to match precise yield curve expectations and risk parameters.
Fundamental Features of Securitized Residential Mortgage Loans
The structural integrity and cash flow dynamics of residential mortgage-backed securities depend directly on the contractual characteristics of the underlying individual home loans. A residential mortgage loan is a legal contract securing a loan against a primary residential property asset.
Loan Maturity and Interest Rate Mechanics
Residential mortgage contracts establish explicit terms governing principal repayment horizons and interest rate adjustments:
- Contractual Maturity: Standard residential loans typically feature maturities of 15, 20, or 30 years. Shorter-maturity loans (15-year) feature higher monthly principal amortization and lower default rates, whereas 30-year mortgages dominate consumer demand due to lower monthly debt payments.
- Fixed-Rate Mortgages (FRMs): The interest rate remains static across the entire loan term. The borrower’s monthly payment remains constant, but the composition of the payment shifts progressively from interest-heavy in early years to principal-heavy near maturity.
- Adjustable-Rate Mortgages (ARMs): The interest rate resets periodically based on a benchmark financial index (such as the Secured Overnight Financing Rate, SOFR) plus a fixed margin. ARMs transfer interest rate risk from the lender to the borrower.
- Hybrid ARMs: Feature an initial fixed-rate period (e.g., 3, 5, 7, or 10 years) followed by annual adjustable interest rate resets (e.g., a 5/1 Hybrid ARM).
- Interest-Only (IO) Mortgages: Require the borrower to pay only interest for a specified initial period (e.g., 5 or 10 years), after which the loan converts into a fully amortizing structure over the remaining term, resulting in a substantial payment step-up.
Amortization Profiles and Prepayment Terms
Amortization dictates how principal is liquidated over the life of the loan. A fully amortizing mortgage is structured so that scheduled monthly payments satisfy both interest accrual and total principal repayment by maturity. Partially amortizing loans feature lower monthly payments but require a lump-sum balloon payment at maturity.
In the United States primary market, standard conforming mortgage contracts grant borrowers the unconditional right to prepay outstanding principal at any time without penalty. In contrast, international residential mortgage markets (such as those in Europe or Canada) frequently enforce explicit prepayment penalty clauses or yield maintenance fees if borrowers refinance prior to contractual reset dates.
Lender Rights, Recourse Provisions, and Underwriting Metrics
The credit risk of securitized mortgage pools depends on legal remedies and borrower qualification criteria:
- Recourse versus Non-Recourse Loans: Under recourse mortgage contracts, if a defaulting borrower’s foreclosed property fails to cover the outstanding balance, the lender retains legal rights to seize the borrower’s other personal assets and wages. Under non-recourse loans, the lender’s recovery is strictly limited to liquidating the underlying physical real estate collateral. Most U.S. residential mortgages function effectively as non-recourse loans due to state-level anti-deficiency statutes.
- Loan-to-Value (LTV) Ratio: Measures loan leverage relative to collateral value:
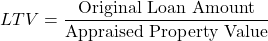
Higher LTV ratios correlate strongly with elevated default probability. Mortgages with LTV ratios exceeding 80% typically require Private Mortgage Insurance (PMI) to protect lenders against credit losses.
- Debt-to-Income (DTI) Ratio: Evaluates borrower debt-servicing capacity by calculating total monthly debt obligations as a percentage of gross monthly income.
- Credit Scores (FICO): Categorize borrower creditworthiness into prime (typically FICO > 660) and subprime tiers, establishing baseline default expectations for securitization models.
Types, Characteristics, Cash Flows, and Risks of Residential Mortgage-Backed Securities (RMBS)
Residential Mortgage-Backed Securities are broadly categorized based on the credit quality of the underlying mortgages and the nature of the entity guaranteeing the securities.
                               +-----------------------------------+
                               | RESIDENTIAL MORTGAGE-BACKED (RMBS)|
                               +-----------------------------------+
                                                 |
                       +-------------------------+-------------------------+
                       |                                                   |
                       v                                                   v
         +---------------------------+                       +---------------------------+
         |        AGENCY RMBS        |                       |      NON-AGENCY RMBS      |
         +---------------------------+                       +---------------------------+
                       |                                                   |
           +-----------+-----------+                                       v
           |                       |                         +---------------------------+
           v                       v                         |   Senior / Subordinated   |
    +--------------+       +--------------+                  |    Credit Enhancement     |
    |  Ginnie Mae  |       | Fannie Mae / |                  |    Structures & Tranches  |
    | (Explicit US |       | Freddie Mac  |                  +---------------------------+
    |  Government  |       |   (GSEs)     |
    |  Guarantee)  |       +--------------+
    +--------------+
Agency versus Non-Agency RMBS Frameworks
The global RMBS ecosystem is divided into Agency and Non-Agency market segments:
- Agency RMBS: Issued or guaranteed by U.S. government agencies or government-sponsored enterprises (GSEs).
- Ginnie Mae (Government National Mortgage Association): A government corporation within the U.S. Department of Housing and Urban Development (HUD). Ginnie Mae securities carry the explicit full faith and credit guarantee of the U.S. government, eliminating credit default risk for investors.
- Fannie Mae (Federal National Mortgage Association) and Freddie Mac (Federal Home Loan Mortgage Corporation): GSEs operating under federal conservatorship. They guarantee the timely payment of principal and interest on conforming mortgages meeting strict underwriting criteria (LTV, loan size limits). While GSE securities carry an implicit federal backing rather than an explicit guarantee, they are treated as virtually risk-free from a default standpoint.
- Non-Agency RMBS: Issued by private financial institutions, such as commercial banks and investment firms including Wells Fargo and JPMorgan Chase. These structures securitize prime non-conforming loans (jumbo loans exceeding GSE size limits), subprime loans, or non-qualified mortgages (Non-QM). Because Non-Agency RMBS lack government guarantees, issuers incorporate internal credit enhancements—such as senior-subordinated structures, overcollateralization, and excess spread—to absorb credit defaults.
Mortgage Pass-Through Securities: Structure and Cash Flows
The foundational RMBS instrument is the mortgage pass-through security. A trustee holds a undivided pool of residential mortgages, and payments made by underlying borrowers are passed through directly to investors on a pro-rata basis, minus servicing fees paid to loan servicers and guarantee fees paid to GSEs.
 Underlying Mortgage Pool (Monthly Borrower Payments: Principal + Interest)
                                     |
                                     v
                       Servicing & Guarantee Fees
                                     |
                                     v
 Investor Pass-Through Cash Flows (Pro-Rata Distributable Interest & Principal)
Key pool metrics governing pass-through cash flows include:
- Weighted Average Coupon (WAC): The weighted average interest rate of the underlying mortgages in the pool, where weights correspond to each loan’s outstanding principal balance.
- Weighted Average Maturity (WAM): The weighted average remaining term of the underlying loans, expressed in months.
Investors in pass-through securities receive monthly cash flows consisting of scheduled interest, scheduled principal amortization, and unscheduled principal prepayments. Because cash flows are distributed pro-rata across all pool certificates, pass-through investors bear unmitigated exposure to prepayment risk (both contraction and extension risk).
Collateralized Mortgage Obligations (CMOs): Advanced Tranching and Waterfall Cash Flows
To overcome the single-risk structure of pass-throughs, market originators pool mortgage pass-through securities to construct Collateralized Mortgage Obligations (CMOs). CMOs redistribute the cash flow streams of the underlying collateral across specialized tranches with varying maturities, yields, and risk profiles.
Beyond time-tranched sequential and PAC structures, CMO innovations include Stripped Mortgage-Backed Securities:
- Interest-Only (IO) Strips: Receive all interest cash flows generated by the underlying pool and zero principal payments. IO strips carry a nominal principal balance. As prepayment rates accelerate, the underlying principal balance decays rapidly, causing future interest payments to vanish. Consequently, IO values drop sharply when interest rates fall, creating a negative duration profile.
- Principal-Only (PO) Strips: Receive all principal repayments and zero interest payments. PO securities are purchased at a deep discount to par value (e.g., USD60 per USD100 face value). When prepayments accelerate, principal is returned faster, accelerating realization of the discount and dramatically increasing investor yield.
Comparing RMBS Structures, Cash Flows, and Risk Profiles
| Security Type | Issuer / Guarantor | Primary Cash Flow Mechanism | Prepayment Risk Profile | Default / Credit Risk | Primary Target Investor |
| Agency Pass-Through | Ginnie Mae, Fannie Mae, Freddie Mac | Pro-rata monthly principal and interest minus fees. | Full, direct exposure to contraction and extension risk. | Minimal to zero default risk (government/GSE backing). | Mortgage REITs (e.g., Annaly Capital Management), Central Banks, Bond Funds. |
| CMO Sequential Tranche | GSEs or Private SPVs | Waterfall payment; principal concentrated on active short tranche. | Contraction risk mitigated for later tranches; extension risk reduced for early tranches. | Zero (Agency) to Structural (Non-Agency). | Commercial Banks, Short-Term Money Managers. |
| CMO PAC Tranche | GSEs or Private SPVs | Scheduled fixed principal repayment supported by companion tranches. | Highly protected against both contraction and extension risk within collar. | Minimal to zero default risk (Agency collateral). | Pension Funds, Life Insurance Companies. |
| Non-Agency Senior RMBS | Commercial & Investment Banks | Senior-subordinated waterfall; subordinated tranches absorb losses first. | Direct prepayment exposure combined with default sensitivity. | Protected by credit subordination, excess spread, and overcollateralization. | Hedge Funds, Institutional Credit Asset Managers. |
Commercial Mortgage-Backed Securities (CMBS): Characteristics and Credit Structures
Commercial Mortgage-Backed Securities (CMBS) are backed by mortgage loans secured by commercial, income-generating real estate assets. While RMBS rely on individual residential wage earners, CMBS cash flows depend on the operating revenues produced by commercial property tenants.
Underlying Commercial Collateral and Property Economics
CMBS underlying collateral comprises diversified commercial real estate sectors:
- Multi-Family Residential: Apartment complexes.
- Office Property: High-rise central business district or suburban office buildings.
- Retail Real Estate: Regional shopping malls, anchored strip centers.
- Industrial & Logistics: Warehouses, distribution facilities.
- Hospitality: Hotels, resorts, and lodging properties.
Underwriting commercial mortgages requires analyzing property-level net operating income (NOI), tenant lease structures, vacancy rates, and market cap rates. Major global real estate asset managers, such as Blackstone, originate and structure commercial real estate debt portfolios designed for secondary CMBS distribution.
Primary metrics utilized by CMBS analysts include:
- Debt Service Coverage Ratio (DSCR): Evaluates a property’s cash flow margin available to cover debt obligations:
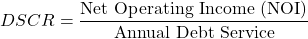
A DSCR greater than 1.0 indicates that the property generates sufficient operational income to satisfy annual interest and principal payments. CMBS underwriting standards typically target DSCRs of 1.25 to 1.50.
- Debt Yield Ratio: Calculates NOI as a percentage of total loan balance, evaluating lender protection independent of interest rate levels:
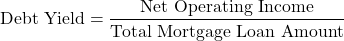
Call Protection Mechanisms in Commercial Mortgages
Unlike residential mortgages, commercial real estate loans feature contractual call protections that restrict borrower prepayments, mitigating contraction risk for CMBS investors:
- Lockout Periods: Contractual clauses prohibiting prepayments entirely for an initial period (e.g., the first 2 to 5 years of a 10-year loan term).
- Defeasance: A legal structure where a borrower wishing to prepay a loan replaces the real estate collateral with a customized portfolio of U.S. Treasury securities. The Treasury cash flows match all remaining scheduled interest and principal payments of the original mortgage. Defeasance removes real estate credit risk while eliminating prepayment uncertainty.
- Yield Maintenance Charges: A financial penalty requiring the borrower to pay a premium equal to the present value of the interest income the lender would lose by reinvesting the prepaid principal at lower current market rates.
- Prepayment Penalty Points: Enforces fixed percentage penalties on prepaid principal (e.g., 5% in year one, 4% in year two, step-down scale).
CMBS Tranches, Credit Enhancement, and Balloon Refinancing Risk
CMBS transactions feature senior-subordinated credit tranching structures designed to allocate credit default risk:
+-------------------------------------------------------------------------+
|                      COMMERCIAL MORTGAGE POOL                           |
+-------------------------------------------------------------------------+
                                     |
                                     v
+-------------------------------------------------------------------------+
|                           CASH FLOW WATERFALL                           |
+-------------------------------------------------------------------------+
       |                             |                             |
       v                             v                             v
+--------------+              +--------------+              +--------------+
| AAA Tranche  |              |  BBB Tranche |              |   B-Piece    |
| (First Cash  | ------------>| (Mezzanine   | ------------>| (Subordinated|
| Flow Priority|              | Credit Risk  |              | First Loss   |
| Lowest Yield)|              | Yield Boost) |              | Highest Yield|
+--------------+              +--------------+              +--------------+
                                                                    ^
                                                                    |
                                                      First Dollar Losses Absorbed
- Senior Tranches (AAA/AA): Receive priority payment of interest and principal. They are protected against default losses by subordinated tranches.
- Mezzanine Tranches (A/BBB): Absorb losses once lower-tier equity and subtranches are wiped out.
- First-Loss B-Piece (Unrated/BB): The lowest tranche in the CMBS waterfall. B-Piece investors absorb the first dollar of default losses across the commercial pool. In exchange for taking high credit risk, B-Piece buyers receive high yields and retain special servicing rights.
- Role of Special Servicer: If a commercial loan enters default or experiences severe stress, control of the loan transfers from the Master Servicer to a designated Special Servicer. The Special Servicer executes loan workouts, debt restructurings, or property foreclosures to maximize recovery value.
- Balloon Risk (Refinancing Risk): Most commercial mortgages are structured as 10-year interest-only or partially amortizing loans that require a large balloon payment at maturity. If property values drop, credit markets tighten, or interest rates spike at loan maturity, the borrower may be unable to secure refinancing or sell the property, defaulting on the balloon payment. Balloon risk represents the primary credit driver in mature CMBS portfolios.
Structural Differences: RMBS versus CMBS Comparison
| Structural Attribute | Residential Mortgage-Backed Securities (RMBS) | Commercial Mortgage-Backed Securities (CMBS) |
| Underlying Collateral | Thousands of small, homogeneous single-family residential loans. | Tens to hundreds of large, heterogeneous commercial property loans. |
| Primary Credit Driver | Borrower personal income, employment status, FICO, and home equity. | Commercial tenant lease revenue, property NOI, occupancy rates, and DSCR. |
| Prepayment Protection | Generally non-existent at loan level (unconditional prepayment rights). | Highly structured (Lockouts, Defeasance, Yield Maintenance). |
| Prepayment Risk Focus | Severe Contraction and Extension risk driven by interest rates. | Low prepayment risk due to robust contractual call protections. |
| Credit Risk Focus | Minimal in Agency RMBS; default risk in Non-Agency RMBS. | Substantial credit risk managed via credit tranching and B-Piece structures. |
| Maturity Structure | Fully amortizing 15- to 30-year terms. | 5- to 10-year interest-only terms ending in large balloon payments. |
| Servicing Framework | Standardized master servicing and default liquidation routines. | Dual-servicer setup: Master Servicer for regular payments, Special Servicer for workouts. |
Strategic Implications for Financial Managers and Institutional Investors
Mortgage-backed securities offer unique risk-adjusted return opportunities across fixed-income strategies, but their structural complexity requires disciplined oversight. Portfolio managers must continuously monitor interest rate shifts, refinancing incentives, property market fundamentals, and macroeconomic trends to manage risk effectively.
By utilizing time-tranched structures, Agency guarantees, and CMBS call protections, institutional investors can customize duration targets, enhance portfolio yields, and optimize asset-liability matching (ALM) frameworks. As financial technology and loan underwriting models continue to evolve, securitized mortgage instruments will remain a central component of modern global capital markets.
