Liability-Driven and Index-Based Strategies represent the foundational methodologies used by global pension funds, insurance companies, sovereign wealth funds, and asset managers to construct robust fixed-income portfolios.
This comprehensive analysis evaluates the strategic management of single and multiple liability structures, examines portfolio immunization across dynamic interest rate environments, details the structural risks of liability hedging, and addresses the operational challenges of executing passive index replication and benchmark selection.
Introduction
In institutional portfolio management, fixed-income allocations serve two distinct primary objectives: matching future cash obligations or replicating broad market performance. The paradigm of asset management has shifted from pure return-seeking mandates toward liability-centric frameworks. For institutions such as defined benefit pension plans and life insurers, investment success is not defined by beating a generic market index, but by ensuring that asset cash flows and valuations evolve in tandem with liability obligations. Simultaneously, for institutions seeking diversified market exposure, index-based strategies provide a low-cost, systematic means of capturing fixed-income beta. Understanding Liability-Driven and Index-Based Strategies requires a deep exploration of immunization mechanics, quantitative risk factor matching, derivative overlay structures, and benchmark architecture.
Evaluating Strategies for Managing a Single Liability
Managing a single isolated liability obligation—such as a guaranteed investment contract (GIC), a single corporate payout, or a principal debt redemption—requires structuring a portfolio whose future value at a specific horizon date is immune to fluctuations in market interest rates.
Classical Immunization Mechanics
Immunization of a single liability is achieved by balancing two opposing economic forces: price risk and reinvestment risk. When interest rates rise, the market value of fixed-income assets declines (price risk), but the income generated from reinvesting coupon payments earns a higher yield (reinvestment risk). Conversely, when interest rates fall, asset values rise, but coupon reinvestment income decreases.
To achieve classical single-liability immunization, three core mathematical conditions must be satisfied:
- Macaulay Duration Matching: The Macaulay duration of the asset portfolio (
 ) must precisely equal the Macaulay duration of the liability (
 ), matching the target investment horizon (
 ).
- Present Value Coverage: The present value of asset cash flows (
 ) must equal or exceed the present value of the liability cash flows (
 ).
- Convexity Optimization: The distribution of asset cash flows around the horizon date must be minimized to reduce structural risk, while maintaining asset convexity (
 ) greater than or equal to liability convexity (
 ).
The monetary measure of duration exposure, known as Money Duration ( ), is calculated as:
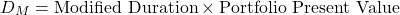
Matching the money duration of assets to liabilities ensures that the absolute dollar valuation change for a given change in yield is identical across both sides of the balance sheet.
Bullet vs. Barbell Portfolio Structures
Asset managers can structure an immunized portfolio using different cash flow distributions:
- Bullet Portfolios: Asset cash flows are tightly clustered around the liability maturity date. This structure minimizes asset cash flow dispersion and lowers portfolio convexity. By keeping cash flows close to the horizon date, bullet portfolios drastically reduce reinvestment risk and structural exposure to yield curve twists.
- Barbell Portfolios: Asset cash flows are split between short-maturity and long-maturity bonds. While a barbell portfolio provides higher overall convexity—which increases portfolio value under large parallel rate shifts—it introduces substantial reinvestment risk and exposes the portfolio to non-parallel yield curve changes.
To minimize structural risk in single-liability management, managers prioritize bullet structures with minimal dispersion over high-convexity barbells.
Cash Flow Matching vs. Duration Matching
A single liability can also be managed via cash flow matching, where a zero-coupon bond matures on the exact date and in the exact amount of the liability obligation. While cash flow matching completely eliminates interest rate and reinvestment risks, zero-coupon instruments of exact maturities may not always be available or liquid. Consequently, duration-matched immunization using coupon-bearing bonds remains the primary operational method.
For example, Pension Insurance Corporation, a UK specialist insurer managing over USD35 billion in pension assets, structures dedicated bullet portfolios of high-grade corporate bonds and sovereign debt to guarantee single-lump-sum pension buyout commitments, maintaining tight duration alignment to insulate balance sheets against rate shifts.
Comparing Single and Multiple Liability Strategies with Alternative Implementations
Extending immunization principles from a single obligation to a stream of multiple future liabilities requires managing complex cash flow structures across multi-decade horizons.
Multiple Liability Immunization
To immunize a stream of multiple liabilities, the portfolio must satisfy multi-variable immunization conditions:
- Present Value Matching:
 .
- Duration Matching: The weighted Macaulay duration of the asset portfolio must equal the weighted Macaulay duration of the liability stream (
 ).
- Convexity Spread: The dispersion of asset cash flows must exceed the dispersion of liability cash flows, meaning asset convexity must be greater than liability convexity (
 ).
- Cash Flow Coverage: The cash flow range of assets must span the full timeline of liability payouts, from the earliest to the latest obligation.
Cash Flow Matching (Cash Laddering)
Cash flow matching for multiple liabilities involves constructing a dedicated bond ladder where coupon income and principal redemptions meet liability payments in every period.
- Advantages: Completely removes interest rate, yield curve, and reinvestment risks; eliminates the need for ongoing rebalancing.
- Disadvantages: Requires access to a vast array of specific bond issues; creates “cash drag” if intermediate coupon payments must be held in low-yielding cash prior to liability payout dates; typically yields lower expected returns than duration-matched strategies.
Alternative Implementation Approaches
Institutional managers employ advanced implementation frameworks to optimize capital efficiency and return generation:
+-----------------------------------------------------------------------------------+
|                         INSTITUTIONAL LDI ALLOCATION                              |
+---------------------------------------------------+-------------------------------+
|             LDI Core (Derivatives)                |      Return-Seeking Core      |
|  - Interest Rate Swaps / Overnight Index Swaps    |  - Global Equities            |
|  - Government Bond Futures & Repurchase Agreements|  - Private Credit & Infrastructure|
|  - Goal: Full Duration & Cash Flow Alignment      |  - Goal: Growth & Capital Gain|
+---------------------------------------------------+-------------------------------+
- Derivatives Overlay Strategies: Instead of purchasing physical bonds to achieve necessary duration, institutions utilize interest rate swaps (receiving fixed rate, paying floating rate), Treasury futures, and swaptions. By using derivatives, a pension plan can construct an LDI core requiring only a fraction of physical capital as collateral.
- Separation of LDI and Return-Seeking Portfolios: Utilizing derivative overlays allows institutions to split the asset base into an LDI core (hedging liability interest rate and inflation risks) and a return-seeking core (invested in equities, private credit, and real estate to eliminate funding deficits).
- Contingent Immunization: An active-passive hybrid strategy where a portfolio is actively managed as long as an asset surplus (safety margin) exists above the required present value of liabilities. If market movements erode the safety margin to a predetermined threshold floor, active management is terminated, and the portfolio is immediately immunized into a passive liability-matching structure.
Legal & General, managing over USD1.3 trillion in global assets, utilizes comprehensive derivative overlay strategies for defined benefit pension clients worldwide, enabling funds to hedge 100% of interest rate and inflation risk while retaining capital in growth-generating real assets.
Evaluating Liability Strategies Under Various Interest Rate Scenarios
Classical immunization models assume that the yield curve is flat and that all yield curve movements are parallel shifts. In real-world financial markets, yield curve movements are predominantly non-parallel, involving steepening, flattening, and butterfly twists.
Non-Parallel Yield Curve Dynamics
When yield curves shift in a non-parallel fashion, matching simple portfolio duration to liability duration is insufficient to protect the portfolio’s funding ratio.
                  TYPICAL YIELD CURVE SHIFT PATTERNS

       Yield                               Yield
         ^    / Parallel Shift               ^   /---\ Steepening
         |   /   (Equal Shift)               |  /     \ (Long rates up)
         |  /                                | /       \
         | /                                 |/         \
         +------------>                      +------------>
                       Maturity                            Maturity
- Steepening Shift: Short-term yields decline or rise less than long-term yields. A barbell portfolio with heavy short-duration exposure will suffer because the long-end capital losses outweigh short-end reinvestment gains.
- Flattening Shift: Long-term yields fall or rise less than short-term yields. Portfolios with longer-maturity assets benefit from capital appreciation, but reinvestment of short-term cash flows occurs at lower relative rates.
- Butterfly Shifts: Involve changes in the curvature of the yield curve (e.g., the belly of the curve moving independently of the 2-year and 30-year points).
Key Rate Duration (KRD) Matching
To immunize portfolios against non-parallel yield curve changes, quantitative managers utilize Key Rate Duration (KRD) matching. Key rate duration measures the sensitivity of a portfolio’s value to a shift in a single specific maturity point along the yield curve, holding all other key rates constant.
A portfolio is fully immunized against non-parallel shifts when its vector of key rate durations matches the liability key rate duration vector across all primary curve points (e.g., 2-year, 5-year, 10-year, 20-year, and 30-year points):
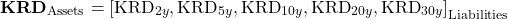
Strategy Selection Framework
The selection of an optimal LDI structure depends directly on macro yield curve expectations and liability characteristics:
| Yield Curve Scenario | Recommended LDI Portfolio Strategy | Structural Rationale |
| Parallel Rate Rise | Bullet Portfolio / High-Yield LDI | Minimizes capital losses while reinvesting intermediate cash flows at higher market rates. |
| Curve Flattening | Long-Duration Bullet / Receiver Swaps | Captures duration gains on the long end while stabilizing liability present valuations. |
| Curve Steepening | Short-Barbell with Derivative Overlays | Protects long-end asset values via receiver swap hedges while holding liquid short paper. |
| High Curve Volatility | Key-Rate Duration Matched Portfolio | Minimizes structural dispersion and protects balance sheets against curve twists. |
Global risk manager Insight Investment applies stochastic interest rate modeling across tens of thousands of scenario paths to calibrate key-rate matching frameworks for liability portfolios totaling over USD800 billion.
Risks Associated with Managing a Portfolio Against a Liability Structure
While liability-driven strategies aim to eliminate financial risk, several structural, operational, and market risks remain inherent to LDI execution.
Structural Risk
Structural risk arises when the cash flow distribution of assets differs significantly from the cash flow distribution of liabilities. Even if Macaulay durations are equal, non-parallel yield curve twists impact asset values differently than liability values. Higher asset cash flow dispersion increases structural risk.
Immunization Target Yield Risk
Immunization models assume that intermediate asset cash flows can be reinvested at the calculated initial yield to maturity (YTM). If market interest rates decline significantly below the initial YTM during the holding period, intermediate reinvestment income falls short of projections, causing the terminal portfolio value to drop below the required liability target.
Spread Risk and Basis Risk
In many regulatory frameworks (such as US GAAP, IAS 19, or Solvency II), pension and insurance liabilities are discounted using high-quality corporate bond yield curves (e.g., AA corporate curves). However, LDI portfolios often hold government bonds (Treasuries, Gilts, Bunds) or interest rate swaps due to liquidity requirements.
- Credit Spread Risk: If corporate bond yields rise relative to government bond yields (spread widening), the present value of liabilities declines faster than the value of government assets, altering the funding ratio.
- Basis Risk: Arises when the floating leg of interest rate derivatives (e.g., SOFR or Euribor) diverges from the underlying discount rate framework of the liabilities.
Liquidity and Collateral Management Risk
Strategies utilizing derivative overlays (interest rate swaps and futures) require maintaining sufficient liquid collateral to meet variation margin calls. If interest rates rise rapidly, the market value of duration-matching receiver swaps drops dramatically.
This risk was vividly demonstrated during the September 2022 UK Gilt market crisis. Rapidly rising yields triggered unprecedented margin calls on derivative-overlay portfolios held by UK defined benefit pension funds. Schemes were forced to execute emergency fire sales of liquid physical assets, including gilts and corporate bonds, driving yields higher in a self-reinforcing liquidity spiral.
Model and Cash Flow Uncertainty Risk
Liability valuations rely on actuarial assumptions, including employee retirement ages, salary growth rates, inflation indexation, and mortality trends. If actual demographic experience deviates from actuarial models, the timing and magnitude of liability cash flows change, rendering the previous asset immunization profile inaccurate.
Bond Indexes and Challenges of Index-Mimicking Strategies
For institutions seeking broad fixed-income market exposure rather than matching specific liabilities, index-based strategies offer a disciplined, systematic framework. However, mimicking a bond index presents operational hurdles not encountered in equity indexing.
Structural Characteristics of Fixed-Income Indexes
Fixed-income indexes exhibit fundamental structural differences compared to equity market indexes:
- Heterogeneity and Scale: Major fixed-income indexes contain thousands of individual bond issues. For example, the Bloomberg US Aggregate Index includes over 13,000 individual instruments across treasury, corporate, agency, and securitized sectors.
- Over-the-Counter (OTC) Trading: Unlike equities that trade on centralized exchanges with continuous bid-ask pricing, most fixed-income instruments trade in fragmented OTC dealer markets.
- Illiquidity and Turnover: A large portion of corporate and municipal bond issues are bought by buy-and-hold institutions and rarely trade in secondary markets after initial issuance.
- Dynamic Index Composition: Bond indexes experience frequent structural turnover as individual bonds mature, drop below minimum maturity thresholds (e.g., less than one year remaining), get called, or undergo credit rating migrations (e.g., “fallen angels” falling from investment-grade to high-yield).
Operational Challenges of Index Replication
- Matrix Pricing Inaccuracy: Because many constituent bonds do not trade daily, index providers utilize matrix pricing (estimating prices based on yield spreads of similar liquid issues). Actual execution prices in the market often deviate from index matrix prices.
- Transaction Costs and Bid-Ask Drag: Full physical replication requires purchasing thousands of illiquid issues. Paying bid-ask spreads across thousands of small bond lots creates substantial trading cost drag.
- Cash Drag: Bond indexes assume instant, seamless reinvestment of intermediate coupon payments into the entire index index distribution. In practice, receiving cash coupons creates cash drag until funds are pooled and deployed.
- New Issuance and Maturing Issue Friction: When new bonds enter an index or maturing bonds exit, index managers must trade to maintain index weights, incurring rebalancing costs that index calculations ignore.
BlackRock, the world’s largest asset manager holding over USD10 trillion in total assets, manages massive index replication portfolios via its iShares fixed-income ETF franchise, employing institutional trading floors and proprietary quantitative matching models to minimize replication drag.
Comparing Alternative Methods for Establishing Passive Bond Market Exposure
To navigate the illiquidity and execution costs of fixed-income indexes, portfolio managers utilize four primary passive exposure methods:
+-----------------------------------------------------------------------------------+
|                        PASSIVE BOND EXPOSURE METHODS                              |
+-------------------+-------------------+-------------------+-----------------------+
|  Full Replication | Stratified        | Quantitative      | Synthetic             |
|                   | Sampling          | Optimization      | Derivatives / ETFs    |
| - High Cost       | - Lower Cost      | - Factor Balanced | - Highly Liquid       |
| - Zero Model Risk | - Minor Tracking  | - Risk-Factor     | - Counterparty Basis  |
|                   |   Error           |   Matched         |   Risk                |
+-------------------+-------------------+-------------------+-----------------------+
1. Full Replication
The manager holds every bond in the index in its exact weight.
- Suitability: Restricted to narrow, highly liquid indexes (e.g., short-term US Treasury indexes).
- Drawback: Cost-prohibitive and practically impossible for broad aggregate indexes.
2. Stratified Sampling (Cell Matching)
The benchmark index is partitioned into discrete multi-dimensional cells based on primary risk characteristics:
- Maturity buckets (e.g., 1-3 years, 3-5 years, 5-10 years, 10+ years)
- Credit rating tiers (AAA, AA, A, BBB)
- Sectors (Government, Industrial, Financial, Utility, Securitized)
- Coupon rates and call features
The manager then selects representative, highly liquid bonds within each cell to match the total cell weight of the index.
3. Quantitative Factor Optimization
Utilizes mathematical multi-factor risk models to construct a reduced-issuer portfolio that matches the core risk factor sensitivities of the index—including duration, key-rate durations, spread duration, convexity, credit quality, and sector weights—while explicitly minimizing expected transaction costs and the total number of holdings.
4. Synthetic Exposure via Derivatives and Exchange-Traded Funds (ETFs)
Managers establish passive market exposure using liquid financial instruments:
- Fixed Income ETFs: Offer immediate, liquid beta exposure with low explicit management fees.
- Total Return Swaps (TRS): The portfolio pays a floating rate (e.g., SOFR) and receives the total return of the target bond index from a dealer counterparty.
- Bond Futures: Provide broad interest rate duration exposure across key curve points.
Methodological Comparison
| Exposure Method | Tracking Error | Transaction & Operational Costs | Liquidity Profile | Execution Complexity |
| Full Replication | Near Zero (Theoretical) | Extremely High | Low (Holds illiquid issues) | Extremely High |
| Stratified Sampling | Low to Moderate | Low to Moderate | High (Selects liquid issues) | Moderate |
| Quantitative Optimization | Low | Moderate | High | High (Requires factor models) |
| Synthetic / Derivatives | Very Low (to Swap Index) | Lowest Explicit Cost | Highest | Low (Subject to margin rules) |
Criteria for Benchmark Selection and Benchmark Justification
Selecting an appropriate benchmark is a critical governance requirement for both liability-driven and index-based fixed income portfolios. A poorly chosen benchmark misaligns manager incentives, obscures true risk exposures, and leads to unhedged liabilities.
Properties of a Valid Benchmark (The SAMURAI Framework)
A valid fixed-income benchmark must satisfy the classic SAMURAI criteria:
- Specified in Advance: The benchmark is defined prior to the start of the evaluation period.
- Appropriate: The benchmark aligns directly with the manager’s investment style, constraints, and mandate.
- Measurable: The benchmark return can be calculated frequently, accurately, and consistently.
- Unambiguous: The identity, individual weights, and constituents of the benchmark securities are clearly defined.
- Reflective of Current Investment Opinions: The manager possesses institutional knowledge and research coverage of the benchmark components.
- Accountable: The investment manager accepts ownership of tracking performance relative to the benchmark.
- Investable: The benchmark consists of actionable, executable assets that can be held or replicated in open markets.
Justification of Benchmark Selection
The justification for benchmark selection depends on the underlying portfolio mandate:
+-----------------------------------------------------------------------------------+
|                        BENCHMARK SELECTION JUSTIFICATION                          |
+---------------------------------------------------+-------------------------------+
|         Liability-Driven Portfolios               |   Index-Based Beta Mandates   |
|  - Custom Liability Benchmark                     |  - Broad Market-Cap Indexes   |
|  - Matched Key-Rate Durations & Discount Curves   |  - Transparent, Highly Liquid |
|  - Goal: Minimize Asset-Liability Variance        |  - Goal: Capture Market Return|
+---------------------------------------------------+-------------------------------+
1. Justifying Benchmarks for Liability-Driven Portfolios
Broad, market-cap-weighted market indexes (such as the Bloomberg Global Aggregate) are fundamentally inappropriate for LDI strategies. Market-cap indexes weight issuers by total debt outstanding—meaning the most indebted issuers carry the largest weight—and their duration reflects market issuance rather than the institution’s specific liability horizon.
- Justification: LDI mandates require a Custom Liability Benchmark or a Liability-Index Overlay. The benchmark is constructed as a custom liability index whose cash flows and key-rate durations mirror the actuarial liability profile of the plan. Success is measured by the stability of the funding ratio (minimizing asset-liability variance) rather than absolute return.
2. Justifying Benchmarks for Index-Based Portfolios
For general fixed income mandates, managers select established broad-market benchmarks, such as the Bloomberg US Aggregate, FTSE World Government Bond Index (WGBI), or ICE BofA Corporate Indexes.
- Justification: These benchmarks offer transparent governance, broad diversification, independent pricing verification, and high investability.
Asset management pioneers Vanguard and PIMCO regularly construct customized benchmark solutions for institutional clients, tailoring duration bounds, ESG screening criteria, and sector exposures to ensure benchmark alignment with institutional balance sheet objectives.
Conclusion
Liability-Driven and Index-Based Strategies represent rigorous quantitative frameworks designed to solve specific institutional asset management challenges. Managing a single liability relies on classical duration matching and bullet cash flow structuring to neutralize price and reinvestment risks. Multi-liability management expands these concepts through key-rate duration vectors, cash-laddering, and derivative overlay frameworks that separate cash management from duration matching.
While LDI strategies insulate balance sheets against parallel and non-parallel rate shifts, institutions must actively manage structural risk, credit spread basis risk, and derivative collateral liquidity. Concurrently, for broad market mandates, index-based strategies navigate fixed-income market illiquidity using stratified sampling and factor optimization to achieve efficient market exposure. Ultimately, whether hedging defined liabilities or tracking market indexes, institutional success requires precise risk factor measurement, robust operational execution, and the selection of investable, alignment-focused benchmarks.
