An essential responsibility of asset owners, institutional consultants, and chief investment officers is the systematic selection, evaluation, and ongoing monitoring of investment managers. Capital allocation decisions require a rigorous governance framework to separate genuine investment skill (alpha) from luck, market beta, or temporary style tilts.
This comprehensive guide outlines the end-to-end investment manager selection framework, covering quantitative and qualitative due diligence, decision-making errors, style analysis techniques, downside risk metrics, team behavioral dynamics, account structures, and performance-based fee mechanics.
The Manager Selection Process and Due Diligence
The manager selection process is a structured, multi-stage workflow designed to identify strategies capable of delivering superior risk-adjusted returns within an investor’s total portfolio framework.
+-------------------------------------------------------------------------------+
|                       1. SOURCING & INITIAL SCREENING                         |
|    Define universe, set quantitative thresholds, filter by strategy alignment  |
+-------------------------------------------------------------------------------+
                                       |
                                       v
+-------------------------------------------------------------------------------+
|                        2. QUALITATIVE DUE DILIGENCE                           |
|       Evaluate philosophy, process, team stability, and culture (4 Ps)        |
+-------------------------------------------------------------------------------+
                                       |
                                       v
+-------------------------------------------------------------------------------+
|                       3. QUANTITATIVE DUE DILIGENCE                           |
|      Analyze performance attribution, risk-adjusted returns, style consistency |
+-------------------------------------------------------------------------------+
                                       |
                                       v
+-------------------------------------------------------------------------------+
|                      4. OPERATIONAL DUE DILIGENCE (ODD)                       |
|   Assess compliance, valuation, IT security, internal controls, trade ops     |
+-------------------------------------------------------------------------------+
                                       |
                                       v
+-------------------------------------------------------------------------------+
|                      5. PORTFOLIO FIT & SELECTION DECISION                    |
|    Model multi-manager correlation, mandate sizing, negotiate fee structures  |
+-------------------------------------------------------------------------------+
                                       |
                                       v
+-------------------------------------------------------------------------------+
|                        6. ONGOING MONITORING & REVIEW                         |
|   Track style drift, key personnel turnover, performance against benchmark    |
+-------------------------------------------------------------------------------+
Components of Operational Due Diligence (ODD)
Operational Due Diligence (ODD) evaluates operational risks that could result in financial loss or reputational damage, independent of market or investment performance. Key focus areas include:
- Governance and Legal Structure: Examination of fund documents (PPM, limited partnership agreements), legal entities, and board independence.
- Operations and Trade Lifecycle: Verification of trade execution, allocation policies, trade reconciliation, and settlement workflows.
- Valuation Policies: Assessment of pricing sources for illiquid or complex securities, checking whether valuation functions are strictly separated from portfolio management teams.
- Compliance and Regulatory Oversight: Review of regulatory filings, internal codes of ethics, personal trading policies, and anti-money laundering (AML) controls.
- Service Provider Verification: Independent verification (“confirmations”) directly with third-party administrators, prime brokers, custodians, and external auditors.
- Technology and Cybersecurity: Audit of IT infrastructure, disaster recovery plans (DRP), business continuity planning (BCP), and cybersecurity safeguards.
Type I and Type II Errors in Manager Decisions
In statistics and decision theory, hypothesis testing frames the decision to hire or fire an investment manager. The null hypothesis ( ) assumes that the manager possesses no value-added skill (
 ).
| Decision Outcome | Null Hypothesis (H0) is True(Manager Has No Skill) | Null Hypothesis (H0) is False(Manager Has Genuine Skill) |
| Hire / Retain Manager | Type I Error ( error) False Positive: Hiring/retaining an unskillful manager. | Correct Decision |
| Reject / Terminate Manager | Correct Decision | Type II Error ( error) False Negative: Firing/rejecting a skillful manager. |
Economic and Behavioral Asymmetries
- Cost of Type I Error (False Positive): Hiring an unskillful manager leads to underperformance, excess management fees paid to non-performing managers, and transaction costs associated with hiring and firing.
- Cost of Type II Error (False Negative): Rejecting or terminating a genuinely skilled manager results in missed excess returns (opportunity costs) and premature termination during temporary style headwinds.
- Asymmetry in Institutional Practice: Asset owners frequently exhibit a bias toward minimizing Type I errors (being overly cautious before hiring). However, in manager continuation decisions, investors frequently commit Type II errors by terminating skilled managers during cyclical drawdowns, replacing them with managers who have recently outperformed but may be at cyclical peaks.
Returns-Based vs. Holdings-Based Style Analysis
Style analysis identifies a manager’s underlying asset allocation and investment style characteristics over time.
+-----------------------------------------------------------------------------------+
|                              RETURNS-BASED STYLE ANALYSIS                         |
|                                         (RBSA)                                    |
|                                                                                   |
|  Regresses portfolio total returns against index benchmarks using constrained OLS |
|                                                                                   |
|  [ Portfolio Returns ] <=== Regression ===> [ Index A ] + [ Index B ] + [ Index C ] |
+-----------------------------------------------------------------------------------+
                                          |
                                          | Contrast
                                          v
+-----------------------------------------------------------------------------------+
|                              HOLDINGS-BASED STYLE ANALYSIS                        |
|                                         (HBSA)                                    |
|                                                                                   |
|   Aggregates security-level characteristics from snapshot portfolio holdings      |
|                                                                                   |
|  [ Portfolio Holdings ] === Top-Down Aggregate ===> [ P/E, P/B, Market Cap, Yield ]|
+-----------------------------------------------------------------------------------+
Comparative Analysis: RBSA vs. HBSA
| Feature / Dimension | Returns-Based Style Analysis (RBSA) | Holdings-Based Style Analysis (HBSA) |
| Primary Method | Multi-factor regression of total portfolio returns against set passive style indices using constrained linear regression. | Aggregation of security-level fundamental metrics (e.g., Weighted Average P/E, Market Cap, Sector Weights) at a point in time. |
| Data Requirements | Long time-series of total portfolio returns (e.g., 36–60 monthly returns). Requires basic return data. | Granular snapshot data of underlying portfolio holdings at month-end or quarter-end. |
| Implementation Cost | Low computational and data cost; straightforward to execute. | High data costs; requires position-level security database access. |
| Timeliness | Lagging indicator. Reflects average historical style exposure over the regression window. | Current snapshot. Reflects exact portfolio characteristics on the report date. |
| Key Strengths | – Works without access to confidential portfolio holdings. – Captures effective asset exposures across complex asset classes. | – Highly accurate for current positioning. – Detects recent style drift immediately. – Ideal for multi-asset or fast-turnover strategies. |
| Key Weaknesses / Limitations | – Can mischaracterize dynamic or rapidly changing portfolios. – Illiquidity in underlying holdings can skew regression results. – Vulnerable to factor multi-collinearity. | – High data burden and potential delay in obtaining complete holdings. – Point-in-time snapshot may miss intra-period trading activity (“window dressing”). |
Downside Risk Metrics and Capture Ratios
Evaluating a manager requires analyzing risk characteristics during asymmetric market environments, particularly down markets.
Mathematical Definitions
- Upside Capture Ratio (UCR):
Where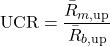
 is the manager’s compound return during periods when the benchmark return (
 ) is positive.
- Downside Capture Ratio (DCR):
Where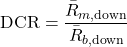
 is the manager’s compound return during periods when the benchmark return (
 ) is negative.
- Up/Down Capture Spread & Ratio:
An Up/Down Capture Ratio greater than 1.0 implies structural return asymmetry (capturing more market upside than downside).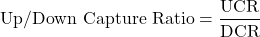
- Maximum Drawdown (MDD):
Measures the maximum peak-to-trough drop in portfolio valuation over a specified time horizon.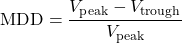
- Drawdown Duration:The time elapsed from the initial peak through the trough until the portfolio recovers to its previous peak level (Trough Recovery Time + Peak-to-Trough Time).
Interpreting Asymmetric Capture Profiling
  Up Market Capture > 100%               Up Market Capture < 100%
  Down Market Capture < 100%             Down Market Capture << 100%
+--------------------------------------+--------------------------------------+
|  HIGH-BETA / ALPHA GENERATOR         |  DEFENSIVE / CAPITAL PRESERVATION    |
|  - Outperforms in bull markets       |  - Lagging in strong bull markets    |
|  - Manages downside exposure         |  - Strong relative protection in bear |
|  - Profile: Growth / Momentum        |  - Profile: Quality Value / Low-Vol  |
+--------------------------------------+--------------------------------------+
  Up Market Capture > 100%               Up Market Capture < 100%
  Down Market Capture > 100%             Down Market Capture > 100%
+--------------------------------------+--------------------------------------+
|  AGGRESSIVE / HIGH RISK              |  STRUCTURAL UNDERPERFORMER           |
|  - Amplifies market movement both    |  - Fails to capture upside while     |
|    ways                              |    participating fully in downside   |
|  - High market beta dependence       |  - Red flag for manager selection    |
+--------------------------------------+--------------------------------------+
Evaluating Investment Philosophy and Decision-Making Process
A manager’s investment philosophy forms the baseline rationale for why market inefficiencies exist and how the firm systematically exploits them. Evaluators assess the Four Ps:
                  +-----------------------------------+
                  |            PHILOSOPHY             |
                  | Underlying core beliefs about how |
                  |  market inefficiencies occur      |
                  +-----------------------------------+
                                    |
                                    v
                  +-----------------------------------+
                  |             PEOPLE                |
                  | Key talent, team depth, culture,  |
                  |    and incentive alignment        |
                  +-----------------------------------+
                                    |
                                    v
                  +-----------------------------------+
                  |             PROCESS               |
                  | Execution framework: Research,   |
                  | Portfolio Design, Risk Management |
                  +-----------------------------------+
                                    |
                                    v
                  +-----------------------------------+
                  |           PERFORMANCE             |
                  | Out-of-sample results matching the |
                  |    stated investment framework    |
                  +-----------------------------------+
Key Questions for Due Diligence Evaluation
- Incentive Alignment: Are portfolio managers significant personal investors in their own strategies (“skin in the game”)? How is compensation structured between short-term performance and long-term multi-year excess return goals?
- Scalability and Capacity Limits: What is the strategy’s total asset capacity before market impact costs erode performance?
- Repeatability: Is performance driven by a structured, repeatable decision process, or is it heavily dependent on a single star manager?
Behavioral Factors in Team Decision-Making and Mitigation Techniques
Investment decisions are subject to cognitive biases and group dynamic flaws that can compromise performance.
| Behavioral Bias / Dynamic | Mechanism & Manifestation | Mitigation Strategy / Best Practice |
| Groupthink | Desire for consensus suppresses dissenting viewpoints, leading to flawed decision-making. | – Appoint a formal Devil’s Advocate for investment committee reviews. – Require pre-voting submissions to avoid bandwagoning. |
| Confirmation Bias | Seeking out evidence that confirms existing thesis while ignoring contradictory data. | – Conduct formal Pre-Mortem Analyses (assuming the thesis failed prior to allocating). – Maintain structured “Bear Case” checklists. |
| Sunk Cost Fallacy / Escalation of Commitment | Doubling down on losing positions to justify initial entry decisions. | – Enforce strict pre-set Stop-Loss Triggers and systematic position-sizing frameworks. – Require independent risk team review for positions exceeding loss thresholds. |
| Overconfidence / Availability Bias | Overestimating decision accuracy based on recent vivid market successes. | – Maintain comprehensive Investment Logs/Journals recording pre-trade rationale. – Conduct post-trade reviews comparing actual vs. expected outcomes. |
Pooled Investment Vehicles vs. Separately Managed Accounts (SMAs)
Selection requires choosing an appropriate legal vehicle structure based on liquidity, operational control, tax efficiency, and cost considerations.
| Feature / Attribute | Pooled Investment Vehicles(Mutual Funds, UCITS, Commingled Funds) | Separately Managed Accounts (SMAs)(Direct Institutional Mandates) |
| Ownership Structure | Investor holds shares/units of a central fund entity. Asset title rests with the fund. | Investor holds direct beneficial ownership of individual underlying securities. |
| Customization & Guidelines | None. Investor must accept the standardized Investment Policy Statement (IPS) of the fund. | High. Full customization of ESG screens, sector exclusions, or risk mandates. |
| Tax Efficiency | Lower. Inflows/outflows by co-investors can trigger embedded capital gains distributions for all holders. | Higher. Direct tax-loss harvesting and custom cost-basis management. |
| Operational & Fee Burden | Lower administrative overhead; costs shared across the investor base. | Higher operational complexity, custody, trading, and account setup fees. |
| Transparency & Reporting | Periodic reporting (monthly/quarterly) of aggregate holdings and sector breakdowns. | Full daily transparency into position-level transactions and holdings. |
| Minimum Capital Threshold | Accessible at low minimums (e.g.,  1,000,000). | High institutional minimums (typically 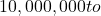 50,000,000+). |
Investment Manager Contracts and Fee Structures
Investment management agreements (IMAs) establish the legal, operational, and fee terms between asset owners and investment managers.
Major Provisions in Investment Management Agreements
- Scope of Mandate & Guidelines: Exact benchmark specifications, eligible asset classes, leverage limits, and liquidity requirements.
- Key Person Clauses: Provisions allowing asset owners to pause trading or terminate contracts if critical investment leaders depart.
- Termination Provisions: Terms for immediate termination with or without cause, outlining notice periods (e.g., 30-day written notice).
Three Basic Forms of Performance-Based Fees
Performance-based fees align manager compensation with excess return generation over a benchmark.
                           PERFORMANCE FEE TYPES
                                     |
         +---------------------------+---------------------------+
         |                           |                           |
         v                           v                           v
+------------------+        +------------------+        +------------------+
|   FULCRUM FEE    |        |   ASYMMETRIC     |        |   ASYMMETRIC     |
|   (SYMMETRIC)    |        |   WITH HURDLE    |        |  HIGH-WATER MARK |
|                  |        |   (BENCHMARK)    |        |   (ABSOLUTE)     |
| Base fee adjusts |        | Base fee plus    |        | Base fee plus    |
| symmetrically    |        | performance share|        | performance share|
| up OR down based |        | above a benchmark|        | above historic   |
| on performance   |        | hurdle rate      |        | net asset peak   |
+------------------+        +------------------+        +------------------+
1. Fulcrum Fees (Symmetrical Fee Model)
- Structure: The base fee adjusts symmetrically based on relative performance against a benchmark. If performance exceeds the benchmark by
 , the fee increases by
 ; if performance lags by , the fee decreases by .
- Mandate Type: Common in traditional institutional long-only equity mandates.
2. Asymmetric Fee Structure with Benchmark Hurdle
- Structure: The manager earns a baseline management fee. If the return exceeds a specified benchmark hurdle rate, the manager receives a percentage share of the excess return. However, underperformance relative to the benchmark reduces fee upside without reducing the base management fee below its floor.
3. Asymmetric Fee Structure with High-Water Mark (Absolute Return)
- Structure: Typical in hedge funds and private market vehicles (e.g., “2 and 20” model). Performance fees are calculated on net capital appreciation above a historic peak portfolio valuation (High-Water Mark), ensuring managers are not paid performance fees for recovering previous losses.
Performance-Based Fee Schedule Analysis
Sample Fee Schedule Parameters
- Account Structure: Institutional Long-Only Separately Managed Account (SMA)
- Assets Under Management (AUM): USD 100,000,000
- Base Management Fee: 0.50% per annum on total AUM
- Performance Fee: 20.0% sharing rate on net excess returns over the Benchmark Index
- Hurdle Rate: Benchmark Return (Relative Hurdle)
- High-Water Mark (HWM) Provision: Applies relative to benchmark excess return
- Maximum Fee Cap: Total annual fee capped at 2.00% of average AUM
Multi-Year Scenario Analysis
Below is an analysis of a USD 100,000,000 institutional mandate over three consecutive operating years.
+-----------------------------------------------------------------------------------+
| YEAR 1: OUTPERFORMANCE                                                            |
| Portfolio Return: +12.00%  | Benchmark Return: +7.00%   | Excess Return: +5.00%   |
| Base Fee: USD 500,000     | Performance Fee: USD 1,000,000                      |
| Total Fee Paid: USD 1,500,000 (1.50% effective fee rate)                          |
+-----------------------------------------------------------------------------------+
                                          |
                                          v
+-----------------------------------------------------------------------------------+
| YEAR 2: UNDERPERFORMANCE                                                          |
| Portfolio Return: -4.00%   | Benchmark Return: -2.00%   | Excess Return: -2.00%   |
| Base Fee: USD 500,000     | Performance Fee: USD 0 (Deficit carried forward)     |
| Total Fee Paid: USD 500,000 (0.50% effective fee rate)                            |
+-----------------------------------------------------------------------------------+
                                          |
                                          v
+-----------------------------------------------------------------------------------+
| YEAR 3: RECOVERY & CATCH-UP                                                       |
| Portfolio Return: +15.00%  | Benchmark Return: +8.00%   | Gross Excess: +7.00%    |
| Net Excess after Y2 Deficit Offset (-2.00%): +5.00%                               |
| Base Fee: USD 500,000     | Performance Fee: USD 1,000,000                      |
| Total Fee Paid: USD 1,500,000 (1.50% effective fee rate)                          |
+-----------------------------------------------------------------------------------+
Detailed Year-by-Year Calculations
Year 1: Outperformance Period
- Gross Portfolio Return:

- Benchmark Return:

- Gross Excess Return:
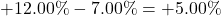
- Base Management Fee:
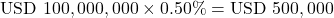
- Performance Fee Calculation:
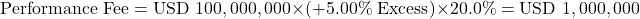
- Fee Cap Check:
Result: Below the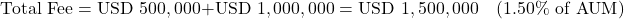
 fee cap (
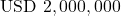 ). Full fee is payable.
- Net Return to Investor:
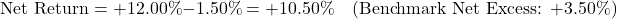
Year 2: Underperformance Period
- Gross Portfolio Return:

- Benchmark Return:

- Gross Excess Return:
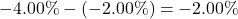 (Negative Excess Return)
- Base Management Fee:
- Performance Fee Calculation: No performance fee earned due to benchmark lag.
- High-Water Mark (Excess Deficit) Carryforward: A relative benchmark deficit is carried into Year 3.
- Total Fee Paid:
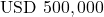 (
 effective rate).
Year 3: Recovery and High-Water Mark Catch-Up
- Gross Portfolio Return:

- Benchmark Return:

- Current Period Gross Excess Return:
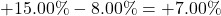
- High-Water Mark / Deficit Adjustment:
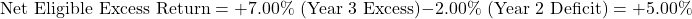
- Base Management Fee:
- Performance Fee Calculation:
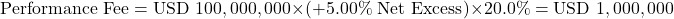
- Total Fee Paid:
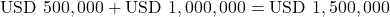 (
 effective rate).
Conclusion & Manager Selection Summary Framework
Selecting investment managers requires combining qualitative evaluation with quantitative risk analysis.
By implementing robust operational due diligence, using downside risk metrics, mitigating behavioral team biases, and structuring fee schedules with high-water marks and deficit carryforwards, asset owners can build resilient, cost-effective multi-manager portfolios aligned with their long-term objectives.
