An Introduction to Equity Valuation provides business executives, corporate managers, institutional investors, and financial analysts with the analytical foundation needed to estimate the true economic worth of common shares, distinguish public market quotes from intrinsic value, and execute rigorous capital allocation strategies.
This introductory guide examines the core principles of security valuation, beginning with the crucial distinction between market price and intrinsic value.
It evaluates key balance sheet and market indicators—including book value of equity, market capitalization, and enterprise value—and provides a detailed analysis of the three major categories of valuation models: present value models, relative valuation multipliers, and asset-based approaches.
Introduction to Equity Valuation
Equity valuation represents the process of determining the fair economic value of an ownership interest in a corporation. For executive leadership, institutional investors, financial advisors, and academic professionals, mastering an Introduction to Equity Valuation is essential for evaluating strategic mergers and acquisitions, structuring corporate equity issuances, managing investment portfolios, and assessing corporate performance.
At its core, equity valuation seeks to translate a company’s past operational results, current balance sheet strength, competitive advantages, and future growth prospects into a quantified economic estimate. Equity securities represent residual claims on corporate cash flows and assets. Unlike debt instruments, which feature contractual coupon payments and fixed maturity dates, equity investments yield variable cash flows dependent on managerial execution, industry dynamics, macroeconomic conditions, and competitive disruption. Consequently, valuing equity requires combining quantitative financial modeling with qualitative corporate analysis.
In global capital markets, valuation models serve as a common analytical language across different market participants:
- Corporate Executives and Board Members: Utilize equity valuation to evaluate strategic investments, determine buyback thresholds, benchmark capital costs, and negotiate corporate acquisitions.
- Sell-Side Equity Research Analysts: Build explicit forecast models to establish target share prices and formulate investment recommendations for corporate clients and institutional traders.
- Buy-Side Fund Managers and Value Investors: Compare estimated intrinsic values against prevailing exchange prices to identify underpriced or overpriced securities for long-term allocation.
- Regulators, Tax Authorities, and Legal Advisors: Apply valuation frameworks in court proceedings, estate tax filings, transfer pricing disputes, and restructuring cases.
Understanding equity valuation requires recognizing that no single quantitative formula produces an indisputable measure of corporate worth. Every financial model relies on underlying assumptions regarding revenue trajectories, profit margins, capital expenditure requirements, terminal growth rates, and cost of capital. A thorough analysis therefore requires utilizing multiple valuation methodologies to construct a comprehensive evaluation of a firm’s equity.
Distinguishing Price from Value in Equity Securities
A fundamental principle in an Introduction to Equity Valuation is the distinction between market price and intrinsic value. Although these terms are frequently used interchangeably in public commentary, they represent fundamentally different financial concepts.
Market price represents the instantaneous transaction price at which an equity security trades on an organized exchange, such as the New York Stock Exchange, Nasdaq, or Euronext. It reflects the point of convergence between immediate supply and demand among public buyers and sellers. Market price is influenced by trading volume, liquidity preferences, short-term earnings announcements, macroeconomic sentiment, algorithmic execution, and human psychology.
In contrast, intrinsic value—often termed fundamental value or fair value—represents the present value of all expected future cash flows generated by the firm, discounted at an interest rate reflecting the risk profile of those cash flows. Intrinsic value is an estimate of what a security is truly worth based on uncompromised financial analysis of corporate fundamentals, competitive moat, industry structure, and economic outlook.
Market Price  = Instantaneous Clearing Point (Supply vs. Demand, Sentiment, Liquidity)
Intrinsic Value = Present Value of All Future Cash Flows (Fundamentals, Moat, Risk)
The relationship between market price and intrinsic value is governed by varying degrees of market efficiency. Under the Efficient Market Hypothesis (EMH), developed by Eugene Fama, financial markets reflect available information in security prices. In its strong form, price constantly equals intrinsic value. However, empirical market behavior demonstrates that security prices frequently deviate from their underlying intrinsic values due to informational asymmetry, behavioral biases, market overreaction, and temporary liquidity shortages.
Benjamin Graham, widely recognized as the father of value investing, illustrated this distinction through the allegory of “Mr. Market”—an emotional business partner who offers to buy or sell corporate shares at different prices each day. When market participants are overly optimistic, market prices rise well above intrinsic value; when fear dominates, market prices plunge below intrinsic value.
Consider the real-world comparison between Apple and Samsung Electronics. In public equity markets, Apple trades at a market capitalization of approximately USD3.77 trillion to USD4.22 trillion, driven by investor confidence in its software ecosystem, high return on invested capital, and pricing power. Conversely, Samsung Electronics, despite holding a balance sheet with total assets of roughly USD380 billion and a book value of equity near USD260 billion (compared to Apple‘s book value of equity of approximately USD62 billion to USD73.7 billion), trades at a market capitalization of around USD290 billion. Public market pricing reflects differences in profitability, profit conversion efficiency, and return on equity, illustrating how market price departs from historical accounting cost.
The primary objective of fundamental equity research is to identify mispricings where market price deviates from estimated intrinsic value. Investors apply a “margin of safety”—purchasing securities only when market price is lower than the calculated intrinsic value—to protect capital against forecasting errors and unanticipated market disruption.
Financial Indicators of Intrinsic Value
To establish a company’s intrinsic value, analysts evaluate three fundamental indicators derived from financial statements and market trading data: book value of equity, market capitalization, and enterprise value. Each metric provides a distinct viewpoint on corporate worth and capital structure.
Book Value of Equity
Book value of equity, or shareholders’ equity, represents the net asset value of a company recorded on its balance sheet in accordance with International Financial Reporting Standards (IFRS) or U.S. Generally Accepted Accounting Principles (GAAP). It is calculated as total assets minus total liabilities.
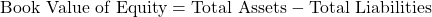

Book value reflects historical accounting costs adjusted for accumulated depreciation, amortization, retained earnings, and capital transactions. It indicates the historical net capital contributed by equity holders plus accumulated profits retained within the business.
While book value provides a verified accounting metric, its effectiveness as an indicator of intrinsic value varies significantly across industries:
- Capital-Intensive Sectors: In industries such as banking, real estate, and insurance, book value serves as a relevant base metric because financial assets and property are marked to market or closely track current fair value.
- Knowledge and Technology Sectors: For asset-light technology corporations like Microsoft, book value severely underestimates intrinsic value because accounting standards mandate expensing research and development (R&D), human capital investments, and brand equity rather than capitalizing them as balance sheet assets.
Market Capitalization
Market capitalization (market cap) measures the total equity value of a publicly traded company according to secondary market trading. It is calculated by multiplying the current market share price by the total number of common shares outstanding.
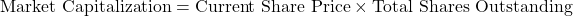

Market capitalization reflects public equity market expectations regarding a firm’s future earnings power, growth potential, and operational stability. It categorizes public corporations into distinct capitalization tiers (mega-cap, large-cap, mid-cap, small-cap, micro-cap), which institutional investors use to construct asset allocations and investment mandates.
However, market capitalization has specific limitations when used as a sole indicator of total corporate value:
- Exclusion of Debt Obligations: Market capitalization measures only the value accruing to common equity holders, ignoring the firm’s debt obligations and preferred share capital.
- Short-Term Volatility: Because market capitalization relies directly on current share prices, it fluctuates with daily market sentiment, making it prone to short-term mispricing.
Enterprise Value
Enterprise Value (EV) measures the total economic value of a company’s underlying operational assets, independent of its capital structure. It represents the theoretical cost an acquirer would incur to purchase the entire business enterprise, assume all outstanding debt obligations, and absorb non-operating cash reserves.
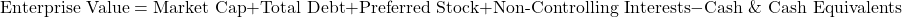

Enterprise value provides a capital-structure-neutral basis for evaluation by accounting for both equity and debt financing. By subtracting cash and liquid marketable securities, EV isolate the net operating assets needed to generate business operations.
For instance, consider a major energy firm such as Shell. Evaluating Shell solely through market capitalization ignores its total debt obligations and cash position. An enterprise value calculation adjusts market capitalization by adding short-term and long-term interest-bearing debt and deducting liquid cash reserves, yielding an EV of approximately USD306 billion. This calculation provides acquirers and analysts with a complete measure of the firm’s net operating assets.
Similarly, examining automotive manufacturer Toyota Motor Corporation highlights the difference between market capitalization and enterprise value. Toyota Motor Corporation maintains significant corporate debt stemming from its automotive financing division alongside sizeable cash reserves. Calculating Toyota Motor Corporation‘s EV provides a more comprehensive view of the capital required to acquire its operational business than viewing market capitalization alone.
Comparative Analysis of Core Value Metrics
The table below contrasts Book Value of Equity, Market Capitalization, and Enterprise Value across financial definitions, primary applications, and operational limitations:
| Financial Metric | Core Definition | Calculation Formula | Primary Applications | Key Strengths | Major Limitations |
| Book Value of Equity | Accounting value of net assets owned by equity holders | 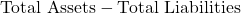 | Liquidation analysis, commercial banking, financial institutions | Objective, verified historical accounting data | Omits off-balance-sheet intangibles, intellectual property, and future growth |
| Market Capitalization | Aggregated market value of public common shares | 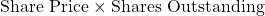 | Index weighting, equity benchmark allocation, public valuation | Real-time market data, simple calculation | Omits corporate debt obligations, influenced by short-term market volatility |
| Enterprise Value | Total economic value of operating business assets | 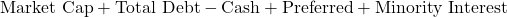 | Mergers & Acquisitions (M&A), capital-structure-neutral valuation | Eliminates debt leverage distortions, evaluates full operating enterprise | Requires detailed balance sheet adjustments for cash, minority interests, and non-operating assets |


Major Categories of Equity Valuation Models
Financial analysts categorize equity valuation methods into three main groups: present value models, relative valuation multipliers, and asset-based models. Each group relies on distinct theoretical assumptions, financial inputs, and operational procedures.
Present Value Models (Discounted Cash Flow Models)
Present value models, commonly referred to as Discounted Cash Flow (DCF) models, represent the theoretical foundation of equity analysis. These absolute valuation models determine the intrinsic value of a security by estimating its expected future economic cash flows and discounting them back to the present using a discount rate that reflects the investment’s risk level.
The general formula for present value equity models is expressed as:
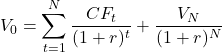

Where:


Within present value methodologies, three primary model types are widely utilized:
Dividend Discount Model (DDM)
The Dividend Discount Model estimates equity value as the present value of all future dividend payouts. For firms exhibiting stable long-term growth, analysts apply the Gordon Growth Model variant:


Where 


Free Cash Flow to Equity (FCFE) Model
The FCFE model measures the cash flow available for distribution to common shareholders after accounting for operating expenses, tax liabilities, interest obligations, net debt repayments, and working capital and capital expenditure investments.
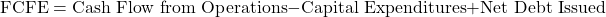

Cash flows are discounted at the required return on equity (

Free Cash Flow to Firm (FCFF) Model
The FCFF model measures the total cash flow available to all capital providers—including common shareholders, preferred equity holders, and debt holders—after funding necessary capital investments and operating expenses.
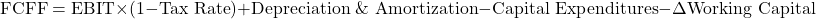

Because FCFF measures operating cash flows accruing to both debt and equity holders, cash flows are discounted using the Weighted Average Cost of Capital (WACC). Subtracting total debt value from the resulting Enterprise Value yields the intrinsic value of common equity.
FCFF Model Flow:
[ Calculate Operating Cash Flows (FCFF) ]
                  │
                  ▼
[ Discount via WACC to obtain Enterprise Value (EV) ]
                  │
                  ▼
[ Subtract Net Debt & Preferred Capital ]
                  │
                  ▼
[ Result: Intrinsic Value of Common Equity ]
Advantages of Present Value Models
- Theoretical Rigor: Directly grounded in finance theory—value equals the present value of future cash flows.
- Operational Independence: Less susceptible to short-term market sentiment or market wide mispricings.
- Customization: Allows explicit modeling of strategic operational changes, capital spending, margin shifts, and tax impacts.
Disadvantages of Present Value Models
- Sensitivity to Inputs: Small changes in discount rate (
- Forecast Uncertainty: Requires explicit long-term operational assumptions, making multi-year projections inherently uncertain for cyclical or early-stage businesses.
Multiplier and Relative Valuation Models
Relative valuation models estimate the value of an equity security by comparing its financial metrics to those of similar operating companies or relevant historical industry benchmarks. Instead of deriving absolute cash flow estimates, relative valuation relies on standardized financial ratios or valuation multiples.
The fundamental assumption underlying relative valuation is that similar financial assets should trade at comparable price multiples. The three most common valuation multipliers are:
Price-to-Earnings (P/E) Ratio
The P/E ratio measures the price paid per dollar of net income earned per share.
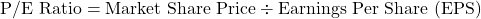

Analysts distinguish between Trailing P/E (utilizing historical 12-month net income) and Forward P/E (utilizing projected 12-month consensus earnings forecasts). High P/E ratios signal expectations of elevated future earnings growth, superior profit stability, or lower perceived investment risk.
Price-to-Book (P/B) Ratio
The P/B ratio compares market capitalization to the balance sheet book value of equity.
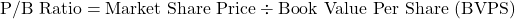

This ratio is widely applied in evaluating financial institutions, capital-intensive manufacturing entities, and real estate investment trusts.
Enterprise Value to EBITDA (EV/EBITDA) Multiple
The EV/EBITDA multiple measures total enterprise value relative to Earnings Before Interest, Taxes, Depreciation, and Amortization.
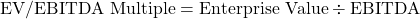

EV/EBITDA is capital-structure-neutral, enabling valid comparisons between companies with differing debt structures or varying international tax regulations.
For example, when evaluating global luxury enterprise LVMH, financial analysts combine relative P/E multiples with EV/EBITDA analysis against comparable luxury peers to establish market-clearing valuation ranges.
Advantages of Relative Valuation Models
- Market Alignment: Reflects current market conditions, pricing trends, and investor appetite.
- Efficiency: Easy to compute, update, and communicate using publicly available market data.
- Simplicity: Provides a straightforward mechanism for benchmarking peer companies.
Disadvantages of Relative Valuation Models
- Market Mispricing Risk: If an entire sector is mispriced by public sentiment, relative valuation will perpetuate that systemic distortion.
- Comparability Limits: Truly comparable peer firms rarely exist due to variations in product portfolios, geographic exposure, leverage, and growth rates.
- Accounting Differences: Variances in accounting policies across jurisdictions can distort earnings and asset multiples.
Asset-Based Valuation Models
Asset-based valuation estimates the intrinsic value of an equity security by calculating the total value of its individual assets and subtracting its liabilities. This approach treats the enterprise as a collection of individual tangible and intangible assets rather than an ongoing cash-generating operating entity.
Asset-based valuations use three primary asset valuation methods:
- Adjusted Net Asset Value: Balance sheet assets and liabilities are adjusted from historical accounting costs to current fair market value.
- Liquidation Value: Estimates the net cash proceeds that would be realized if operations ceased immediately, assets were sold under distressed or orderly conditions, and liabilities were settled.
- Replacement Cost Method: Estimates the total capital cost required to replicate the firm’s physical infrastructure, technology, intellectual property, and operating assets from scratch.
Asset-based models are primarily applied in specific situations: evaluating holding companies, appraising natural resource firms, valuing real estate enterprises, and assessing distressed companies facing restructuring or liquidation.
For instance, asset-based valuation is useful when appraising investment holding firms or capital-intensive industrial organizations like Toyota Motor Corporation, where underlying real estate, manufacturing plants, equipment, and equity holdings can be systematically appraised.
Advantages of Asset-Based Models
- Tangible Baseline: Provides a concrete valuation floor based on physically verifiable assets.
- Useful in Distress: Offers reliable valuation estimates when firm cash flows are negative or unpredictable.
- Reduced Long-Term Reliance: Does not depend on speculative long-term cash flow or revenue growth forecasts.
Disadvantages of Asset-Based Models
- Ignores Going-Concern Value: Fails to capture synergistic value created by operational integration, customer relationships, or managerial talent.
- Intangible Valuation Difficulty: Estimating fair values for proprietary software, brand assets, and patents can be subjective.
Comprehensive Matrix of Equity Valuation Models
The table below summarizes the three major categories of equity valuation models, comparing their underlying methodologies, key inputs, suitable applications, and major trade-offs:
| Valuation Model Category | Fundamental Underlying Methodology | Key Input Variables Required | Best Suited Applications | Major Operational Advantages | Key Analytical Disadvantages |
| Present Value Models (DCF, DDM, FCFE, FCFF) | Intrinsic value equals the discounted present value of expected future cash flows | Projected cash flows, discount rate (WACC or | Companies with predictable cash flows, long-term investments | Independent of short-term market noise; theoretically sound | Highly sensitive to small changes in inputs; relies on uncertain forecasts |
| Relative Valuation Models (P/E, P/B, EV/EBITDA) | Intrinsic value estimated relative to peer trading multiples | Market prices, peer operational metrics (EPS, EBITDA, Revenue) | Public equities, active industries, quick screening | Simple to calculate; reflects current market conditions | Can perpetuate sector-wide mispricings; hard to find true peer matches |
| Asset-Based Models (Net Asset Value, Liquidation) | Value equals the current market value of assets minus liabilities | Adjusted fair value of tangible and intangible assets, liabilities | Holding companies, real estate, natural resources, liquidation | Provides a concrete valuation floor; reliable for troubled firms | Ignores going-concern synergy; hard to value intangible assets |
Strategic Synthesis and Real-World Application
In practical corporate finance and institutional asset management, practitioners rarely rely on a single valuation model. Instead, professional analysts apply a combination of methodologies—frequently summarized in a “football field” valuation chart—to establish a reasonable range of fair value.
Football Field Valuation Chart (Example Illustrative Range in USD):
DCF Range         : [====================] (USD140 - USD185)
P/E Peer Range    :     [==============]   (USD150 - USD175)
EV/EBITDA Range   :   [================]   (USD145 - USD180)
Asset-Based Floor : [========]             (USD110 - USD130)
Combining multiple valuation techniques provides several key practical benefits:
- Cross-Verification: DCF models establish a baseline intrinsic value, while relative valuation metrics confirm whether the DCF output is realistic compared to current market conditions.
- Sensitivity Analysis: Changing discount rates, cash flow growth rates, or operating margin assumptions allows managers to stress-test valuations under different economic scenarios.
- Contextual Flexibility: Multi-stage DCF models suit high-growth technology corporations, while relative multiples are effective for mature industrial firms, and asset-based methods provide a lower bound for holding companies or distressed businesses.
By systematically applying these approaches, financial decision-makers can reduce analytical bias, navigate changing market conditions, and make informed capital allocation decisions.
Conclusions
An Introduction to Equity Valuation highlights the foundational principles, analytical metrics, and quantitative frameworks required to determine the true value of common shares. Understanding the essential difference between market price—a short-term equilibrium point of market supply and demand—and intrinsic value—the discounted present value of expected cash flows—is critical for making sound investment and capital allocation decisions.
Evaluating accounting metrics such as book value of equity, market indicators like market capitalization, and capital-structure-neutral measures like enterprise value provides a structured approach to assessing corporate balance sheets and operating assets. Furthermore, combining present value models, relative valuation multipliers, and asset-based methodologies allows corporate leaders, institutional investors, and financial analysts to move beyond individual model limitations and establish robust fair value ranges. Mastered effectively, equity valuation serves as an indispensable tool for navigating global capital markets, optimizing M&A execution, and building long-term corporate value.

