An introduction to commodity markets provides foundational insights into physical assets that drive the global economy. Unlike financial assets such as equities or fixed-income securities, commodities are physical goods—ranging from crude oil and natural gas to gold, wheat, and copper—that are extracted, grown, or processed.
Understanding their physical characteristics, supply chain life cycles, market participant behaviors, pricing mechanics, and index construction methods is essential for institutional investors, corporate treasurers, and market analysts.
This article provides a comprehensive analysis of commodity sectors, market mechanics, valuation frameworks, derivative structures, and index dynamics.
Characteristic Comparison of Major Commodity Sectors
Commodities are generally divided into major sectors, each defined by distinct physical attributes, storage constraints, seasonal supply-demand dynamics, and economic sensitivity.
| Commodity Sector | Representative Commodities | Storage & Transportation Costs | Supply Dynamics & Elasticity | Demand Drivers & Economic Sensitivity |
| Energy | Crude Oil (WTI, Brent), Natural Gas, Refined Products | High storage costs; requires pipelines, specialized tankers, and localized facilities. | Inelastic short-term supply due to heavy capital investment and geopolitical constraints. | Highly cyclical; tied directly to global macroeconomic growth, industrial output, and transportation. |
| Industrial Metals | Copper, Aluminum, Zinc, Nickel | Moderate storage costs; dense weight requires bulk rail and ocean freight. | Inelastic short-term supply; long capital expenditure lead times (5–10 years for new mines). | Strongly tied to global manufacturing, construction, global infrastructure, and urban development. |
| Precious Metals | Gold, Silver, Platinum, Palladium | Low relative storage cost; high security and vaulting costs relative to physical volume. | Highly inelastic supply; massive global above-ground stocks exist (especially for gold). | Driven by inflation hedging, safe-haven demand, currency dynamics, and central bank reserves. |
| Agriculture | Wheat, Corn, Soybeans, Coffee, Sugar | High storage costs relative to value; vulnerable to spoilage, pests, and moisture. | Highly seasonal; short-term supply depends on weather patterns, acreage allocation, and crop yields. | Inelastic baseline demand (food security), impacted by population growth, diets, and biofuel mandates. |
| Livestock | Live Cattle, Feeder Cattle, Lean Hogs | High short-term maintaining costs; living animals require continuous feed and veterinary care. | Dependent on animal breeding and lifecycle timelines; highly perishable once slaughtered. | Tied to consumer disposable income, protein consumption shifts, and feed costs. |
Life Cycle of Commodity Sectors: Production to Consumption
The life cycle of a commodity spans its initial extraction or growth through processing, transportation, trading, and final end-user consumption.
Energy Sector Life Cycle
- Production: Exploration, drilling, and extraction (upstream).
- Processing: Refining crude oil into gasoline, diesel, and jet fuel, or processing raw gas (midstream).
- Transportation: Moving products via pipelines, rail, or tankers to storage hubs (e.g., Cushing, Oklahoma, or Rotterdam).
- Trading & Consumption: Traded on spot and derivative exchanges (NYME/ICE) before delivery to end consumers, industrial users, or utilities (downstream).
Agricultural Life Cycle
- Production: Planting seeds, fertilizing, harvesting, and field treatment dependent on annual weather cycles.
- Processing & Storage: Drying, sorting, and holding crops in regional grain elevators.
- Transportation: Rail and river barges transport crops to export terminals or domestic mills.
- Trading & Consumption: Futures contracts (CBOT) lock in prices before processing into food products, animal feed, or biofuels.
Metals Life Cycle
- Production: Ore extraction, crushing, concentration, and smelting.
- Processing: Refining metal into standardized ingots, cathode plates, or bars matching exchange specifications (e.g., London Metal Exchange warrants).
- Trading & Consumption: Metal is held in exchange-approved vaults until sold to manufacturers for industrial production or held as investment bullion.
Valuation of Commodities vs. Equities and Bonds
The valuation framework for commodities differs fundamentally from that of financial assets due to the absence of direct cash flows.
Financial Asset Valuation (DCF Model):
Value = ∑ [ Cash Flow_t / (1 + r)^t ]

Commodity Valuation (Cost-of-Carry Model):
Spot Price = Future Price Expectations - Net Carrying Costs + Convenience Yield- Equities: Valued using the discounted cash flow (DCF) framework, reflecting the present value of future corporate earnings, free cash flows, and dividends. Equities benefit from corporate capital allocation, productivity gains, and economic growth.
- Bonds: Valued by discounting explicit contractual cash flows (coupon payments and principal return) using appropriate risk-adjusted discount rates and yield curves.
- Commodities: Do not generate internal cash flows, interest, or dividends. Holding physical commodities incurs carrying costs (storage, insurance, wastage). Therefore, physical commodities are valued through supply-demand balance models, marginal cost of production, and the cost-of-carry framework:
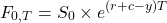
Where:
 = Current spot price
 = Futures price for delivery at time

 = Risk-free interest rate
 = Physical storage and insurance costs (percentage)
 = Convenience yield (the non-monetary benefit of holding physical inventory)
Types of Participants in Commodity Futures Markets
Participants in commodity markets are broadly categorized by their operational motivations and trading objectives.
┌─────────────────────────────────────────────────────────┐
│              Commodity Market Participants              │
└────────────────────────────┬────────────────────────────┘
                             │
       ┌─────────────────────┼─────────────────────┐
       ▼                     ▼                     ▼
┌──────────────┐      ┌──────────────┐      ┌──────────────┐
│   Hedgers    │      │ Speculators  │      │ Arbitrageurs │
│(Commercials) │      │(Non-Comm.)   │      │(Market Makers│
└──────────────┘      └──────────────┘      └──────────────┘
- Hedgers (Commercial Producers and Consumers):
- Examples: Mining corporations (e.g., BHP), oil producers (e.g., ExxonMobil), airlines, agricultural processors.
- Motivation: Mitigate price volatility. Producers short futures to lock in selling prices; industrial consumers buy futures to fix input costs.
- Speculators (Non-Commercial Investors):
- Examples: Commodity Trading Advisors (CTAs), hedge funds, institutional asset managers, retail traders.
- Motivation: Profit from price movement predictions. Speculators absorb price risk from hedgers, providing market liquidity.
- Arbitrageurs and Market Makers:
- Examples: Physical commodity trading houses (e.g., Vitol, Trafigura, Glencore), investment bank desks.
- Motivation: Capture price discrepancies between regional cash markets, spot vs. futures spreads, or related physical commodities (e.g., crack spreads, crush spreads).
Spot Prices and Futures Prices: Contango vs. Backwardation
The structural shape of the commodity futures curve reflects current supply tightness, storage availability, and market expectations.
Price (USD)
  ^
  │          Contango Curve (F > S) [Upward Sloping]
  │        .───────────
  │      .─
  ├────.────────────────────── Spot Price (S_0)
  │  .─
  │.────────── Backwardation Curve (F < S) [Downward Sloping]
  └───────────────────────────────> Time to Expiry (T)
- Contango Market Structure:
- Definition: Futures price exceeds the current spot price (
 ), resulting in an upward-sloping forward curve.
- Underlying Drivers: Plentiful inventory, high financing costs, elevated storage costs, and low convenience yield (
 ).
- Definition: Futures price exceeds the current spot price (
- Backwardation Market Structure:
- Definition: Spot price exceeds the futures price (
 ), resulting in a downward-sloping forward curve.
- Underlying Drivers: Immediate market inventory shortages, supply disruption fears, and high convenience yield (
 ), prompting market participants to pay a premium for immediate physical availability.
- Definition: Spot price exceeds the futures price (
Theories of Commodity Futures Returns
Three primary financial economic theories explain price formation and expected returns in commodity futures markets:
- Insurance Theory (Keynes’ Theory of Normal Backwardation):
- Producers naturally want to hedge production risk more aggressively than consumers hedge input costs.
- To induce speculators to take long positions, producers sell futures contracts at a discount to expected spot prices (
 ).
- Implication: Long futures positions earn a positive risk premium over time as futures prices converge upward to spot prices at maturity.
- Hedging Pressure Hypothesis:
- Extends Insurance Theory by accounting for consumer hedging demand.
- If producers dominate hedging demand, markets trade in normal backwardation. If industrial consumers dominate hedging demand, markets trade in normal contango (
 ).
- Implication: The magnitude and sign of the risk premium depend on the net balance of producer vs. consumer hedging activity.
- Theory of Storage:
- Focuses on physical supply fundamentals, storage space, and convenience yields.
- Relates the spot-futures price spread directly to cost of carry:
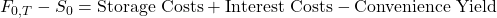 .
- Implication: When inventories are high, convenience yield is low, forcing markets into contango. When inventories are scarce, convenience yield spikes, driving markets into backwardation.
Components of Total Return for a Fully Collateralized Commodity Futures Contract
A fully collateralized long commodity futures position does not require paying the contract value upfront; instead, cash equal to the full nominal value is deposited in safe collateral (like short-term Treasury bills). The Total Return consists of three distinct components:
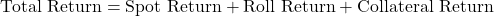
1. Spot Return (Price Return)
The return generated from changes in the underlying spot price over the holding period:
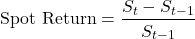
2. Roll Return (Roll Yield)
The return generated from rolling expiring near-term futures contracts into longer-dated futures contracts over time to maintain continuous exposure.
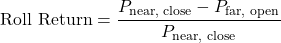
3. Collateral Return (Yield)
The interest earned on US Treasury bills or cash posted as margin/collateral to support the futures contract value.
Calculation & Interpretation Example
Consider a collateralized position in crude oil futures over a 1-year holding period:
- Initial Collateral Deposited: USD 100,000 in US T-Bills yielding 4.0% per annum.
- Spot Price Evolution: Oil spot price rises from USD 70.00 to USD 74.20 (+6.0%).
- Futures Roll Activity: Over the year, rolling maturing contracts generated an aggregate +3.5% gain due to backwardated forward curves.
Total Return Breakdown Calculation:
• Spot Return:       +6.0%
• Roll Return:       +3.5%
• Collateral Return: +4.0%
----------------─────────
• Total Return:     +13.5%
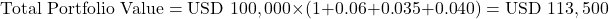
Contrast of Roll Return in Contango vs. Backwardation
Because futures contracts expire, continuous commodity index investors must regularly sell expiring contracts and purchase subsequent contracts (the “roll process”).
┌─────────────────┬──────────────────────────────────┬──────────────────────────────────┐
│ Market Dynamic  │ Roll Action                      │ Roll Return Impact               │
├─────────────────┼──────────────────────────────────┼──────────────────────────────────┤
│ Contango        │ Sell cheaper near-term contract; │ Negative Roll Return             │
│ (F > S)         │ Buy expensive far-term contract  │ (Structural drag on portfolio)   │
├─────────────────┼──────────────────────────────────┼──────────────────────────────────┤
│ Backwardation   │ Sell expensive near-term contract│ Positive Roll Return             │
│ (F < S)         │ Buy cheaper far-term contract    │ (Structural yield boost)         │
└─────────────────┴──────────────────────────────────┴──────────────────────────────────┘
- Impact in Contango Markets: The investor sells a cheaper expiring contract and buys a more expensive subsequent contract. This negative roll yield (“buy high, sell low”) acts as a structural headwind on index returns, causing long-term futures returns to underperform physical spot price gains.
- Impact in Backwardation Markets: The investor sells a higher-priced expiring contract and buys a lower-priced next-out contract. This generates a positive roll yield (“buy low, sell high”), creating an ongoing performance tailwind over time.
Commodity Swaps for Managing Risk Exposure
Commodity swaps are custom over-the-counter (OTC) derivative agreements where parties exchange cash flows linked to commodity prices over fixed intervals without physically transferring the underlying good.
                     Fixed Price Payment (USD/bbl)
               ┌─────────────────────────────────────┐
               │                                     │
      ┌────────┴────────┐                   ┌────────▼────────┐
      │  Commercial     │                   │ Financial Swap  │
      │ Offtaker/User   │                   │ Dealer / Bank   │
      └────────┬────────┘                   └────────▲────────┘
               │                                     │
               └─────────────────────────────────────┘
                    Floating Spot Price (USD/bbl)
Types of Commodity Swaps
- Fixed-for-Floating Swaps: A consumer (e.g., an airline) pays a fixed price per barrel of jet fuel to a bank, receiving the actual floating market spot price in return. This fixes operational fuel input costs.
- Basis Swaps: Cash flows are exchanged based on the price spread between two regional pricing locations (e.g., WTI Cushing vs. Brent North Sea).
- Financial Index Swaps: Cash flows are linked to total return commodity indexes (such as the S&P GSCI or Bloomberg Commodity Index) to gain diversified asset exposure without managing physical futures contracts.
Construction of Commodity Indexes and Impact on Returns
Commodity indexes track sector performance, but variation in index construction methods creates substantial performance differences across benchmark providers.
Key Construction Variables
- Weighting Schemes:
- Liquidity-Weighted: Weights commodities based on trading volume (e.g., Bloomberg Commodity Index – BCOM). Limits energy concentration.
- Production-Weighted: Weights commodities based on global physical production output (e.g., S&P GSCI). Highly dominated by energy sectors (~50–60%), driving higher volatility.
- Roll Mechanics & Optimization:
- Standard Monthly Roll: Automatically rolls into the front-month contract on fixed calendar dates regardless of market curve shape.
- Dynamic/Optimum Roll: Evaluates the shape of the futures curve and selects contracts across maturities (e.g., 6–12 months out) to minimize contango roll drag or maximize backwardation yield.
