A comprehensive guide on Interest Rate Risk and Return, exploring the sources of fixed-rate bond returns, the mechanics of Macaulay duration, and how investment horizons impact portfolio volatility for global corporations and financial institutions.
Introduction to Fixed-Income Markets and Interest Rate Dynamics
Fixed-income securities represent a cornerstone of global capital markets, providing essential financing for governments, municipalities, and multinational corporations while offering investors predictable cash flow streams. However, despite their reputation for stability relative to equities, fixed-rate bonds are subject to complex market risks, chief among them being interest rate risk. Understanding the interplay between interest rate risk and return is vital for corporate treasurers, portfolio managers, institutional investors, and financial analysts worldwide.
When market interest rates fluctuate, the market prices of existing fixed-rate bonds move in the opposite direction. This inverse relationship exposes investors to capital gains and losses if bonds are sold prior to maturity. Furthermore, the total realized return from a fixed-rate bond investment is rarely equal to its initial yield-to-maturity due to the compounding effects of reinvested coupon payments and changes in market conditions. To navigate these complexities, finance professionals rely on analytical tools such as Macaulay duration, which bridges the gap between bond maturity, cash flow timing, and price sensitivity.
This article explores the fundamental sources of fixed-rate bond returns, the calculation and interpretation of Macaulay duration, and the critical relationships governing holding period returns and investment horizons.
Sources of Return from Investing in a Fixed-Rate Bond
To evaluate the performance of a fixed-rate bond investment, an investor must decompose the total return into its constituent components. Unlike equities, where returns are driven by unpredictable corporate earnings and capital appreciation, a bond’s return is derived from three distinct sources: coupon payments, capital gains or losses, and reinvestment income.
Coupon Payments
The primary and most visible source of return is the periodic coupon interest paid by the issuer. For instance, when a major global enterprise like Microsoft Corporation issues corporate bonds with a fixed annual coupon, investors receive steady cash inflows over the life of the instrument. These payments provide a reliable income stream, which forms the baseline yield of the security at purchase.
Capital Gains and Losses
If an investor holds a bond until maturity, the bond will redeem at its par value (typically USD 1,000), eliminating any capital gain or loss resulting from intermediate market price fluctuations. However, if the investor sells the bond prior to maturity, the sale price may differ from the purchase price. If market interest rates decline after purchase, the bond price rises above par or purchase price, generating a capital gain. Conversely, if market interest rates rise, the bond price falls, resulting in a capital loss.
Reinvestment Income (Interest-on-Interest)
Coupon payments received throughout the life of the bond must be reinvested in the market. The income generated by reinvesting these periodic coupon payments at prevailing market interest rates is known as reinvestment income or interest-on-interest. The magnitude of reinvestment income depends heavily on the prevailing interest rate environment during the holding period.
Analyzing Bond Return Sources with Corporate Examples
Consider a corporate bond issued by JPMorgan Chase & Co. with a par value of USD 1,000, an annual coupon rate of 6% (paid annually, resulting in USD 60 per year), and a maturity of 3 years. Suppose an investor purchases this bond at par when the market yield-to-maturity is 6%.
The breakdown of cash flows and return sources over the 3-year investment horizon is summarized in the table below.
| Year | Beginning Book Value (USD) | Coupon Payment Received (USD) | Reinvestment Rate | Total Cash Flow / Accumulation (USD) |
| 1 | 1,000.00 | 60.00 | 6.00% | 60.00 |
| 2 | 1,000.00 | 60.00 | 6.00% | 63.60 (including Year 1 interest) |
| 3 | 1,000.00 | 60.00 + 1,000.00 (Principal) | 6.00% | 1,067.36 |
In this scenario, total cash accumulated at the end of year three equals USD 60.00 × 1.06² + USD 60.00 × 1.06 + USD 1,060.00 = USD 67.36 + USD 63.60 + USD 1,060.00 = USD 1,190.96. The total annualized realized return reflects the combination of coupon income, capital return, and reinvestment income.
Defining, Calculating, and Interpreting Macaulay Duration
Interest rate risk cannot be managed effectively without measuring the price sensitivity of a bond. While maturity date indicates when the final principal is repaid, it fails to account for the timing of intermediate cash flows (coupon payments). To address this limitation, Frederick Macaulay introduced the concept of Macaulay duration in 1938.
Definition of Macaulay Duration
Macaulay duration measures the weighted-average time to receipt of the cash flows generated by a fixed-income security. The weights are determined by the present value of each cash flow relative to the total present value (market price) of the bond. Expressed in years, Macaulay duration serves as a summary statistic of the effective maturity of a bond’s cash flow stream.
Step-by-Step Calculation of Macaulay Duration
Let us calculate the Macaulay duration for the 3-year The Coca-Cola Company corporate bond examined earlier:
- Par Value: USD 1,000
- Annual Coupon Rate: 6% (USD 60 per year)
- Yield-to-Maturity (YTM): 6%
- Maturity: 3 years
The present value of each cash flow discounted at the 6% yield-to-maturity is calculated as follows:
- Year 1 Cash Flow: USD 60 / 1.06 = USD 56.60
- Year 2 Cash Flow: USD 60 / 1.06² = USD 53.40
- Year 3 Cash Flow: USD 1,060 / 1.06³ = USD 890.00
- Total Present Value (Bond Price): USD 56.60 + USD 53.40 + USD 890.00 = USD 1,000.00
Next, we calculate the proportion of total present value represented by each cash flow (weights) and multiply by the time in years:
| Year (t) | Cash Flow (USD) | Present Value (USD) | Weight (Wt) | Time-Weighted Present Value (t×Wt) |
| 1 | 60.00 | 56.60 | 0.0566 | 0.0566 |
| 2 | 60.00 | 53.40 | 0.0534 | 0.1068 |
| 3 | 1,060.00 | 890.00 | 0.8900 | 2.6700 |
| Total | 1,180.00 | 1,000.00 | 1.0000 | 2.8334 |
The sum of the time-weighted present values yields the Macaulay duration:
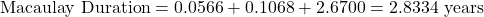

Interpreting Macaulay Duration
The calculated Macaulay duration of 2.8334 years indicates that, on average, the investor recovers the present value of their investment in approximately 2 years and 10 months. Because coupons accelerate cash inflows compared to a zero-coupon bond of identical maturity (which would have a Macaulay duration of exactly 3.0 years), coupon-bearing bonds always exhibit a Macaulay duration shorter than their stated maturity.
For institutional portfolio managers at asset management giants like BlackRock, Macaulay duration provides an indispensable measure of interest rate risk. A higher Macaulay duration implies greater percentage price volatility for a given change in market interest rates.
Relationships Among Holding Period Return, Macaulay Duration, and Investment Horizon
Understanding how interest rate changes affect bond investments requires analyzing the dual opposing forces of price risk and reinvestment risk over a specific investment horizon. The relationship between a bond’s holding period return (HPR), its Macaulay duration, and the investor’s investment horizon determines whether the investor is a net beneficiary or victim of interest rate movements.
Price Risk vs. Reinvestment Risk
When market interest rates change:
- Price Risk: An increase in interest rates decreases bond prices, harming investors who sell before maturity. Conversely, a decrease in rates increases bond prices, benefiting sellers.
- Reinvestment Risk: An increase in interest rates allows coupon payments to be reinvested at higher rates, benefiting long-term investors. Conversely, a decrease in rates reduces reinvestment income.
Because these two risks move in opposite directions, they partially offset each other. The net effect on the holding period return depends entirely on the duration of the investment horizon relative to the bond’s Macaulay duration.
Immunization and Horizon Matching
The critical threshold connecting holding period return and Macaulay duration is the investment horizon:
- Horizon Equals Macaulay Duration: When an investor’s holding period matches the bond’s Macaulay duration, price risk and reinvestment risk exactly offset each other. If interest rates rise, the capital loss on the bond sale is precisely counterbalanced by higher reinvestment income from coupons. If interest rates fall, the capital gain is offset by lower reinvestment income. This strategy is known as immunization, locking in the original yield-to-maturity regardless of subsequent market interest rate shifts.
- Horizon Shorter Than Macaulay Duration: When the investment horizon is shorter than the Macaulay duration, price risk dominates reinvestment risk. If interest rates rise, the price decline of the bond outweighs the minor gain in reinvestment income, resulting in a lower holding period return. If rates fall, the investor achieves a higher holding period return due to capital appreciation.
- Horizon Longer Than Macaulay Duration: When the investment horizon exceeds the Macaulay duration, reinvestment risk dominates price risk. If interest rates rise, the accumulated reinvestment income outweighs the capital loss, leading to a higher holding period return. If rates fall, reinvestment income drops significantly, dragging down the overall holding period return.
Real-World Corporate Applications and Risk Management
Multinational corporations and financial institutions manage vast balance sheets exposed to interest rate volatility. For example, technology leader Apple maintains extensive corporate bond portfolios and debt issuance programs to fund operations, share buybacks, and strategic acquisitions. Corporate treasury teams utilize duration matching and asset-liability management (ALM) frameworks to protect net interest margins and portfolio values against unexpected macroeconomic shifts by central banks such as the Federal Reserve or the European Central Bank.
By adjusting the portfolio’s aggregate Macaulay duration to match projected cash outflow liabilities, companies minimize vulnerability to adverse yield curve movements. Financial analysts evaluating corporate creditworthiness closely examine management’s exposure to interest rate risk, ensuring that debt structures are appropriately hedged or immunized.
Conclusion
Interest rate risk and return represent fundamental concepts in fixed-income analysis. By thoroughly understanding the sources of return—coupon payments, capital gains or losses, and reinvestment income—investors can accurately project cash flows. Furthermore, Macaulay duration serves as a powerful quantitative metric that measures the weighted-average time to cash flow receipt, providing crucial insights into bond price volatility.
Most importantly, recognizing the relationship between holding period return, Macaulay duration, and the investment horizon allows financial professionals to implement immunization strategies that neutralize interest rate risk. Whether managing corporate capital for multinational enterprises or constructing institutional portfolios, mastering these principles ensures robust financial planning and disciplined risk management in dynamic global markets.

