An accurate industry and competitive analysis forms the foundation of strategic planning, equity valuation, and corporate investment decisions.
Conducting a thorough analysis enables corporate executives, financial analysts, and strategy consultants to evaluate the operating environment, anticipate structural shifts, and formulate strategies that yield sustainable competitive advantages.
The Process of Industry and Competitive Analysis
Industry and competitive analysis evaluates the external dynamics influencing a firm’s profitability and market position. Rather than analyzing a business in isolation, this process maps out structural forces, competitor behavior, and broader macroeconomic drivers.
+-------------------------------------------------------------------------------+
|                      PHASE 1: INDUSTRY SCOPE & BOUNDARIES                      |
|  Define sector boundaries, product lines, geographic scale, and value chain. |
+-------------------------------------------------------------------------------+
                                       |
                                       v
+-------------------------------------------------------------------------------+
|                     PHASE 2: STRUCTURAL & PESTLE ANALYSIS                     |
|  Evaluate macro-forces (PESTLE) and competitive structure (Five Forces).      |
+-------------------------------------------------------------------------------+
                                       |
                                       v
+-------------------------------------------------------------------------------+
|                    PHASE 3: COMPETITOR & STRATEGIC MAPPING                    |
|  Group peer companies, analyze market positions, and benchmark financials.    |
+-------------------------------------------------------------------------------+
                                       |
                                       v
+-------------------------------------------------------------------------------+
|                     PHASE 4: SYNTHESIS & STRATEGIC OUTLOOK                    |
|  Project revenue trends, assess profit sustainability, and model risks.       |
+-------------------------------------------------------------------------------+
Phase 1: Defining Industry Scope and Boundaries
An analysis begins by establishing clear industry boundaries:
- Product scope: Identifying direct products, services, and viable substitutes.
- Geographic scope: Distinguishing between local, regional, and global dynamics.
- Value chain mapping: Tracing the lifecycle from raw material extraction to final delivery.
Phase 2: Industry Structural Analysis
This phase examines macroeconomic dynamics alongside competitive dynamics to uncover profit drivers:
- Macro-environmental scanning: Evaluating trends in technology, regulation, demographics, and economics.
- Structural force assessment: Analyzing competitive pressures, supplier and buyer leverage, and barriers to entry.
Phase 3: Competitor Intelligence and Peer Grouping
This phase shifts focus to key industry players:
- Mapping direct, indirect, and potential competitors.
- Classifying companies into strategic groups based on business models, distribution channels, and pricing strategies.
- Benchmarking operating performance, cost structures, and technological capabilities.
Phase 4: Synthesis and Strategic Outlook
The final phase converts data into strategic directives:
- Forecasting total addressable market (TAM) growth and market share shifts.
- Evaluating industry profit pools across segments.
- Identifying key success factors (KSFs) required to sustain above-average returns on invested capital (ROIC).
Industry Classification Methods and Enterprise Groupings
Grouping companies into peer sets allows analysts to evaluate performance, establish valuation multiples, and benchmark operations accurately. Standardized systems and custom frameworks provide different lenses for grouping corporate peers.
Taxonomy of Classification Systems
Standardized systems categorize businesses using defined taxonomies based on revenue sources, principal activities, or economic sensitivity.
Standard Industrial Classification (SIC) and North American Industry Classification System (NAICS)
- SIC System: Developed in the 1930s, this 4-digit numeric code classifies establishments by their primary physical output or production processes.
- NAICS System: Designed to replace SIC, NAICS uses a 6-digit hierarchical structure that prioritizes production processes and emerging technology sectors like information services and biotechnology.
Global Industry Classification Standard (GICS) and Industry Classification Benchmark (ICB)
- GICS Framework: Developed by MSCI and S&P Dow Jones Indices, GICS organizes public companies into 11 Sectors, 25 Industry Groups, 74 Industries, and 163 Sub-Industries based on principal revenue drivers.
- ICB System: Maintained by FTSE Russell, ICB uses a four-tier structure (11 Industry sectors, 20 Supersectors, 45 Sectors, and 173 Subsectors) popular among European institutions for portfolio management and index construction.
Comparative Framework of Grouping Methodologies
The choice of peer grouping methodology depends on the analytical goal. Selecting the right framework ensures meaningful comparisons of valuation, margins, and operational metrics.
| Classification Method | Primary Basis of Grouping | Major Strengths | Primary Limitations | Primary Real-World Application |
| GICS / ICB | Revenue generation and market perception | Universal standardization, updated regularly, seamless peer comparisons | Diversified conglomerates can be misclassified under a single dominant segment | Quantitative equity portfolio management, index creation, relative valuation |
| NAICS / SIC | Production processes and operational output | Detailed sub-segment tracking, standardized government and economic census data | Fails to capture asset-light and modern digital business models | Economic policymaking, corporate tax modeling, trade flow analysis |
| Strategic Group Mapping | Shared strategic dimension (pricing, geographic coverage, R&D depth) | Uncovers direct tactical rivals, highlights strategic barriers to mobility | Requires subjective judgment, manual data gathering, and custom parameters | Corporate strategic planning, targeted competitive positioning |
| Cluster / Network Analysis | Machine learning analysis of product text, SEC filings (10-K descriptions), and customer overlaps | Captures cross-industry rivalries and emerging business models in real time | Complex computation, lacks long historical datasets | Algorithmic trading, M&A target screening, cross-sector threat identification |
Corporate Case Study: Classification in Practice
Enterprise classifications vary across standard systems. Global corporate giants often cross sector boundaries, illustrating how different taxonomy choices shape competitive peer sets:
- Apple Inc. https://www.apple.com/
- GICS Classification: Information Technology (Technology Hardware, Storage & Peripherals).
- Operational Reality: Apple operates across consumer electronics, proprietary semiconductor development, digital advertising, financial payments, and cloud streaming. Placing Apple strictly alongside hardware manufacturers like Dell or HP overlooks its higher-margin Services segment, which generated USD30.01 billion in a single quarter (Q1 FY2026).
- Microsoft Corporation https://www.microsoft.com/
- GICS Classification: Information Technology (Systems Software).
- Operational Reality: Microsoft spans enterprise software, cloud infrastructure (Azure), hardware, and digital gaming (Xbox). In FY2026, Microsoft generated USD331.84 billion in revenue with an operating profit of USD155.24 billion, illustrating how cloud infrastructure scale alters financial profiles compared to traditional software licensing models.
- Toyota Motor Corporation https://global.toyota/
- GICS Classification: Consumer Discretionary (Automobiles).
- Operational Reality: In FY2026, Toyota recorded JPY295.25 net income per share on sales revenues of tens of trillions of yen. While classified as an automaker, its large financial services arm (Toyota Financial Services) operates essentially as a global retail bank, introducing distinct capital structure considerations.
Determining Industry Size, Growth, Profitability, and Market Share Dynamics
Evaluating an industry requires quantifying its core metrics: market size, dynamic growth rates, baseline profitability, and market share distribution.
Sizing the Industry: TAM, SAM, and SOM
Market sizing establishes an industry’s addressable boundary using three core metrics:
- Total Addressable Market (TAM): Total global demand for a product or service category, assuming 100% market penetration.
- Serviceable Addressable Market (SAM): The portion of TAM targeted by a firm’s specific products, geographical focus, and delivery capabilities.
- Serviceable Obtainable Market (SOM): The realistic portion of SAM captured short-term, accounting for capacity constraints and competitive pressure.
+-------------------------------------------------------------------------------+
| TOTAL ADDRESSABLE MARKET (TAM)                                                |
| Total market demand for a category                                            |
|                                                                               |
|   +-----------------------------------------------------------------------+   |
|   | SERVICEABLE ADDRESSABLE MARKET (SAM)                                  |   |
|   | Segment targeted within geographic & operational reach                |   |
|   |                                                                       |   |
|   |   +---------------------------------------------------------------+   |   |
|   |   | SERVICEABLE OBTAINABLE MARKET (SOM)                           |   |   |
|   |   | Target market share realistic to capture short-term           |   |   |
|   |   +---------------------------------------------------------------+   |   |
|   +-----------------------------------------------------------------------+   |
+-------------------------------------------------------------------------------+
Methodologies for Estimating Market Size
- Top-Down Approach: Starts with macro market research data, applying logical filters to narrow down to the target industry segment.
- Bottom-Up Approach: Calculates total size by multiplying unit volumes by average selling price (ASP):
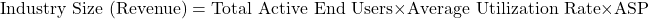

Measuring Growth Characteristics
Industry growth is measured using compound annual growth rates (CAGR) alongside historical sales volumes:
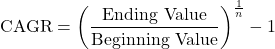

Where 

The Industry Life Cycle Stage Framework
- Introduction Stage: Rapid technological innovation, high market development costs, negative net margins, and limited adoption.
- Growth Stage: Standardized products, rapid volume expansion, expanding profit margins, and lower unit production costs.
- Shakeout Stage: Decelerating demand growth, excess industry capacity, price wars, and market consolidation.
- Maturity Stage: Saturated customer penetration, replacement-driven demand, high barrier maintenance, stable profit margins, and strong cash generation.
- Decline Stage: Structural substitution, shrinking market volumes, margin compression, and industry exits.
Evaluating Industry Profitability
Industry profit margins vary based on capital intensity, asset turnover, pricing leverage, and supply chain concentration. Standard metrics for evaluating profitability include:
- Gross Profit Margin: Demonstrates core unit economics and pricing power.
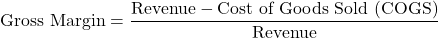
- Operating Margin (EBIT Margin): Isolates operational performance from financing decisions and capital structure.
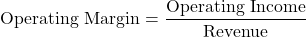
- Return on Invested Capital (ROIC): Evaluates capital allocation efficiency and moat strength.
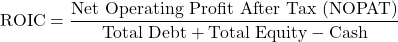


When industry-wide ROIC consistently exceeds the Weighted Average Cost of Capital (WACC), the industry is generating economic value (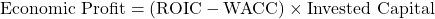

Analyzing Market Share Trends and Concentration
Market share distributions show whether an industry is fragmented, oligopolistic, or consolidated.
Concentration Metrics
- Concentration Ratio (


- Herfindahl-Hirschman Index (HHI): Sums the squared market shares of all industry participants:
(Where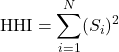


| HHI Range | Market Structure | Competitive Characteristics |
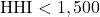 | Unconcentrated / Highly Fragmented | Low pricing leverage, high price-based competition |
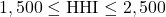 | Moderately Concentrated | Selective pricing power, localized differentiation |
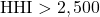 | Highly Concentrated | Strong oligopoly dynamics, elevated profit potential, strict antitrust oversight |


Structural and External Environmental Analysis Frameworks
To understand profitability, strategic analysts use structural frameworks like Porter’s Five Forces alongside macro environmental scanning tools like PESTLE.
Porter’s Five Forces Analysis Framework
Developed by Harvard Business School Professor Michael Porter, this framework evaluates the micro-economic forces shaping industry structure and margin potential.
                       +---------------------------------------+
                       |           THREAT OF NEW               |
                       |             ENTRANTS                  |
                       +---------------------------------------+
                                           |
                                           v
+-----------------------+      +-----------------------+      +-----------------------+
|   BARGAINING POWER    | ---> |  RIVALRY AMONG        | <--- |   BARGAINING POWER    |
|     OF SUPPLIERS      |      | EXISTING COMPETITORS  |      |       OF BUYERS       |
+-----------------------+      +-----------------------+      +-----------------------+
                                           ^
                                           |
                       +---------------------------------------+
                       |          THREAT OF SUBSTITUTE         |
                       |         PRODUCTS OR SERVICES          |
                       +---------------------------------------+
1. Threat of New Entrants
New entrants expand capacity and compete for market share, pressuring incumbent prices.
- Key Determinants: Capital requirements, brand equity, distribution access, proprietary technology, regulatory approval, and switching costs.
- High-Barrier Example: Semiconductor manufacturing requires tens of billions of dollars in capital expenditure per fabrication plant, limiting new entrants.
2. Bargaining Power of Suppliers
Powerful suppliers capture value by raising input costs or restricting supply quality.
- Key Determinants: Supplier concentration relative to buyers, availability of substitute inputs, switching costs between suppliers, and forward integration threats.
- High-Power Example: Commercial aircraft engine manufacturing is concentrated among a few global providers (GE Aerospace, Rolls-Royce, Pratt & Whitney), granting suppliers significant pricing power over airframe assemblers.
3. Bargaining Power of Buyers
Powerful customers force down prices, demand higher quality, or leverage competitors against one another.
- Key Determinants: Buyer concentration, purchase volume as a percentage of total supplier revenue, price sensitivity, product standardization, and backward integration threats.
- High-Power Example: Massive retail buyers exert leverage over small consumer packaged goods (CPG) suppliers by controlling shelf-space access.
4. Threat of Substitute Products or Services
Substitutes limit industry profit potential by establishing an absolute price ceiling.
- Key Determinants: Relative price-performance trade-offs, switching costs, and customer propensity to substitute.
- High-Threat Example: High-speed rail transportation acts as a substitute for short-haul regional flights, limiting air carriers’ pricing flexibility.
5. Rivalry Among Existing Competitors
Rivalry takes the form of price discounting, advertising wars, product launches, and customer service enhancements.
- Key Determinants: Industry growth rate, exit barriers, fixed vs. variable cost structures, capacity additions, and product differentiation.
- High-Rivalry Example: Global commercial airline operations feature high fixed costs, exit barriers, and homogeneous services, leading to frequent price competition during downturns.
The PESTLE Environmental Analysis Framework
The PESTLE framework tracks external macro-environmental factors that create strategic opportunities or systemic risks for an entire industry.
                       PESTLE MACRO-ENVIRONMENTAL ANALYSIS

   [P] OLITICAL           [E] CONOMIC          [S] OCIOCULTURAL
   • Foreign Trade        • Real Interest Rates• Demographic Shifts
   • Geopolitical Align   • Inflation Vectors  • Consumer Values
   • Tax & Tariff Laws    • FX Volatility      • Labor Preferences

   [T] ECHNOLOGICAL       [L] EGAL             [E] NVIRONMENTAL
   • Generative AI & Automation  • Antitrust Rules    • Carbon Reporting
   • Semiconductor Scale  • IP Protections     • Supply Resilience
   • R&D Capital Flows    • Data Privacy (GDPR)• Climate Vulnerability
1. Political Factors
Government policies, international trade relations, tax policy, foreign trade rules, and geopolitical stability.
- Direct Impact: Trade tariffs and export controls on advanced hardware shift global manufacturing footprints and realign supply chain strategies.
2. Economic Factors
Macroeconomic indicators including interest rates, inflation rates, currency movements, structural GDP growth, and capital availability.
- Direct Impact: High interest rates increase capital costs for capital-intensive industries (commercial real estate, utility networks), lowering valuations and slowing project deployment.
3. Sociocultural Factors
Demographic shifts, consumer attitudes, cultural movements, wealth distribution, and workforce preferences.
- Direct Impact: Aging global populations alter demand curves, increasing healthcare spending while shrinking traditional retail banking user bases.
4. Technological Factors
R&D trajectories, automation, digital infrastructure development, artificial intelligence adoption, and technological obsolescence rates.
- Direct Impact: Generative AI and automated workflows reduce operational costs for software companies while requiring elevated capital investments in high-density data infrastructure.
5. Legal Factors
Antitrust oversight, labor laws, data privacy regulations (e.g., GDPR), health and safety mandates, and intellectual property protections.
- Direct Impact: Heightened regulatory scrutiny of big tech acquisitions restricts traditional inorganic M&A strategies, forcing companies toward internal R&D investments.
6. Environmental Factors
Climate risks, carbon emission regulations, sustainable resource access, circular economy trends, and ESG reporting requirements.
- Direct Impact: Mandated corporate sustainability disclosures require heavy industrial manufacturers to invest in decarbonization technologies and shift toward sustainable power purchasing agreements (PPAs).
Comparative Integration Matrix: Porter’s Five Forces vs. PESTLE
Combining macro environmental scanning (PESTLE) with structural competitive dynamics (Porter’s Five Forces) provides a complete analytical view.
| PESTLE Factor | Affected Porter’s Force | Primary Analytical Mechanism | Corporate Strategic Response |
| Political (Tariffs & Trade Barriers) | Threat of New Entrants / Rivalry | Increases cost structures for offshore competitors, insulating domestic players | Localization of manufacturing footprints, regionalized supply chain strategy |
| Economic (Capital Costs & Inflation) | Rivalry Among Competitors | High fixed interest burdens force firms to clear inventory via price cutting | Balance sheet deleveraging, operational efficiency improvements |
| Sociocultural (Preference Shifts) | Threat of Substitutes | Shifts consumer demand toward alternative product categories | Product redesign, strategic repositioning, acquiring niche brands |
| Technological (Automation / AI) | Threat of Entrants / Power of Suppliers | Reduces entry barriers for asset-light software rivals; raises specialized tech supplier power | Strategic technology investments, vertical integration into key tech stacks |
| Legal (Antitrust Oversight) | Bargaining Power of Buyers / Rivalry | Restricts large consolidation mergers, preserving fragmented buyer alternatives | Organic innovation focus, minority venture investments over acquisitions |
| Environmental (Carbon Mandates) | Supplier Power / Cost Structures | Raises raw input costs as suppliers pass through carbon compliance costs | Circular value chain adoption, long-term sustainable supply contracts |
Integrating structural frameworks, precise peer classifications, and rigorous financial metrics enables corporate executives, strategy consultants, and equity research teams to navigate industry disruptions, capitalize on competitive vulnerabilities, and execute strategies that drive long-term economic value creation.

