In modern corporate strategy, understanding how to manage complementators has emerged as a cornerstone of platform governance, ecosystem orchestration, and long-term value creation.
Complementators—entities whose products or services increase the value of a focal company’s offerings—play a decisive role in driving user adoption, expanding market boundaries, and creating sustainable competitive advantages.
This comprehensive guide examines the economic foundations of complementarity, strategic governance frameworks, risk mitigation techniques, and real-world corporate strategies from industry leaders to equip executives, investors, and advisors with actionable insights on how to manage complementators effectively.
Introduction: The Strategic Imperative of Complementator Management
The classical view of business strategy, dominated by industrial organization economics and Porter’s Five Forces, focused heavily on zero-sum competition: negotiating down supplier power, fending off rivalry, blocking substitutes, and capturing margin from buyers. However, the rise of digital platforms, multi-sided markets, and modular product architectures has reshaped competitive dynamics. Today, enterprise value is frequently co-created within business ecosystems where independent firms generate synergistic value.
At the center of this paradigm shift is the concept of the complementator. Formally introduced into strategic management literature by Adam Brandenburger and Barry Nalebuff in their Value Net framework, a complementator is any player whose product makes your product more valuable in the eyes of customers. For instance, high-performance graphics processing units (GPUs) become substantially more valuable when paired with optimized artificial intelligence software frameworks; video game consoles require compelling game titles; and smartphones rely on a vibrant library of third-party mobile applications.
Learning how to manage complementators requires moving beyond conventional transactional procurement or vendor management. Because complementators are neither wholly controlled subsidiaries nor traditional arm’s-length suppliers, managing them demands a sophisticated blend of economic incentive alignment, technical standardization, platform governance, and delicate coopetition management. Organizations that master how to manage complementators can unleash powerful positive feedback loops, whereas those that mismanage these vital partners risk ecosystem stagnation, partner defection, or devastating regulatory antitrust intervention.
Understanding the Value Net Framework and Complementarity
To systematically analyze how to manage complementators, executives must first ground their approach in the fundamental economics of value co-creation. In the Value Net framework, business relationships exist across four nodes around a focal firm: Customers, Suppliers, Competitors, and Complementators.
                   Suppliers
                       |
                       |
Competitors <---- Focal Firm ----> Complementators
                       |
                       |
                   Customers
A complementator relationship is mathematically characterized by joint utility: two products 


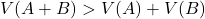

This positive synergy creates mutual dependence. When a complementator lowers its price, improves its product quality, or expands its feature set, the demand curve for the focal product shifts outward. Conversely, if a complementator raises prices, reduces reliability, or exits the market, the value of the focal firm’s product deteriorates. Consequently, learning how to manage complementators is ultimately about orchestrating external innovation and capital to expand the total pool of economic value before negotiating how that value is divided.
Core Pillars of Effective Complementator Governance
Successfully governing a network of independent complements requires explicit structural choices. Executives must balance encouraging third-party innovation with protecting platform integrity and capturing equitable financial returns. The strategic orchestration of complementators rests upon three core pillars.
1. Alignment of Incentives and Economic Models
The financial architecture of an ecosystem dictates the health and commitment of its complementators. If a focal platform extracts excess economic rent, complementators will underinvest, migrate to rival platforms, or launch regulatory challenges. Conversely, if the platform captures too little value, it cannot sustain infrastructure investments, security enforcement, or research and development.
Effective incentive alignment relies on tailored monetization structures, including:
- Revenue-Sharing Models: Platform owners collect a percentage commission on digital transactions or subscription fees generated by complementators.
- Tiered Licensing and API Access Fees: Complementators pay flat, usage-based, or performance-contingent access fees to interface with the primary system.
- Royalty and Subsidization Schemes: Platform sponsors actively subsidize strategic complementators during early-stage platform launches to overcome the “chicken-and-egg” network effect problem.
A prime global example of economic orchestration is Apple. Within its iOS platform, third-party app developers serve as essential complementators. According to independent economic analysis published by Analysis Group, the global App Store ecosystem facilitated over USD1.4 trillion in total developer billings and sales in 2025 alone. Concurrently, Apple‘s financial filings show that its proprietary Services division generated more than USD109 billion in fiscal year 2025 revenue, driven heavily by App Store commissions, digital subscriptions, and payment processing. By calibrating commission structures—such as reducing platform fees from 30% to 15% for small business developers earning under USD1 million annually—Apple preserved developer incentives while maintaining one of the most profitable service margins in corporate history.
2. Openness versus Control: Architectural and Strategic Trade-Offs
A central question in determining how to manage complementators is selecting the appropriate degree of platform openness. Platform sponsors face a direct trade-off between open governance (which maximizes complementator entry and architectural variety) and tight control (which ensures end-user quality, cybersecurity, and predictable brand experience).
| Dimension | Open Complementator Model | Closed / Governed Complementator Model |
| Primary Objective | Rapid ecosystem growth & broad innovation | Superior user experience, quality control & security |
| Barrier to Entry | Low; standardized public APIs and self-service SDKs | High; rigorous vetting, certification, and licensing |
| Ecosystem Diversity | High volume of niche tools and experimental applications | Curated catalog of high-grade, enterprise-ready solutions |
| Platform Monetization | Indirect (hardware sales, data monetisation, cloud usage) | Direct (commission fees, platform access charges, royalties) |
| Key Strategic Risk | Malware, fragmentation, and user experience degradation | Slow ecosystem adoption, partner discontent, and high friction |
Enterprise software titan Microsoft exemplifies a highly effective hybrid approach. Through its Intelligent Cloud and Productivity segments—which powered total corporate revenue growth of 15% to clear USD245 billion in fiscal year 2025—Microsoft maintains an open ecosystem for third-party software vendors (ISVs) building on Microsoft Azure and Microsoft 365, while enforcing stringent security, identity, and compliance standards via its Cloud Partner Program. By delivering robust Software Development Kits (SDKs) alongside strict enterprise governance, Microsoft encourages millions of global developers to build specialized tools that directly amplify Azure cloud consumption.
3. Navigating Coopetition and Platform Encroachment
The dynamic between platform owners and complementators is inherently coopetitive—simultaneously cooperative and competitive. A major structural point of friction occurs when a platform owner engages in “platform encroachment” (often colloquially termed “sherlocking”), absorbing a complementator’s feature set directly into the core operating system or base product.
While platform encroachment can enhance native user convenience, executing it aggressively creates severe trust deficits across the partner network. If complementators perceive that building a successful complement will result in the platform owner copying their intellectual property and expropriating their market, high-value developers will divert innovation to competing ecosystems.
To manage coopetition responsibly, leading platform orchestrators establish transparent boundary rules:
- Roadmap Transparency: Providing advanced notice of core platform feature additions so complementators can pivot up-market toward more complex, differentiated capabilities.
- Strict Boundary Rules: Establishing clear domain limits defining what the core platform will supply versus what will remain reserved for partner solutions.
- Safe Harbor Designations: Offering official certification or strategic co-selling status to key complementators, protecting their enterprise valuation while scaling global go-to-market motions.
A notable illustration of deliberate coopetition governance is observed in enterprise software leader Salesforce. Through its AppExchange marketplace, Salesforce enables thousands of independent software vendors to create industry-specific tools. Rather than absorbing successful partner applications, Salesforce frequently co-invests in key complementators through Salesforce Ventures, converting potential competitive friction into capital appreciation and ecosystem alignment.
Strategic Frameworks for Complementator Lifecycle Management
Knowing how to manage complementators requires applying customized governance models across every stage of the partner lifecycle. The optimal strategy evolves as the platform matures from an emerging standard to a dominant market infrastructure.
Phase 1: Attraction and Onboarding (Seeding the Ecosystem)
In the early lifecycle stage, a platform lacks critical mass. Because customers will not purchase the core platform without valuable complements, and complementators will not invest in developing complements without an established user base, the focal firm must actively seed the ecosystem.
- Subsidies and Developer Grants: Providing financial incentives, free cloud infrastructure, or direct co-development resources to high-profile complementators (“anchor complementators”).
- Provision of Software Development Toolkits: Offering intuitive APIs, robust technical documentation, and sandbox testing environments to minimize third-party development costs.
- Strategic Anchor Partnerships: Securing exclusive or early-window launch commitments from prominent industry complementators to validate the platform’s market viability.
Phase 2: Scaling and Nurturing (Strengthening Network Effects)
Once two-sided network effects take hold, the management focus shifts from direct recruitment to ecosystem orchestration, standard setting, and cross-promotional alignment.
- Joint Go-To-Market (GTM) Programs: Structuring revenue-sharing incentives for internal direct sales teams to sell partner complement applications alongside core platform products.
- Ecosystem Certification and Marketplaces: Creating centralized digital storefronts that lower discovery and transaction costs for end buyers while validating partner quality.
- Technical Interoperability Standards: Regularly updating architectural frameworks to ensure complement stability across product updates.
A dramatic execution of ecosystem scaling is demonstrated by AI semiconductor pioneer NVIDIA. Beyond its advanced GPU architectures, NVIDIA‘s explosive growth—reaching USD130.5 billion in fiscal year 2025 revenue and expanding further to USD215.9 billion in fiscal year 2026—is fundamentally underpinned by its CUDA software ecosystem. By providing researchers, software developers, and cloud hyperscalers with free libraries, deep learning frameworks, and optimized software compilers, NVIDIA cultivated a global network of software complementators. Because millions of AI models and applications are written specifically to run on CUDA libraries, switching costs away from NVIDIA hardware remain exceptionally high, demonstrating how software complements can create a formidable moat around physical hardware assets.
Phase 3: Governance, Compliance, and Dispute Resolution
As an ecosystem achieves market dominance, managing complementators increasingly involves policy enforcement, anti-siphoning monitoring, data access control, and regulatory compliance.
- Data Access and Privacy Policies: Defining clear rules regarding what user interaction data complementators may collect, retain, or monetize.
- Anti-Siphoning and Disintermediation Controls: Preventing complementators from steering platform customers off-platform to bypass transaction fees.
- Antitrust and Regulatory Alignment: Proactively auditing platform policies to ensure compliance with emerging global regulations, such as the European Union’s Digital Markets Act (DMA), which penalizes self-preferencing and restrictive tying practices.
Comparative Analysis of Global Complementator Management Strategies
The following table evaluates how leading multinational enterprises across diverse technology and industrial sectors structure, govern, and monetize their complementator networks:
| Enterprise / Platform | Primary Complementator Network | Ecosystem Governance Model | Key Monetization & Incentive Engine | Primary Strategic Risk |
| Apple (iOS / App Store) | Mobile app developers, accessory manufacturers, streaming content providers | Closed, highly curated platform with centralized security review | 15%–30% commission on digital goods; facilitated USD1.4 trillion ecosystem sales in 2025 | Regulatory antitrust challenges regarding platform monopoly and sideloading mandates |
| Microsoft (Azure & Windows) | Enterprise ISVs, system integrators, cybersecurity partners | Hybrid open ecosystem with standardized enterprise certification | Usage-based cloud infrastructure consumption and joint GTM marketplace rev-shares | Managing channel conflict between direct first-party solutions and partner tools |
| NVIDIA (CUDA / AI Infrastructure) | AI labs, software developers, cloud service providers | Open software libraries combined with proprietary hardware integration | Premium GPU hardware pricing enabled by lock-in to free software complement ecosystem | Hyperscaler custom silicon development aiming to bypass CUDA dependencies |
| Sony (PlayStation Interactive) | AAA game publishers, indie game developers, gaming headset manufacturers | Controlled console licensing with strict quality assurance testing | Software publisher royalty fees, platform subscription cuts, and dev kit licensing | High developer costs causing complementators to release multi-platform titles simultaneously |
| ASML (EUV Lithography Systems) | Optical component specialists (Carl Zeiss), specialized chemical suppliers, fab leaders (TSMC) | Highly integrated industrial joint-development partnership network | Multi-billion-dollar long-term joint R&D funding and co-equity stakes | Extreme supply chain dependency on sole-source high-tech complementators |
Risks, Pitfalls, and Mitigation Strategies in Complementator Relations
While complementators drive substantial network effects, mismanaging these relationships introduces serious strategic vulnerabilities. Executive teams must implement proactive mitigation strategies for three primary risk categories.
1. Complementator Holdup and Holdout Strategies
A holdup scenario occurs when a single, highly dominant complementator achieves sufficient market power to demand unfavorable commercial terms, redirect revenue away from the platform owner, or threaten platform defection. In video gaming, for example, popular game titles can dictate royalty concessions to console platforms because their presence directly drives hardware adoption.
Mitigation Strategy: Platform owners must prevent single-source complementator lock-in by fostering a diverse, fragmented network of alternatives. Where dominant complementators exist, platform owners should construct long-term multi-year joint venture agreements, cross-licensing arrangements, or strategic equity investments to lock in mutual commitments.
2. Platform Fragmentation and Quality Degradation
When platform entry barriers are excessively low, an influx of low-quality, buggy, or fraudulent third-party complements can impair overall brand perception. Customers rarely distinguish between a core platform defect and a failure caused by a poor third-party complement, holding the platform owner accountable for the degraded user experience.
Mitigation Strategy: Implement automated code-scanning tools, strict developer identity verification, transparent consumer rating/review mechanisms, and rapid revocation policies for non-compliant complements. Establishing clear technical performance benchmarks ensures ecosystem quality without imposing prohibitive onboarding friction.
3. Antitrust, Regulatory, and Ecosystem Backlash Risks
As platforms expand into multi-trillion-dollar digital infrastructures, regulatory authorities globally scrutinize how dominant orchestrators treat complementators. Practices such as self-preferencing (ranking first-party apps higher than third-party complements), restrictive payment gateway requirements, and asymmetric data access face increasing legal exposure under competition laws.
Mitigation Strategy: Establish an internal Ecosystem Ethics and Fair Governance Board. Conduct regular third-party compliance audits to evaluate whether platform policy changes unfairly squeeze complementator margins, restrict interoperability, or create illegal tying arrangements. Building fair, predictable, and transparent operational terms shields the enterprise from regulatory fines and mandated structural breakups.
Best Practices for Executives: Actionable Guidelines on How To Manage Complementators
For C-suite executives, board members, and business unit leaders responsible for designing or executing ecosystem strategies, the following actionable guidelines provide a roadmap on how to manage complementators for long-term enterprise value:
- Map the Total Value Net Periodically: Conduct formal annual audits to identify emerging complementators across adjacent industries. Map how shifting customer preferences or technological breakthroughs alter the relative power between your core product and key complements.
- Decouple Value Creation from Value Capture: Focus initial ecosystem efforts entirely on expanding total co-created value (growing the overall pie). Avoid aggressive margin extraction during early growth phases; premature rent-seeking destroys partner trust before critical network effects solidify.
- Maintain Modular Architectural Interfaces: Design hardware, software, and operational interfaces using standardized, publicly documented specifications. Modular architectures lower third-party integration costs and allow complementators to innovate independently without breaking core system functionality.
- Implement Dual Performance Metrics: Measure ecosystem health using partner-centric key performance indicators alongside traditional financial metrics. Track complementator net promoter score (NPS), developer return on investment (ROI), partner churn rates, and average complements per active user.
- Establish Clear Encroachment Policies: Formulate explicit, internal policy guidelines governing when and how the enterprise may develop internal offerings that overlap with third-party partner features. Provide complementary partners with clear migration paths and early advisory notices.
- Build Multi-Homing Moats Through Superior Developer Utility: Recognize that complementators often “multi-home”—building products for multiple competing platforms simultaneously. Win complementator loyalty by providing superior technical tools, superior sales distribution channels, faster payout cycles, and unmatched developer support.
Conclusion: Building Sustainable Competitive Advantage Through Ecosystem Co-Evolution
In an increasingly interconnected global economy, competitive advantage is rarely built in isolation. Individual firm capabilities are increasingly secondary to the overall strength, dynamism, and alignment of the ecosystem in which the firm operates. Understanding how to manage complementators represents a transition from transactional management to strategic ecosystem leadership.
By establishing transparent governance structures, fair economic alignment models, robust technical interfaces, and proactive risk management protocols, forward-thinking enterprises can transform independent complementators into an energized force multiplier for corporate growth. As demonstrated by global market leaders across technology, semiconductor, and industrial sectors, firms that excel at managing complementators do not merely compete within established markets—they shape entire industry architectures, secure enduring market leadership, and continuously co-create superior value for customers and shareholders alike.

