Evaluating quality of financial reports is a vital competency for corporate leaders, equity analysts, investors, and regulators who seek to ascertain the true underlying economic reality of a commercial enterprise.
High-quality financial reports provide clear, reliable, and transparent information that accurately reflects a company’s financial position, operating results, and cash flows.
Conversely, low-quality reports obscure economic performance through aggressive accounting choices, intentional earnings management, or outright misstatement.
Understanding how to systematically dissect financial statements allows decision-makers to assess sustainable competitive advantages, identify solvency risks, and determine the intrinsic value of corporate enterprises.
Conceptual Framework for Evaluating Quality of Financial Reports
To rigorously evaluate the financial health of an enterprise, analysts must distinguish between financial reporting quality and earnings quality. While these two dimensions are interrelated, they address distinct aspects of corporate reporting:
- Financial Reporting Quality pertains to the clarity, completeness, and adherence to relevant accounting standards (such as GAAP or IFRS) with which a company presents its economic activities. High financial reporting quality provides decision-useful, transparent, and unbiased information.
- Earnings Quality (often extended to include cash flow and balance sheet quality) pertains to the underlying economic performance of the business. High earnings quality implies that reported profits are sustainable, persistent, backed by actual cash inflows, and derived from core operational activities rather than temporary accounting adjustments or non-recurring events.
Evaluating quality of financial reports requires viewing financial statement presentation along a continuous spectrum ranging from high-quality operational disclosures down to fraudulent misrepresentation.
The Spectrum of Financial Reporting Quality
| Quality Tier | Financial Reporting Quality | Earnings Quality | Operational Characteristics |
| Tier 1: High Quality | GAAP/IFRS compliant, decision-useful, transparent disclosures | High sustainability, high return on capital, strong cash backing | True, unbiased representation of economic operations. |
| Tier 2: Intermediate Quality | GAAP/IFRS compliant, decision-useful disclosures | Low sustainability, low earnings persistence | Honest reporting, but the core business faces structural or cyclical headwinds. |
| Tier 3: Within-GAAP Biased | Compliant with standards, but relies on aggressive or conservative choices | Earnings shifted across periods | Management uses accounting discretion to smooth earnings or meet targets. |
| Tier 4: Earnings Management | Technically within GAAP, but distorts underlying economics | Artificially inflated or smoothed earnings | Real activity management (e.g., cutting R&D) or aggressive discretionary accruals. |
| Tier 5: Non-Compliant | Departs from accounting standards (Non-GAAP violations) | Unreliable and misstated metrics | Inappropriate revenue recognition or deferral of current operating expenses. |
| Tier 6: Fraudulent | Fabricated records and deceptive disclosures | Unbacked by genuine business transactions | Intentional falsification of accounts to deceive investors and creditors. |
Potential Problems Affecting Financial Reporting Quality
Multiple operational pressures and structural incentives can compromise financial reporting quality. When corporate managers face aggressive market expectations, debt covenant constraints, or executive compensation tied directly to short-term earnings per share (EPS), they may adopt accounting treatments that obscure true performance.
Aggressive Revenue Recognition
Revenue recognition is the most common area for financial reporting distortion. Companies seeking to accelerate top-line growth may engage in practices such as:
- Channel Stuffing: Shipping excessive product inventory down distribution channels before end-customer demand exists, recognizing revenue prematurely.
- Bill-and-Hold Transactions: Booking sales for goods that remain in the seller’s warehouse without meeting stringent criteria for control transfer.
- Fabricated Transactions: In extreme corporate frauds, such as Luckin Coffee, management inflated 2019 net revenue by USD328 million through fake voucher sales and related-party shell entities.
Inappropriate Expense Recognition and Capitalization
Distorting expense timing artificially inflates current operating margins. Key techniques include:
- Capitalizing Operating Costs: Classifying routine operational expenditures as capital expenditures (CapEx) to spread costs over multi-year depreciation schedules rather than expensing them immediately.
- Stretching Asset Depreciation Lives: Lengthening the assumed useful life of physical assets to artificially lower annual depreciation charges.
- Delayed Impairments: Failing to write down impaired long-term assets or goodwill promptly when economic underlying cash flows deteriorate.
Off-Balance-Sheet Arrangements and Classification Manipulation
Management may hide liabilities or manipulate key margins by shifting items across financial statement line items:
- Off-Balance-Sheet Entities: Utilizing special purpose entities (SPEs) or variable interest entities (VIEs) to keep debt and underperforming assets off the consolidated balance sheet.
- Classification Shifting: Moving operating expenses into non-operating sections or reclassifying recurring expenses as “one-time restructuring charges” to present an artificially clean core operating margin.
Methodology for Evaluating Quality of Financial Reports
A systematic approach ensures that analysts evaluate reporting quality objectively without overlooking subtle disclosures in footnotes or supplementary filings.
Step 1: Understand Industry Dynamics & Business Model
   │
Step 2: Evaluate Management Incentives & Accounting Policies
   │
Step 3: Compare Reported Earnings to Operating Cash Flows
   │
Step 4: Audit Footnotes, Related-Party Transactions & Disclosures
   │
Step 5: Perform Ratio Analysis & Check for Accrual Anomalies
Step 1: Contextualize Business Model and Accounting Choices
Analyze the company’s operating environment, competitive positioning, and revenue drivers. Identify critical accounting estimates where management exercises significant subjective judgment (e.g., revenue recognition for long-term contracts, inventory valuation reserves, bad debt provisions, and goodwill impairment assumptions).
Step 2: Assess Management Incentives
Examine executive compensation structures, debt covenant thresholds, and historical earnings guidance patterns. High executive option packages tied to quarterly EPS thresholds increase the risk of earnings smoothing and aggressive accounting choice.
Step 3: Compare Earnings Mechanics to Cash Generation
Cross-examine net income with cash generated from operating activities over multi-year periods. A persistent divergence where net income grows while operating cash flow stagnates or declines is a primary warning signal of aggressive accrual accounting.
Step 4: Examine Footnotes and Audit Opinions
Review the Notes to Financial Statements for changes in accounting policies, estimates, or accounting principles. Pay close attention to Key Audit Matters (KAMs) highlighted in the Independent Auditor’s Report, as well as transactions involving related parties.
Step 5: Perform Anomaly and Ratio Testing
Utilize standardized quantitative tests, such as the Beneish M-Score (to detect earnings manipulation probability) or detailed asset turn and working capital ratio comparisons against industry peers.
Indicators and Mechanics of Earnings Quality
Defining Sustainable (Persistent) Earnings
Sustainable earnings (or persistent earnings) refer to the proportion of reported net income expected to recur naturally in future periods. High-quality earnings stem from core operational competitive advantages rather than non-operating investment gains, tax rate fluctuations, currency swings, or one-off asset sales.
When evaluating earnings quality, analysts must strip away non-recurring components to compute normalized core earnings:
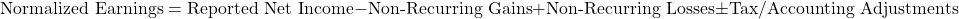
Mean Reversion in Earnings and the Role of Accruals
A fundamental phenomenon in corporate finance is mean reversion: extraordinarily high or extraordinarily low earnings tend to revert toward the long-term industry average over time. High competition erodes excessive profits, while capital reallocation eventually improves depressed returns.
However, the speed of mean reversion depends heavily on whether earnings are driven by cash flows or accruals. Total net income can be decomposed into two distinct components:
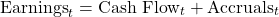
Where accruals represent non-cash adjustments such as changes in accounts receivable, inventory, accounts payable, and accrued liabilities:
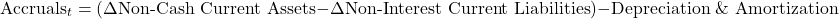
Empirical research shows that the accruals component of earnings reverts to the mean significantly faster than the cash flow component. This occurs because accruals involve subjective management estimates and timing differences that naturally reverse in subsequent accounting periods.
Mathematically, in an earnings persistence regression model:
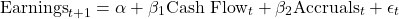
Where empirical evidence demonstrates that  . Consequently, companies whose earnings are dominated by high discretionary accruals experience a rapid decay in earnings persistence, leading to sudden mean reversion in profitability.
Indicators of High vs. Low Earnings Quality
| Evaluation Dimension | High Earnings Quality | Low Earnings Quality |
| Cash Conversion | Operating cash flow exceeds net income consistently | Operating cash flow lags net income persistently |
| Accrual Level | Low net operating accruals relative to assets | High discretionary accruals and growing receivables |
| Revenue Sources | Core, organic product/service demand with predictable volumes | Aggressive channel expansion or customer financing |
| Margin Drivers | Pricing power and sustainable cost structures | One-off cost cuts, asset sales, or pension adjustments |
| Reporting Volatility | Smooth operating performance aligned with economic cycles | Extreme earnings surprises with frequent “one-time” charges |
Indicators and Assessment of Balance Sheet Quality
Evaluating quality of financial reports requires an in-depth examination of balance sheet integrity. High balance sheet quality means that reported assets accurately reflect future economic benefits, liabilities fully encompass all present obligations, and financial leverage is conservative and manageable.
Key Indicators of Balance Sheet Quality
- Conservative Asset Valuation: High proportion of liquid assets (cash, marketable securities) and tangible productive assets relative to unidentifiable intangible assets or goodwill resulting from overpriced acquisitions.
- Adequate Allowance Reserves: Realistic provisions for uncollectible trade receivables and inventory obsolescence.
- Complete Liability Recognition: Explicit recognition of pension obligations, environmental remediation costs, warranty claims, and lease liabilities.
- Low Off-Balance-Sheet Exposure: Absence of hidden obligations through variable interest entities, guarantees, or synthetic leases.
Evaluating Solvency and Financial Flexibility
A balance sheet with strong solvency features manageable financial debt, long maturity profiles, and minimal debt covenant constraints. Analysts evaluate leverage using debt-to-equity, debt-to-EBITDA, and interest coverage metrics to confirm that asset values comfortably cover outstanding claims under stress scenarios.
Indicators and Assessment of Cash Flow Quality
Because cash flow statements are inherently less vulnerable to discretionary accrual accounting than the income statement, evaluating cash flow quality serves as a crucial line of defense when assessing reporting integrity.
Indicators of High Cash Flow Quality
- High Cash Flow to Earnings Ratio: A steady operating cash flow to net income ratio comfortably above 1.0 indicates that net profits are realized in liquid cash.
- Organic Cash Generation: Operating activities consistently generate sufficient cash to cover capital expenditures (CapEx) and operational working capital needs without continuous external debt or equity financing.
- Low Volatility in Operating Cash Flow: Steady cash generation profiles that align with corporate operational cycles rather than erratic year-end collection surges.
Red Flags in Cash Flow Statements
- Classification Manipulation: Inappropriate shifting of operational outflows into investing or financing cash flow sections (e.g., misclassifying vendor financing payables to inflate operating cash flow).
- Capitalizing Operating Cash Outflows: Expensing items on the cash flow statement under investing activities (as CapEx) rather than operating activities.
- Sale of Accounts Receivable: Utilizing factoring agreements or securitizations to sell trade receivables at year-end, temporarily boosting operating cash flow at the expense of future periods.
Corporate Case Studies: Real-World Evaluation of Reporting Quality
Applying these analytical principles to real corporate figures demonstrates how financial reporting quality and earnings quality interact in practice.
Case 1: High Reporting and Earnings Quality — Apple Inc.
An examination of Apple Inc.‘s consolidated financial statements for fiscal year 2025 demonstrates exceptional financial reporting and earnings quality.
| Financial Metric (FY2025) | Reported Value (USD) | Analytical Significance |
| Total Net Sales | USD416.16 billion | Solid top-line growth driven by Services and iPhone sales. |
| Net Income | USD112.01 billion | Strong bottom-line profitability with high gross margins (46.9%). |
| Operating Cash Flow | USD118.26 billion | High cash conversion; OCF exceeds Net Income by USD6.25 billion. |
| Services Revenue | USD109.16 billion | Predictable, high-margin, recurring subscription revenues. |
| Cash & Marketable Securities | USD54.70 billion | Exceptional liquidity and balance sheet conservatism. |
Apple‘s cash flow quality is reinforced by an Operating Cash Flow to Net Income ratio of 1.06, confirming that net profits translate directly into liquid cash flow. Furthermore, its growing Services business provides highly persistent, recurring revenue streams that reduce overall earnings volatility and lower susceptibility to rapid mean reversion.
Case 2: Financial Reporting Complexity and Earnings Distortions — The Boeing Company
Evaluating the quality of financial reports for The Boeing Company in fiscal year 2025 highlights the importance of separating GAAP accounting net income from core operational earnings quality.
| Financial Metric (FY2025) | Reported Value (USD) | Analytical Significance |
| Total Revenues | USD89.46 billion | Substantial top-line recovery up 34% from USD66.52 billion in 2024. |
| GAAP Operating Profit | USD4.28 billion | Swung positive from a GAAP operating loss of USD10.71 billion in 2024. |
| GAAP Net Income | USD2.24 billion | Reported net profit compared to an USD11.83 billion net loss in 2024. |
| One-Time Gain on Business Sale | USD9.60 billion | Non-recurring pre-tax gain from Digital Aviation Solutions sale. |
| Commercial Airplanes Op. Loss | -USD7.08 billion | Deep underlying operating losses in core manufacturing segment. |
| Operating Cash Flow | USD1.07 billion | Turned positive from -USD12.08 billion in 2024. |
| Free Cash Flow (Non-GAAP) | -USD1.88 billion | Remained negative after USD2.94 billion in required CapEx. |
A surface-level review of Boeing‘s FY2025 numbers shows a positive GAAP net income of USD2.24 billion, suggesting a swift operational turnaround. However, a detailed analysis of reporting quality reveals that this net income was heavily driven by a non-recurring pre-tax gain of USD9.60 billion resulting from the divestiture of its Digital Aviation Solutions business within Global Services.
Excluding this non-operating transaction, Boeing‘s primary core segment—Commercial Airplanes—recorded an operating loss of USD7.08 billion with an operating margin of -17.1%. Furthermore, while operating cash flow improved to USD1.07 billion, free cash flow remained negative at -USD1.88 billion due to necessary capital expenditures. This divergence illustrates low earnings persistence: the reported GAAP net profit was driven by asset sales rather than sustainable core manufacturing operations.
Key Sources of Risk Information for Financial Analysis
To evaluate reporting quality thoroughly, analysts must consult multiple qualitative and quantitative sources of risk disclosures embedded across statutory filings:
- Management’s Discussion and Analysis (MD&A): Provides management’s perspective on operating results, liquidity trends, capital resources, and critical accounting policies. Analysts look for abrupt changes in tone, altered key performance indicators (KPIs), or unaddressed operational risks.
- Notes to Financial Statements: Discloses specific details on contingent liabilities, legal exposure, fair value measurements, debt covenant terms, tax disputes, and related-party transactions.
- Auditor’s Report and Key Audit Matters (KAMs): Outlines areas involving high estimation uncertainty or complex accounting judgment identified by independent external auditors.
- Risk Factors (SEC Form 10-K, Item 1A): Itemizes key macro, industry, legal, regulatory, and operational threats that could materially impact future financial performance.
- Proxy Statements (Form DEF 14A): Reveals executive compensation metrics, performance benchmarks, board governance oversight, and insider transaction details.
- Credit Rating Agency Reports & Debt Covenants: Provides external assessments of solvency, liquidity buffers, capital structure sustainability, and default probability from agencies such as Moody’s, S&P, and Fitch.
Integrating Financial Quality Assessment into Corporate Decision-Making
Evaluating quality of financial reports is not a static compliance exercise, but a strategic imperative for corporate leadership, equity investors, and financial advisors. By applying a conceptual framework that evaluates financial reporting quality alongside earnings, balance sheet, and cash flow quality, decision-makers can look past GAAP accounting choices to see the true underlying performance of an enterprise.
Understanding the mechanics of accrual adjustments, recognizing the fast mean reversion of non-cash earnings, and verifying profits against organic operating cash flows equips analysts to spot accounting red flags early. Ultimately, grounding corporate strategy and capital allocation in high-quality, transparent financial evaluations protects capital, ensures accurate company valuations, and promotes sustainable long-term value creation.
