Equity valuation is the foundation of investment management, corporate finance, and financial analysis. Determining the economic worth of an ownership stake allows investors, portfolio managers, and corporate strategists to make rational capital allocation decisions.
Below is an exhaustive business article examining the fundamental components of equity valuation, valuation processes, and model selection.
Introduction to Equity Valuation and Valuation Concepts
Valuation is the process of estimating the economic value of an asset or a company based on variables related to expected future investment returns, comparative asset pricing, or immediate liquidation proceeds. At the core of fundamental analysis is intrinsic value, which represents the actual, true economic value of a security given an evaluation of all underlying company fundamentals, including earnings, cash flows, growth potential, risk profile, and asset quality.
Unlike intrinsic value, market price represents the current consensus price at which buyers and sellers transact in an open market. In an efficient market, market prices closely track intrinsic values. However, real-world markets frequently experience discrepancies. Perceived mispricing occurs when an analyst’s estimated intrinsic value ( ) differs from the prevailing market price (
 ).
The total difference between an estimated value and the market price can be expressed as:
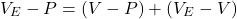
Where:
- = Estimated value by the analyst
- = Market price
 = True intrinsic value
This equation highlights two primary sources of perceived mispricing:
- True Mispricing
 : The market price diverges from the actual intrinsic value because market participants have incomplete information, misinterpret data, or exhibit behavioral biases.
- Estimation Error
 : The analyst’s estimate is flawed due to inaccurate forecasting, inappropriate model selection, or faulty inputs. Investment success relies heavily on minimizing estimation error while correctly identifying true mispricing.
Going Concern Assumption Versus Liquidation Value
A critical premise in financial modeling is the going concern assumption, which presumes that a business will continue its operations for the foreseeable future, retaining its assets to generate cash flows rather than being forced into a sudden shutdown. Under this assumption, a company’s going concern value captures the present value of future cash flows generated by operating the enterprise.
Conversely, liquidation value measures the net amount that would be realized if a company were dissolved today and its assets were sold individually, net of liabilities and liquidation expenses. Liquidation value is typically utilized when a company faces severe financial distress, insolvency, or bankruptcy, where asset-stripping or orderly asset sales yield more value to stakeholders than continued operations.
Definitions of Value and Public Company Relevance
Valuation assignments require precise definitions of value because different contexts alter the ultimate valuation outcome:
- Intrinsic Value: The economic value of an asset based on fundamental characteristics.
- Fair Market Value: The price at which an asset or business would change hands between a willing buyer and a willing seller, neither being under compulsion to buy or sell, and both having reasonable knowledge of relevant facts.
- Investment Value: The value of an asset to a specific, identifiable investor or buyer, taking into account their unique operational synergies, tax status, or strategic goals.
- Fair Value (Financial Reporting): The price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date under current market conditions.
For public company valuation, intrinsic value combined with fair market value is the most relevant definition. Public equity markets provide a continuous liquid platform where stocks trade at fair market values. Professional equity analysts attempt to estimate intrinsic value to determine whether public market prices misprice the company, driving buy, sell, or hold recommendations.
Applications of Equity Valuation
Equity valuation extends far beyond simple stock selection. Major practical applications include:
- Stock Selection and Portfolio Management: Active portfolio managers use valuation models to identify undervalued or overvalued securities to outperform a benchmark.
- Inferring Market Expectations: Analysts reverse-engineer market prices using valuation models to understand what earnings growth, margins, or risk premiums the market has already priced into a stock.
- Corporate Finance and Strategic Decisions: Corporate executives assess whether potential mergers, acquisitions, capital investments, or divestitures will create value for shareholders.
- Fairness Opinions: Investment banks provide formal fairness opinions on the financial terms of a corporate merger, buyout, or restructuring.
- Regulatory and Legal Appraisals: Valuations are required for estate and gift taxation, dissenting shareholder lawsuits, and financial reporting impairment tests.
To ground these applications, global enterprises frequently utilize valuation strategies. For instance, technology leaders like Apple engage in continuous equity valuation and capital allocation strategies—such as massive share repurchase programs—to optimize shareholder returns and align market prices with intrinsic worth. Similarly, multinational conglomerates like General Electric utilize valuation techniques to determine the efficacy of major business spin-offs and restructuring events.
Conducting Industry and Competitive Analysis
Before building quantitative forecasts, an analyst must understand the business environment through a structured framework. Effective industry and competitive analysis addresses several vital questions:
| Analytical Dimension | Core Questions Addressed |
| Industry Growth and Profitability | What are the historical growth rates, cyclicality, and profit margins of the industry? Is the industry growing faster or slower than the broader economy? |
| Industry Structure (Porter’s Five Forces) | How intense is rivalry among existing competitors? What is the threat of new entrants, the threat of substitute products, and the bargaining power of buyers and suppliers? |
| External Macro Influences (PESTLE) | How do political, economic, social, technological, legal, and environmental factors impact the industry’s long-term outlook? |
| Competitive Strategy and Positioning | Does the company compete on cost leadership, differentiation, or a niche focus? How well does the company execute its chosen strategy relative to peers? |
| Quality of Earnings and Financial Integrity | Are the company’s reported earnings backed by strong operating cash flows? Do aggressive accounting policies distort fundamental profitability? |
1. Absolute Versus Relative Valuation Models
Equity valuation models are broadly divided into absolute and relative frameworks:
A. Absolute Valuation Models (Present Value Models)
Absolute models estimate the intrinsic value of a security by calculating the present value of its expected future cash flows. The value is independent of current market prices for peer companies.
- Dividend Discount Models (DDM): Values a stock based on the present value of its expected future cash dividends. The Gordon Growth Model is a classic single-stage DDM variant.
- Free Cash Flow Models (FCF): Values a company based on free cash flow to the firm (FCFF) or free cash flow to equity (FCFE) discounted at the appropriate cost of capital.
- Residual Income Models: Values equity as the current book value of equity plus the present value of expected future residual income (net income minus a capital charge).
B. Relative Valuation Models (Market-Based Models)
Relative models determine the value of an asset by comparing its pricing multiples to those of similar peer companies or historical benchmarks.
- Price Multiples: Metrics such as Price-to-Earnings (P/E), Price-to-Book Value (P/B), Price-to-Sales (P/S), and Price-to-Cash Flow (P/CF).
- Enterprise Value Multiples: Metrics such as Enterprise Value-to-EBITDA (EV/EBITDA) or EV-to-Sales, which account for both debt and equity capital structures.
Global corporations frequently experience valuation shifts based on these models. For example, retail giants like Walmart are often evaluated using relative P/E and EV/EBITDA multiples against competitors like Target Corporation to spot relative mispricings.
2. Sum-of-the-Parts Valuation and Conglomerate Discounts
When a company operates multiple distinct business segments across different industries, applying a single valuation model to the consolidated entity can be misleading. Analysts use Sum-of-the-Parts (SOTP) valuation—also known as breakup value valuation—to value each business segment independently using peer multiples or DCF models tailored to that specific industry, then sum the values together (minus net corporate debt and liabilities) to find total equity value.
Conglomerates often trade at a conglomerate discount—a phenomenon where the market values a multi-segment company at an aggregate price lower than the sum of its individual business units. Sources of conglomerate discounts include:
- Inefficient internal capital allocation.
- Lack of operational transparency and complex financial reporting.
- Investor preference for pure-play investments where they can manage their own asset allocation.
- Higher agency costs and poor corporate governance.
Broad Criteria for Choosing an Appropriate Valuation Approach
Selecting the correct valuation approach depends on three core criteria:
- Characteristics of the Company: For example, dividend discount models work well for mature, stable dividend-paying firms like utility providers, whereas free cash flow models are superior for firms with high growth and zero dividends. Asset-based models are ideal for natural resource companies or holding firms.
- Availability and Quality of Data: If reliable financial forecasts cannot be generated due to extreme business uncertainty, relative valuation multiples based on current peer transactions are often more practical than complex absolute cash flow models.
- Purpose of the Valuation and Analyst Perspective: If an analyst is issuing an opinion on a minority stake in a public company, standard public market multiples or absolute DCF models are appropriate. If the valuation is for a private buyout or controlling acquisition, investment value incorporating control premiums and synergies must be used.
By mastering these applications, processes, and quantitative models, analysts bridge the gap between financial statement analysis and actionable investment decisions.
