Discounted Cash Flow and Growth Models form the foundational architecture of fundamental equity analysis, enabling institutional investors, financial analysts, and corporate leaders to determine the intrinsic value of a business.
This comprehensive guide explores the structural inputs of dividend discount, free cash flow to equity, free cash flow to the firm, and residual income models, outlines the systematic valuation process, demonstrates single-stage and multistage calculations, critiques the inherent assumptions of these models, and examines the mechanics of valuing preferred equity alongside its embedded contingency features.
Introduction to Equity Valuation and Present Value Models
Equity valuation bridges corporate finance and investment management. Determining what an equity security is truly worth requires looking beyond current market prices to project the economic benefits that a corporation will generate over its operating lifecycle. Present value models anchor on the core financial principle that the intrinsic value of any financial asset equals the present value of its expected future cash inflows, discounted at a rate that appropriately reflects the risk associated with those cash flows.
Prominent organizations like Apple, Microsoft, and JPMorgan Chase rely on rigorous analytical frameworks to guide strategic capital allocation, mergers and acquisitions, and portfolio construction. By utilizing present value models, analysts translate forecasts of earnings, dividends, and cash flows into actionable intrinsic values that indicate whether a security is undervalued, fairly priced, or overvalued in the public markets.
Contrasting Inputs in Dividend Discount, FCFE, FCFF, and Residual Income Models
Different valuation frameworks utilize distinct definitions of cash flows, earnings, and return requirements. Selecting the appropriate model depends on corporate dividend policies, capital structure stability, and data availability.
1. Dividend Discount Models (DDM)
The Dividend Discount Model views a share of stock as a claim on the stream of dividend payments distributed by the corporation.
- Cash Flow Definition: Cash dividends paid to common shareholders.
- Discount Rate: Required rate of return on common equity (
 ), typically estimated using the Capital Asset Pricing Model (CAPM).
- Primary Inputs: Current dividend per share, expected future dividend growth rates, and the required return on equity.
- Suitability: Best applied to mature, stable companies with long-term histories of regular dividend payouts, such as utility companies or established consumer staple conglomerates like Procter & Gamble.
2. Free Cash Flow to Equity (FCFE) Models
Free cash flow to equity measures the cash flow remaining available for distribution to common shareholders after all operating expenses, interest payments, net debt service, and necessary investments in working capital and fixed assets have been fulfilled.
- Cash Flow Definition: Net income plus depreciation, minus changes in working capital, minus fixed capital expenditures, plus net new borrowing.
- Discount Rate: Required rate of return on common equity ().
- Primary Inputs: Net income, non-cash charges, working capital investments, fixed capital expenditures, and net debt financing.
- Suitability: Ideal for firms that do not pay steady dividends or whose dividend payouts differ significantly from their capacity to pay dividends.
3. Free Cash Flow to the Firm (FCFF) Models
Free cash flow to the firm evaluates cash flows available to all capital providers—including common shareholders, preferred shareholders, and debt holders—before any financial obligations to debt holders are settled.
- Cash Flow Definition: Earnings before interest and taxes (EBIT) adjusted for taxes, plus non-cash charges, minus capital investments and working capital changes.
- Discount Rate: Weighted Average Cost of Capital (WACC), which combines the cost of equity and the after-tax cost of debt.
- Primary Inputs: Operating income, corporate tax rates, depreciation, capital expenditures, working capital shifts, and capital structure weights.
- Suitability: Highly effective when evaluating firms undergoing significant shifts in their capital structure or firms with high leverage levels where FCFE estimation is volatile.
4. Residual Income Models
Residual income models evaluate intrinsic value by separating a firm’s book value from the present value of future economic profits, defined as net income minus an equity charge.
- Cash Flow Definition: Residual income, calculated as net income minus the product of beginning book value of equity and the cost of equity.
- Discount Rate: Required rate of return on common equity ().
- Primary Inputs: Book value of equity, forecasted earnings, and cost of equity.
- Suitability: Particularly useful when cash flows are unpredictable or negative in early years, or when dividend and free cash flow data are unavailable.
Model Comparison Matrix
| Valuation Model | Cash Flow / Return Metric | Discount Rate | Primary Use Case |
| Dividend Discount Model | Cash Dividends | Required Return on Equity () | Mature, stable dividend-paying firms |
| Free Cash Flow to Equity | FCFE (Net of debt service & capex) | Required Return on Equity () | Firms with variable dividends or high cash retention |
| Free Cash Flow to the Firm | FCFF (Pre-debt cash flows) | Weighted Average Cost of Capital (WACC) | Highly leveraged firms or changing capital structures |
| Residual Income Model | Net Income minus Equity Charge | Required Return on Equity () | Firms with negative early cash flows or strong book values |
Valuation Process Using Present Value Models
Implementing present value models follows a standardized sequential process designed to transform raw financial statement data into a defensible intrinsic value estimate:
- Understand the Business: Analyze the company’s competitive advantage, industry dynamics, macroeconomic exposure, and historical financial performance.
- Forecast Financial Statements: Project income statements, balance sheets, and cash flow statements over a discrete forecast horizon, typically spanning five to ten years.
- Select the Appropriate Model: Choose between DDM, FCFE, FCFF, or residual income based on capital structure and payout characteristics.
- Estimate Cash Flows and Discount Rates: Compute projected cash flows and determine the appropriate discount rate (cost of equity or WACC) using macroeconomic indicators and risk parameters.
- Calculate Terminal Value: Estimate the continuing value of the business beyond the discrete forecast horizon using constant growth or multiple-based approaches.
- Discount and Sum Cash Flows: Discount all discrete forecast cash flows and the terminal value back to the present, then divide by the number of shares outstanding to derive the intrinsic value per share.
- Conduct Sensitivity Analysis: Test how changes in growth rates, discount rates, and margin assumptions impact the final valuation output.
Calculating and Interpreting Intrinsic Value under Constant and Multistage Growth
Constant Growth Models and Growth Formulation
The single-stage (constant) growth model, often called the Gordon Growth Model, assumes that cash flows grow at a constant, perpetual rate ( ). The formula for intrinsic value (
 ) is expressed as:

Where  represents the expected cash flow in the next period, is the discount rate, and is the constant growth rate. For this model to yield meaningful results, the required return () must exceed the perpetual growth rate (), and the growth rate must be lower than or equal to the broader macroeconomic growth rate.
Multistage Growth Models
When companies experience rapid temporary growth followed by a mature steady state, analysts apply multistage models. A two-stage model splits the timeline into an initial high-growth phase and a subsequent stable-growth phase. The intrinsic value is the sum of the present value of cash flows during the high-growth period plus the present value of the terminal value calculated at the transition to stable growth.
Real-World Calculation Example
Consider a hypothetical industrial firm, Apex Machinery, with the following parameters:
- Current Free Cash Flow to Equity (
 ): USD 2.50 per share
- Short-term high growth rate for years 1 through 3: 10% per year
- Perpetual growth rate from year 4 onward: 3% per year
- Required rate of return on equity (): 9%
Step 1: Project FCFE for the High-Growth Phase
- Year 1 FCFE = USD 2.50
 1.10 = USD 2.75
- Year 2 FCFE = USD 2.75 1.10 = USD 3.025
- Year 3 FCFE = USD 3.025 1.10 = USD 3.3275
Step 2: Calculate Year 4 FCFE and Terminal Value at Year 3
- Year 4 FCFE = USD 3.3275 1.03 = USD 3.427325
- Terminal Value at Year 3 (
 ) =
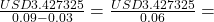 USD 57.122
Step 3: Discount Cash Flows and Terminal Value to Present Value
- PV of Year 1 =
 = USD 2.523
- PV of Year 2 =
 = USD 2.546
- PV of Year 3 + Terminal Value =
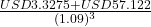 =
 = USD 46.680
- Intrinsic Value per Share () = USD 2.523 + USD 2.546 + USD 46.680 = USD 51.75
Shortcomings of Constant and Multistage Cash Flow Growth Assumptions
While present value models provide mathematical rigor, their underlying assumptions carry notable limitations that analysts must navigate:
- Sensitivity to Inputs: Valuation outputs are exceptionally sensitive to minor adjustments in the discount rate or perpetual growth rate. A 50-basis-point shift in WACC can swing the intrinsic value of a firm by 20% or more.
- Unrealistic Perpetuity Assumptions: Assuming a single constant growth rate in perpetuity fails to account for technological disruption, cyclical economic downturns, and competitive pressures that alter business models over decades.
- Transition Horizon Arbitrariness: Multistage models require subjective judgment regarding when a company transitions from high growth to stable growth, which can introduce analyst bias.
- Inappropriate for Cyclical Firms: Companies in commodities, energy, or heavy cyclical industries experience volatile cash flows that do not conform to smooth constant or staged growth trajectories.
Valuation of Preferred Stock and Contingency Features
Valuation of Non-Callable, Non-Convertible Preferred Stock
Preferred stock represents hybrid equity that shares characteristics with both common stock and fixed-income instruments. Non-callable, non-convertible preferred stock typically pays a fixed dividend in perpetuity with no maturity date. Because the cash flows are fixed and perpetual, the intrinsic value ( ) is calculated as a simple perpetuity:

Where  is the annual preferred dividend and
 is the required rate of return on the preferred stock. For example, if a preferred share pays an annual dividend of USD 5.00 and investors require a 6.5% return, its intrinsic value is
 USD 76.92.
Impact of Contingency Features on Intrinsic Value
Embedded contingency features alter the risk-return profile and market valuation of preferred stock:
- Call Provisions: Allow the issuer to redeem the preferred stock at a predetermined call price after a specific date. This caps the upside price potential for investors, reducing intrinsic value compared to non-callable stock.
- Conversion Features: Permit holders to convert preferred shares into a specified number of common shares. This option adds value, especially if the underlying common stock appreciates significantly.
- Cumulative Provisions: Require issuers to pay all missed preferred dividends before any common stock dividends can be distributed. This safety mechanism enhances investor security and increases intrinsic value.
- Participating Features: Entitle preferred shareholders to receive extra dividends if common stock dividends exceed specified thresholds, increasing the security’s value during periods of strong corporate earnings.
Conclusion
Mastering Discounted Cash Flow and Growth Models is essential for professional equity analysis and sound financial decision-making.
By understanding how to contrast inputs across DDM, FCFE, FCFF, and residual income models, financial professionals can accurately evaluate diverse business models.
While constant and multistage cash flow growth assumptions carry inherent sensitivities and forecasting limitations, disciplined application combined with robust sensitivity analysis yields reliable intrinsic value estimates.
Furthermore, evaluating hybrid instruments such as preferred stock and their embedded contingency features ensures a complete valuation toolkit across the entire capital structure.
