Financial institutions serve as the central nervous system of the modern economy, facilitating the flow of capital from savers to borrowers, providing liquidity, and managing risk.
Because of their unique business models, high leverage, and systemic importance, analyzing banks and insurance companies requires a specialized approach distinct from traditional corporate analysis.
How Financial Institutions Differ from Other Companies?
Financial institutions—primarily commercial banks, investment banks, and insurance companies—differ fundamentally from non-financial corporate entities in their operating mechanics, capital structures, and business risks.
- Financial Assets vs. Physical Assets: Traditional non-financial companies use physical fixed assets (property, plant, and equipment) to manufacture physical goods or provide non-financial services. In contrast, a financial institution’s balance sheet consists almost entirely of financial assets (loans, securities, cash reserves) matched against financial liabilities (deposits, debt, insurance reserves).
- Highly Leveraged Balance Sheets: Non-financial corporations typically maintain debt-to-equity ratios below 2x or 3x to avoid financial distress. Financial institutions operate with extreme leverage, often maintaining debt-to-equity or assets-to-equity ratios between 10x and 20x. A bank’s primary cost of goods sold is the interest paid on deposits and borrowings rather than raw materials.
- Systemic Risk and Interconnectedness: Financial institutions operate in a deeply interconnected network via interbank lending, derivatives clearing, and payment settlement networks. The failure of one major institution can trigger a domino effect across the real economy—a systemic risk scenario rarely seen in standard commercial sectors.
- Information Asymmetry and Asset Inversion: A bank’s principal assets (loans) are often private, unrated, and illiquid, making their true value difficult for outside investors to observe directly. Furthermore, while standard companies raise capital to purchase assets, banks raise liabilities (deposits) that directly fund their revenue-generating assets (loans).
Key Aspects of Financial Regulations
Due to the potential for systemic failure, financial institutions are subject to stringent, highly prescriptive regulatory frameworks designed to protect depositors, policyholders, and public funds.
- Capital Adequacy Requirements: Frameworks established by the Basel Committee on Banking Supervision (Basel III/IV) dictate minimum capital buffers that banks must maintain relative to their risk-weighted assets (RWA). Regulatory capital is stratified into:
- Common Equity Tier 1 (CET1): High-quality capital consisting of common stock and retained earnings.
- Tier 1 Capital: CET1 plus additional qualifying instruments like non-cumulative perpetual preferred stock.
- Tier 2 Capital: Subordinated debt and general loan-loss reserves.
- Liquidity Regulations: Introduced under Basel III to prevent bank runs and short-term liquidity freezes:
- Liquidity Coverage Ratio (LCR): Requires banks to hold sufficient High-Quality Liquid Assets (HQLA) to withstand a 30-day severe stress scenario.
- Net Stable Funding Ratio (NSFR): Requires banks to maintain a stable funding profile in relation to the composition of their assets over a one-year horizon.
- Supervisory Oversight and Stress Testing: Regulatory authorities (e.g., the Federal Reserve, European Central Bank) perform periodic stress tests (such as CCAR in the United States) to simulate extreme macroeconomic downturns and evaluate whether institutions retain sufficient capital to absorb severe losses.
- Consumer and Deposit Protection: Deposit insurance programs (e.g., FDIC in the U.S.) protect retail depositors up to statutory limits, maintaining public confidence and preventing panic-driven bank runs.
The CAMELS Framework for Bank Analysis
Regulators and analysts utilize the CAMELS supervisory rating system to evaluate a bank’s overall internal condition across six core components:
- Capital Adequacy: Measures a bank’s buffer against asset write-downs and insolvency.
- Asset Quality: Evaluates credit risk, loan portfolio risk concentration, and the adequacy of provisions for loan losses.
- Management: Assesses executive capabilities, risk management controls, compliance, and governance processes.
- Earnings: Analyzes the quality, sustainability, and composition of net income and interest margins.
- Liquidity: Evaluates a bank’s ability to meet short-term obligations and deposit withdrawals without incurring unacceptable losses.
- Sensitivity to Market Risk: Measures exposure to adverse changes in interest rates, foreign exchange rates, and asset prices.
Key Ratios and Metrics across CAMELS
| CAMELS Category | Key Financial Ratio / Metric | Formula / Description |
| Capital Adequacy | CET1 Ratio | 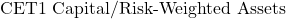 |
| Tier 1 Leverage Ratio | 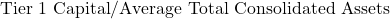 | |
| Asset Quality | NPL Ratio | 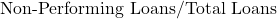 |
| Allowance for Credit Losses / NPLs | Coverage ratio showing loan loss reserve sufficiency relative to bad loans | |
| Management | Efficiency Ratio | 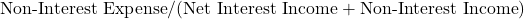 |
| Earnings | Net Interest Margin (NIM) | 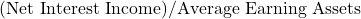 |
| Return on Assets (ROA) | 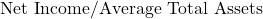 | |
| Return on Equity (ROE) | 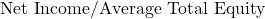 | |
| Liquidity | Loans-to-Deposits Ratio (LDR) | 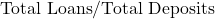 |
| LCR & NSFR | Statutory liquidity ratios measuring HQLA and stable funding sufficiency | |
| Sensitivity | Duration Gap | Difference between the weighted average duration of assets and liabilities |
Limitations of the CAMELS Approach
- Lagging Nature of Financial Statements: CAMELS relies heavily on reported accounting data, which may fail to reflect sudden off-balance-sheet exposures or rapid deterioration in loan quality until default occurs.
- Subjectivity of Management Metrics: Evaluating management capability involves qualitative assessments that can be inconsistent across different analysts or regulatory bodies.
- Model Risk and Risk-Weight Manipulations: Internal models used to compute Risk-Weighted Assets (RWA) can understate real exposure during unprecedented systemic shocks.
- Static Snapshot Constraint: CAMELS assesses a bank at a single point in time, potentially missing dynamic liquidity shifts or sudden deposit flight in digital banking environments.
Analyzing a Bank Based on Financial Statements and Operational Factors
To analyze a bank effectively, an analyst must dissect the balance sheet and income statement while evaluating asset-liability interactions.
1. Balance Sheet Analysis
- Asset Side: Determine the breakdown between earning assets (loans, investment securities) and non-earning assets (cash reserves, fixed assets). Examine the loan portfolio’s sector concentration (e.g., commercial real estate vs. consumer credit).
- Liability Side: Evaluate funding stability. Low-cost non-interest-bearing demand deposits provide a competitive cost-of-funds advantage, whereas reliance on expensive, short-term wholesale borrowings increases funding fragility.
2. Income Statement Analysis
- Net Interest Income (NII): Driven by the spread between interest earned on loans/securities and interest paid to depositors/creditors.
- Non-Interest Income: Fee-based revenue (wealth management, transaction processing, investment banking fees) provides steady, non-spread income.
- Provision for Credit Losses (PCL): An income statement charge that builds up the balance sheet allowance for credit losses, directly reflecting management’s expectations of loan defaults.
3. Key Off-Balance-Sheet Factors
- Unused credit commitments, letters of credit, derivatives contracts, and securitization vehicles do not appear directly on the main balance sheet but carry substantial liquidity, credit, and market risks during market downturns.
Other Key Factors to Consider in Bank Analysis
Beyond financial ratios, comprehensive bank analysis requires evaluating qualitative and macroeconomic variables:
- Interest Rate Environment & Yield Curve Shape: A steep yield curve generally benefits bank profitability by allowing banks to borrow short-term at lower rates and lend long-term at higher rates. A flat or inverted yield curve compresses Net Interest Margins (NIM) and signals macroeconomic recession risks.
- Economic Cycle and Credit Environment: Bank loan default rates correlate tightly with unemployment rates, real estate valuation cycles, and corporate default trends.
- Competitive Landscape and Technological Disruption: Encroachment from fintech firms, neobanks, and non-bank financial intermediaries (“shadow banking”) challenges traditional payment and lending revenues.
- Digital Infrastructure & Cybersecurity: Modern bank failures can be accelerated by mobile app deposit flight. Cybersecurity risk management is now a primary operational vulnerability.
Key Ratios and Factors in Analyzing an Insurance Company
Analyzing insurance companies differs significantly from bank analysis because insurers collect premiums upfront and pay claims later. Their earnings depend on underwriting profitability and investment income. Insurers are categorized into Property & Casualty (P&C) and Life & Health (L&H).
1. Key Insurance Ratios
- Loss Ratio (P&C): Measures underwriting loss exposure.
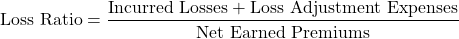
- Expense Ratio: Measures operational efficiency in acquiring and servicing policies.
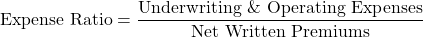
- Combined Ratio: The primary measure of underwriting profitability.
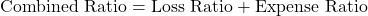
- A Combined Ratio under 100% indicates underwriting profit.
- A Combined Ratio over 100% indicates an underwriting loss (which may still be offset by investment income).
- Investment Yield: Measures return generated on the “float” (collected premiums held before paying claims).
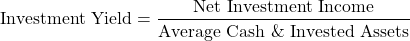
- Operating Ratio: Combines underwriting results and investment returns.
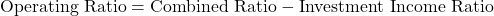
2. Key Regulatory and Structural Metrics
- Solvency II Margin / Statutory Surplus: Regulatory capital measures that evaluate an insurer’s capital buffer against catastrophic claims losses and asset devaluation.
- Embedded Value (EV) (Life Insurance): Represents the present value of future profits from existing policies plus net asset value, offering a realistic view of long-term economic worth that standard accounting (IFRS/GAAP) often obscures.
3. Qualitative Factors in Insurance Analysis
- Reserve Adequacy: Insurers estimate reserves for future claims. Under-reserving artificially inflates current earnings, setting up future earnings hits when reserves must be strengthened.
- Catastrophe Risk and Reinsurance: P&C insurers are vulnerable to natural disasters. Analysts must review an insurer’s reinsurance structure to confirm that tail risks are adequately transferred to third parties.
- Interest Rate Sensitivity (Life Insurers): Life insurers hold long-duration liabilities with guaranteed minimum payout rates. Prolonged periods of ultra-low interest rates reduce investment yields on fixed-income investments, creating structural liability mismatches.
