Corporate payout mechanisms alter shareholder equity structures and impact key financial metrics differently depending on whether cash leaves the balance sheet.
Impact of Corporate Actions on Shareholder Wealth and Financial Ratios
- Regular Cash Dividends: Scheduled distributions of cash from retained earnings to shareholders.
- Shareholder Wealth: Total wealth remains unchanged at distribution. On the ex-dividend date, the share price theoretically drops by the dividend amount, converting market capital into cash holdings equal to the payout.
- Financial Ratios: Cash and Retained Earnings decrease. Total assets and equity drop. Current Ratio and Quick Ratio decline. Debt-to-Equity (D/E) increases due to lower equity. Return on Equity (ROE) and Return on Assets (ROA) increase over time as asset/equity bases shrink.
- Extra (Special) Dividends: Non-recurring cash distributions declared during periods of exceptional profitability or liquidity.
- Shareholder Wealth & Ratios: Similar to regular dividends, but market expectations treat them as non-permanent, preventing permanent valuation re-ratings.
- Liquidating Dividends: Returns of original capital contributed by shareholders when a business segment or the entire firm ceases operations, reducing Paid-in Capital rather than Retained Earnings.
- Shareholder Wealth & Ratios: Wealth is converted from equity ownership to cash. Leverage ratios rise sharply, while total assets contract permanently.
- Stock Dividends: Distribution of additional shares to existing stockholders in proportion to current ownership (e.g., a
 stock dividend).
- Shareholder Wealth: Wealth remains completely unchanged. Ownership percentages stay identical, while the share price drops proportionally to reflect the expanded share count:
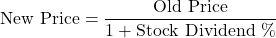
- Financial Ratios: Capital allocation shifts within equity—Retained Earnings decrease while Common Stock and Paid-in Capital accounts increase by an equal amount. Total assets, total equity, D/E, ROE, and ROA remain unchanged. Earnings Per Share (EPS) decreases, but the total earnings entitlement of each investor is unaffected.
- Shareholder Wealth: Wealth remains completely unchanged. Ownership percentages stay identical, while the share price drops proportionally to reflect the expanded share count:
- Stock Splits: An increase in the number of outstanding shares with a proportional decrease in par value (e.g., a 2-for-1 split).
- Shareholder Wealth & Ratios: Zero impact on net wealth or capital accounts. Share prices drop by
 in a 2-for-1 split. Liquidity may improve due to a lower per-share market price. EPS and Book Value Per Share (BVPS) decrease proportionally, while leverage, profitability, and liquidity ratios remain unchanged.
- Shareholder Wealth & Ratios: Zero impact on net wealth or capital accounts. Share prices drop by
- Reverse Stock Splits: A reduction in outstanding shares with a proportional increase in share price (e.g., a 1-for-5 split).
- Shareholder Wealth & Ratios: Net wealth remains unchanged. Used to meet stock exchange minimum listing requirements. Financial statements show a re-allocation of equity across fewer shares; EPS and BVPS increase proportionally, but financial ratios remain identical.
| Action Type | Cash Balance | Total Equity | Share Count | Share Price | Leverage (D/E) | ROE / ROA | Net Shareholder Wealth |
| Regular / Extra Cash Dividend | Decreases | Decreases | Unchanged | Decreases by dividend | Increases | Increases | Unchanged |
| Liquidating Dividend | Decreases | Decreases | Unchanged | Decreases by dividend | Increases | Increases | Unchanged |
| Stock Dividend | Unchanged | Unchanged | Increases | Decreases proportionally | Unchanged | Unchanged | Unchanged |
| Stock Split | Unchanged | Unchanged | Increases | Decreases proportionally | Unchanged | Unchanged | Unchanged |
| Reverse Stock Split | Unchanged | Unchanged | Decreases | Increases proportionally | Unchanged | Unchanged | Unchanged |
Characteristics of Companies At Risk of Dividend Cuts
Companies struggling to maintain cash payouts exhibit distinct structural and operational vulnerabilities:
- High Financial Leverage: Debt service obligations consume operating cash flows, reducing coverage for discretionary equity payouts.
- Volatile Operating Cash Flows: Cyclical revenues make cash flows predictable only during economic expansions, leaving dividend coverage thin during downturns.
- Negative Free Cash Flow to Equity (FCFE): Paying dividends by issuing debt or equity capital rather than funding them through operational cash generation.
- High Payout Ratios: A Dividend Payout Ratio exceeding
 to
 leaves limited retained earnings to absorb operational earnings shocks.
- Declining Coverage Ratios: Net Income Dividend Coverage falling below
 or FCFE Dividend Coverage dropping below
 .
Theories of Dividend Policy and Market Signaling
Financial economists debate whether corporate payout choices influence total firm value or simply redistribute value between capital components.
Theories of Dividend Policy
Modigliani-Miller (MM) Dividend Irrelevance Theorem
Modigliani and Miller argue that in a frictionless capital market (zero taxes, zero transaction costs, equal access to information, and static investment policy), dividend policy has zero effect on shareholder wealth or firm value.
The value of the firm is driven entirely by its basic earning power and investment strategy, not by how earnings are divided between retained capital and cash distributions. If an investor desires current cash flow, they can create a “synthetic dividend” by selling a portion of their holdings. Conversely, if a company pays a dividend that an investor does not need, the investor can reinvest the cash to purchase additional shares.
Bird-in-the-Hand Theory (Gordon and Lintner)
Myron Gordon and John Lintner argue that investors prefer current cash dividends to uncertain future capital gains. Cash distributions reduce investor uncertainty. Under this view, investors discount dividend-paying stocks at a lower required rate of return ( ), which increases total share value:

A higher dividend payout ratio decreases the discount rate , elevating the firm’s equity valuation.
Tax-Preference Theory
In tax regimes where capital gains are taxed at lower rates than cash dividends, or where capital gain taxes are deferred until assets are sold, shareholders prefer earnings retention over cash distributions. Under this model, high dividend payouts increase the total tax burden on investors, causing them to demand higher pre-tax returns, which lowers the current value of the stock.
Information Content and Dividend Signaling
When information asymmetry exists between corporate managers and external markets, dividend adjustments serve as credible signals regarding future earnings prospects:
- Dividend Initiations: Signal that a company has matured, achieved predictable profitability, and generated sustainable cash flow. However, it may also signal a reduction in high-return internal growth opportunities.
- Dividend Increases: Convey managerial confidence in higher, permanent baseline cash flow generation. Markets view dividend increases as positive signals, boosting stock prices.
- Dividend Decreases / Cuts: Generally interpreted as a signal of deteriorating operational profitability, leading to negative stock price adjustments.
- Dividend Omissions: Signal severe liquidity distress or complete capital realignments toward distressed debt repayment, frequently causing sharp price declines.
Agency Costs and Payout Policy
Agency conflicts arise between self-interested managers and dispersed equity owners.
- Free Cash Flow Hypothesis: Managers with excess free cash flow may invest in sub-optimal, value-destroying projects or excess corporate overhead instead of returning capital to shareholders.
- Mitigation via Dividends: High cash dividend payouts commit management to regular cash outflows, reducing discretionary funds available for bad investments. This forces management to seek external capital markets for new projects, subjecting their business models to investment banking scrutiny.
- Bondholder-Shareholder Conflicts: Debt holders prefer cash retention to cushion default risk. Paying large dividends transfers wealth from bondholders to shareholders by reducing the asset base securing outstanding debt obligations.
Practical Factors Influencing Corporate Dividend Policy
- Investment Opportunities: Companies with high return on invested capital relative to weighted average cost of capital (
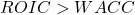 ) retain cash to fund growth.
- Tax Considerations: Differential tax rates applied to ordinary income vs. long-term capital gains dictate payout preference.
- Flotation Costs: High investment banking fees for equity issuances encourage firms to retain cash to fund internal growth.
- Legal and Contractual Constraints:
- Impairment of Capital Rule: Legal restrictions prohibiting companies from distributing cash if dividends exceed accumulated retained earnings.
- Debt Covenants: Restrictions imposed by lenders limiting cash payouts based on leverage or coverage metrics (e.g., maintaining an interest coverage ratio above
 ).
- Liquidity and Financial Flexibility: Cash balances, access to commercial paper markets, and macroeconomic stability dictate payout stability.
Taxation and Payout Policy Calculations
Tax frameworks affect the net cash yield received by equity investors after accounting for corporate and individual tax liabilities.
International Tax Systems on Corporate Earnings
Double Taxation System
Corporate earnings are taxed at the corporate rate ( ), and distributed earnings are taxed again at the individual shareholder dividend rate (
 ).
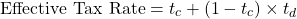
Dividend Imputation System
Corporate tax paid on distributed income flows to individual investors as a tax credit (franking credit). The total income is taxed at the individual shareholder’s marginal tax rate ( ). If the corporate rate exceeds the individual rate, the shareholder receives a tax refund; if lower, the shareholder pays the difference.
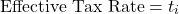
Split-Rate Tax System
Corporate profits are taxed at different rates depending on whether earnings are retained ( ) or distributed as dividends (
 ).
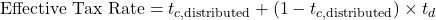
Comparative Tax Calculations
Consider USD1.00 of pre-tax corporate earnings under each system with the following baseline tax assumptions:
- Corporate Tax Rate () =

- Individual Dividend Tax Rate () =

- Individual Marginal Income Tax Rate () =

- Split-Rate Retained Earnings Tax () =

- Split-Rate Distributed Earnings Tax () =

1. Double Taxation System
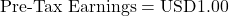
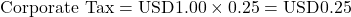
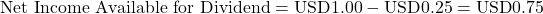
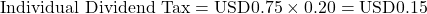
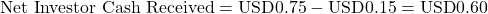
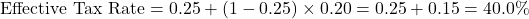
2. Dividend Imputation System
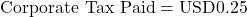
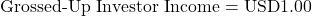
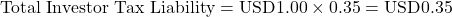
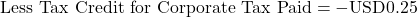
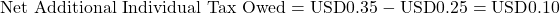
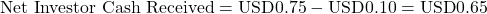
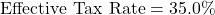
3. Split-Rate Tax System (Distributed Earnings)
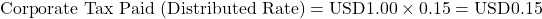
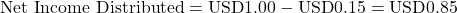
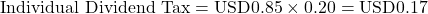
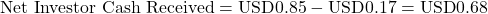
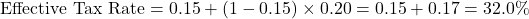
Dividend Models and Global Payout Trends
Management teams choose corporate dividend structures based on market conditions and capital requirements.
Stable Dividend vs. Constant Dividend Payout Ratio
- Stable Dividend Policy: Dividends are set to a predictable, steadily growing dollar amount per share. Management adjusts payouts only when long-term baseline earnings shift higher, using a target payout adjustment model:
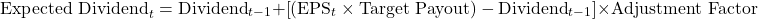
- Constant Dividend Payout Ratio Policy: Dividends represent a fixed percentage of net income each period. Cash payouts fluctuate directly with cyclical corporate earnings.
Comparative Calculation Example
A firm targets a  payout ratio. Year 0 dividend was USD2.00 per share. Over the next three years, EPS fluctuates as follows: Year 1 = USD6.00, Year 2 = USD4.00, Year 3 = USD7.00. The adjustment factor for the stable dividend policy is
 .
Year 1 Stable Dividend = USD2.00 + [(USD6.00 × 0.40) - USD2.00] × 0.30
                       = USD2.00 + [USD2.40 - USD2.00] × 0.30
                       = USD2.12

Year 2 Stable Dividend = USD2.12 + [(USD4.00 × 0.40) - USD2.12] × 0.30
                       = USD2.12 + [USD1.60 - USD2.12] × 0.30
                       = USD1.964

Year 3 Stable Dividend = USD1.964 + [(USD7.00 × 0.40) - USD1.964] × 0.30
                       = USD1.964 + [USD2.80 - USD1.964] × 0.30
                       = USD2.215
For the Constant Dividend Payout Policy, distributions track net income directly:
- Year 1:
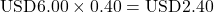
- Year 2:
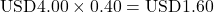
- Year 3:
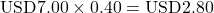
| Metric / Scenario | Year 0 | Year 1 | Year 2 | Year 3 |
| EPS | N/A | USD6.00 | USD4.00 | USD7.00 |
| Stable Dividend Policy Payout | USD2.00 | USD2.12 | USD1.96 | USD2.22 |
| Constant Payout Ratio (40%) Payout | N/A | USD2.40 | USD1.60 | USD2.80 |
Broad Trends in Corporate Payout Policies
- Growth of Share Repurchases: Repurchases make up a larger percentage of total corporate payouts, particularly in North America, due to their timing flexibility and favorable capital gains tax treatment.
- Decreasing Proportion of Dividend Payers: Fewer public companies pay regular cash dividends, as newly listed growth firms prefer to retain earnings for expansion.
- Sticky Dividend Targets: Mature multinationals maintain dividend levels, using share repurchases as a flexible secondary mechanism to distribute excess cash during peak cycles.
Share Repurchases
Share repurchases occur when a corporation buys back its own stock from the open market or directly from shareholders.
Share Repurchase Methods
- Open Market Repurchases: The company buys shares on the open market at prevailing prices over time. Offers flexibility, as the firm has no legal obligation to complete declared buyback volumes.
- Fixed-Price Tender Offer: The company offers to repurchase a fixed number of shares at a specified premium price over the market rate within a defined timeframe.
- Dutch Auction Tender Offer: The company specifies a price range and target number of shares. Shareholders submit bids indicating the minimum price at which they are willing to sell. The firm selects the lowest price that allows it to buy back the requested quantity of stock, paying that uniform clearing price to all participating sellers.
- Direct Negotiation (Targeted Repurchases): Buying back equity directly from a major shareholder, often at a premium to eliminate a hostile takeover threat or at a discount to buy out an institutional holder.
EPS Impact: Cash vs. Debt Financing
The impact of a buyback on EPS depends on whether it is funded using surplus cash or borrowed funds.
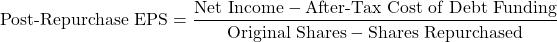
1. Cash-Financed Repurchase Example
- Net Income: USD50,000,000
- Outstanding Shares: 10,000,000
- Baseline EPS: USD5.00
- Current Stock Price: USD50.00
- Cash Used for Buyback: USD20,000,000
- Foregone Interest Earned on Cash (After-Tax):
 (or USD400,000 total)
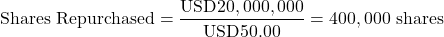
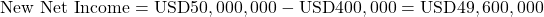
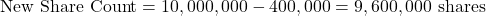
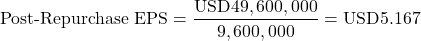
Conclusion: EPS increases because the lost earnings interest yield on cash () is lower than the company’s earnings yield (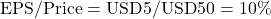 ).
2. Debt-Financed Repurchase Calculations
- Borrowing Cost (Before Tax):

- Corporate Tax Rate:
- After-Tax Cost of Debt (
 ):
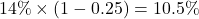
- Debt Capital Raised & Used for Repurchase: USD20,000,000
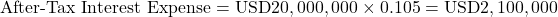
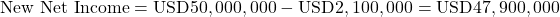
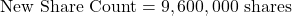
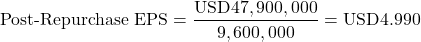
Conclusion: EPS declines because the after-tax cost of debt ( ) exceeds the earnings yield (
 ).
Core Rule for EPS Impact
- If Earnings Yield (
 )
 After-Tax Cost of Funds, Post-Repurchase EPS increases.
- If Earnings Yield ()
 After-Tax Cost of Funds, Post-Repurchase EPS decreases.
Effect of Share Repurchases on Book Value Per Share (BVPS)
The effect of a buyback on BVPS depends on how the repurchase price compares to the original BVPS:
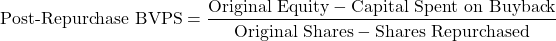
BVPS Calculation Example
- Total Common Equity: USD100,000,000
- Shares Outstanding: 5,000,000
- Original BVPS:
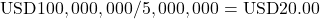
Scenario A: Repurchase Price Above BVPS (Market Price = USD25.00)
Buyback amount: USD10,000,000 (400,000 shares repurchased).
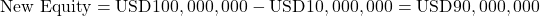
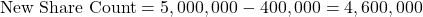
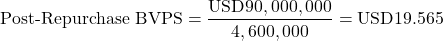
Scenario B: Repurchase Price Below BVPS (Market Price = USD15.00)
Buyback amount: USD10,000,000 (666,667 shares repurchased).
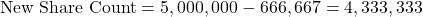
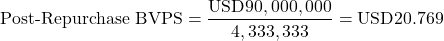
Core Rule for BVPS Impact
- Repurchasing shares at a price above original BVPS decreases BVPS.
- Repurchasing shares at a price below original BVPS increases BVPS.
Choosing Between Cash Dividends and Share Repurchases
- Flexibility: Repurchases lack the implicit long-term commitment of cash dividends, allowing management to return excess capital without setting high expectations for future payouts.
- Executive Compensation Alignment: Stock options encourage share repurchases over cash dividends, as repurchases reduce outstanding shares and support stock prices without dropping the share price by an ex-dividend amount.
- Tax Efficiency: Repurchases allow shareholders to defer tax liabilities or pay taxes at lower capital gains rates, whereas cash dividends trigger immediate income taxes.
- Capital Structure Adjustments: Debt-financed buybacks allow companies to quickly increase leverage and optimize their weighted average cost of capital (
 ).
Dividend Coverage Ratios
Coverage metrics evaluate the sustainability of cash dividend distributions using income statement and cash flow metrics.
Net Income Dividend Coverage Ratio
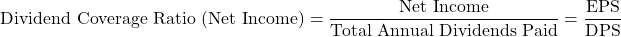
Interpretation: Measures the multiple by which accounting earnings cover equity payouts. Ratios below indicate the firm is paying dividends using capital reserves or debt, raising solvency risks.
Free Cash Flow to Equity (FCFE) Dividend Coverage Ratio
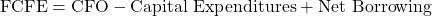

Interpretation: A more reliable measure than net income coverage, as FCFE isolates actual operating cash available after meeting working capital needs, debt obligations, and required capital expenditures. An FCFE coverage ratio below signals that current dividend levels are unsustainable without external borrowing or asset sales.
Calculation Example
- Net Income: USD120,000,000
- Operating Cash Flow (CFO): USD140,000,000
- Capital Expenditures (CapEx): USD50,000,000
- Net Debt Issued: USD10,000,000
- Dividends Paid: USD60,000,000
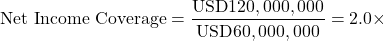
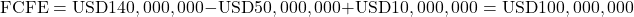
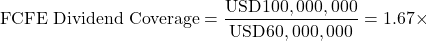
Analysis: Net income coverage ( ) suggests a safe payout cushion, while the FCFE coverage ratio (
 ) provides a clearer picture by accounting for capital expenditure needs. Both metrics show that the dividend remains well covered by operational performance.
