Active equity portfolio construction is the process of translating a manager’s insights, forecasts, and investment philosophy into a concrete, risk-managed portfolio designed to outperform a benchmark index.
This comprehensive analysis covers the foundational philosophy, structural construction methodologies, risk management frameworks, practical execution constraints, portfolio structure efficiency, and strategic long/short approaches.
Investment Philosophy and Portfolio Construction
An investment manager’s investment philosophy represents their core set of beliefs about how markets operate, where inefficiencies lie, and how those inefficiencies can be systematically exploited to generate excess returns (alpha). This philosophy acts as the blueprint for the entire portfolio construction process.
Investment Philosophy  ──►  Alpha Sources & Factor Exposure  ──►  Portfolio Constraints
        │                                                              │
        ▼                                                              ▼
Security Selection      ──►  Weighting & Risk Allocation     ──►  Target Portfolio
Key Elements Influencing Construction
- Market Inefficiency Beliefs:
- Fundamental / Valuation-Based: Managers who believe equity prices periodically diverge from intrinsic value focus on long-term cash flow models, earnings quality, and asset values. Construction emphasizes value metrics (Price-to-Earnings, Price-to-Book) and fundamental bottom-up weighting.
- Behavioral / Momentum-Based: Managers who believe investors overreact or underreact to information focus on price momentum, earnings surprises, and market trends. Construction prioritizes relative strength indicators and dynamic rebalancing rules.
- Informational / Quantitative: Managers who believe alpha is extracted through systemic statistical patterns employ multi-factor quantitative models. Construction relies heavily on mathematical optimization rather than subjective stock selection.
- Source of Alpha (Bottom-Up vs. Top-Down):
- Bottom-Up Focus: Believes individual stock selection drives performance. Portfolio construction is centered on fundamental stock analysis, security-specific active weights, and stock-picking skill. Sector and macroeconomic exposures are typically neutralized or controlled secondary outputs.
- Top-Down Focus: Believes macroeconomic cycles, sector rotation, themes, and country allocations drive returns. Construction starts with macro asset allocation across regions, industries, or factors, followed by selecting representative securities within those allocations.
- Factor Exposures and Style Biases:
- Managers intentionally incorporate exposures to known risk factors—such as Value, Size (small cap vs. large cap), Quality (profitability, balance sheet strength), Momentum, and Low Volatility.
- The investment philosophy dictates whether these exposures are dynamic (factor timing) or strategic (consistent factor tilt), directly driving the tracking error and risk profile of the portfolio.
Approaches for Constructing Actively Managed Equity Portfolios
Active equity portfolios are built using two primary approaches: Systematic (Quantitative) and Discretionary (Fundamental), as well as Combinations (Quantamental).
Systematic vs. Discretionary Approaches
| Dimension | Systematic (Quantitative) | Discretionary (Fundamental) |
| Decision Driver | Rules-based quantitative models & algorithms | Human judgment & fundamental research |
| Data Scope | Broad cross-section of securities (broad depth) | In-depth analysis of fewer companies (narrow depth) |
| Risk Management | Integrated math optimizer (mean-variance, risk-budgeted) | Subjective bounds, analyst targets, committee reviews |
| Turnover & Cost | Higher turnover; lower execution cost per trade | Lower turnover; higher fundamental research cost |
| Main Advantage | Eliminates emotional bias; highly scalable | Deep understanding of complex edge cases & business models |
Portfolio Construction Techniques
- Systematic (Quantitative) Optimization:
- Uses mathematical algorithms (e.g., mean-variance optimization, Black-Litterman) to maximize expected return for a target level of risk or minimize tracking error given return targets.
- Constraints: Applied to sector weights, single-stock caps, factor tilts, and turnover limits to prevent “corner solutions” (unrealistic allocations driven by noisy data).
- Discretionary (Fundamental) Construction:
- Focuses on detailed analysis of financial statements, management meetings, and industry structures.
- Portfolios are constructed using conviction-weighted rankings, target price upsides, or model portfolios created by central research analyst teams.
- Combined (“Quantamental”) Approaches:
- Integrates quantitative screens to define a universe or generate initial candidate weights with fundamental analyst overrides or qualitative research checks before execution.
Active Share and Active Risk
Evaluating an active equity manager’s strategy requires understanding both the extent to which their portfolio differs from the benchmark and the return volatility resulting from those differences.
Active Share
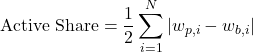
Where  is the weight of security
 in the portfolio and
 is its weight in the benchmark index.
- Measures the degree to which a portfolio’s stock holdings differ from the benchmark index.
- Ranges from
 (identical to the benchmark) to
 (no overlap with the benchmark).
- Active Share increases when a manager takes concentrated individual stock positions or holds stocks not included in the index.
Active Risk (Tracking Error)
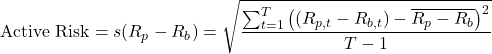
Where  and
 are portfolio and benchmark returns in period
 , respectively.
- Measures the volatility (standard deviation) of excess returns relative to the benchmark over time.
- Reflects the uncertainty of active returns resulting from systematic factor tilts (e.g., sector overweights, beta differentials) as well as stock selection.
Interaction Matrix: Active Share vs. Active Risk
                  HIGH ACTIVE SHARE
                          │
     Concentrated Stock   │   Pure Stock Pickers
     Pickers / Macro      │   (High conviction,
     Sector Rotators      │   uncorrelated alpha)
                          │
LOW ACTIVE RISK ──────────┼────────── HIGH ACTIVE RISK
                          │
     Benchmark Packers    │   Factor Tilters /
     ("Closet Indexers")  │   Systematic Smart Beta
                          │
                  LOW ACTIVE SHARE
- High Active Share + High Active Risk: Concentrated, fundamental stock pickers holding off-benchmark stocks or taking strong non-factor bets.
- High Active Share + Low Active Risk: Multi-stock bottom-up selection where individual active stock bets cancel each other out at the sector/macro level, keeping tracking error low.
- Low Active Share + High Active Risk: Broadly diversified portfolios taking major systematic bets (e.g., heavily tilting toward high-beta or specific sectors).
- Low Active Share + Low Active Risk: “Closet indexers” charging active fees while hugging the benchmark.
Risk Budgeting in Portfolio Construction
Risk budgeting is the process of breaking down overall portfolio risk into constituent components and allocating risk explicitly to areas where the manager expects the highest risk-adjusted active return.
Core Concepts
- Total Active Risk Decomposition:
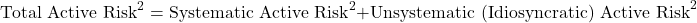
- Marginal Contribution to Active Risk (MCAR):Measures how much an incremental increase in a security or sector position increases total active risk.
- Absolute / Relative Risk Contribution:Calculates the percentage of total portfolio active variance driven by specific asset bets, sector allocations, or factor exposures.
Application Process
- Setting the Overall Active Risk Target: Define total acceptable tracking error (e.g.,
 ).
- Decomposing Active Risk: Allocate tracking error budget across distinct sources:
- Factor Bets:
 tracking error budget to Style/Size factors.
- Sector/Industry Bets:
 tracking error budget to sector timing.
- Security Selection:
 tracking error budget to fundamental stock selection.
- Factor Bets:
- Optimizing Allocations: Adjust portfolio weights so that the ratio of expected active return to marginal risk contribution is equalized across all portfolio holdings:
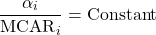
Risk Measures and Limits in Equity Portfolio Construction
Managers integrate quantitative risk measures and hard/soft policy limits to prevent unwanted concentration, unintended factor bets, and extreme drawdown risk.
Key Risk Measures
- Absolute Volatility / Standard Deviation (
 ): Overall variability of total returns.
- Active Volatility / Tracking Error (
 ): Variability of excess returns versus the benchmark.
- Value at Risk (VaR): Maximum expected loss over a specific time horizon at a given confidence level (e.g., 95% 1-day VaR).
- Conditional VaR (CVaR / Expected Shortfall): Average loss incurred given that the loss exceeds the VaR threshold (captures tail risk).
- Beta (
 ): Systematic sensitivity relative to the market benchmark.
- Factor Exposures: Standard deviation units (z-scores) relative to style factor benchmarks (Growth, Value, Momentum, Quality).
How Limits Affect Portfolio Construction
- Single Issuer / Position Limits (e.g., max 5% per stock):
- Effect: Forces diversification, limits single-company idiosyncratic blow-up risk, but reduces the potential impact of top high-conviction stock ideas.
- Sector / Industry Allocation Bands (e.g., benchmark weight
 ):
- Effect: Restricts top-down macro bias, forcing the portfolio to generate performance primarily via stock selection within sectors rather than broad sector timing.
- Tracking Error Limits (e.g., max 3.5% TE):
- Effect: Clamps down overall active deviation from the benchmark, forcing managers to keep market exposure (Beta) close to 1.0 and limiting extreme factor tilts.
- Liquidity Limits (e.g., 90% of portfolio liquidable in 3 days):
- Effect: Constrains allocations to small-cap or low-volume securities, shifting portfolio allocation toward large-cap, liquid equities.
Practical Execution Constraints
Real-world portfolio construction must balance theoretical alpha models against real-world execution friction, liquidity bounds, and asset scales.
Impact of Constraints on Construction
                        ASSETS UNDER MANAGEMENT (AUM)
                                      │
              ┌───────────────────────┴───────────────────────┐
              ▼                                               ▼
     Capacity Constraints                           Trading Market Impact
              │                                               │
              ├─► Lower Active Share                          ├─► Increased Execution Costs
              ├─► Position Size Caps                          ├─► Slower Portfolio Turnover
              └─► Shift to Large-Cap Stocks                   └─► Alpha Decay & Execution Drag
- Assets Under Management (AUM):
- As AUM grows, maintaining high Active Share becomes difficult. Large funds are forced to spread capital across more securities or concentrate only in mega-cap stocks, leading to “capacity constraints.”
- Position Size:
- Managers cap position size based on average daily volume (ADV) (e.g., a single position must not exceed
 of the security’s ADV over 5 trading days).
- Larger position sizes increase portfolio concentration risk and exit friction.
- Managers cap position size based on average daily volume (ADV) (e.g., a single position must not exceed
- Market Liquidity:
- Lower liquidity requires wider bid-ask spreads and higher market impact costs when buying or selling.
- Illiquid market environments limit a manager’s ability to rebalance quickly in response to fundamental news or risk threshold breaches.
- Portfolio Turnover:
- Turnover measures how frequently assets are bought and sold annually.
- Turnover Drag: High turnover creates transaction costs (brokerage commissions, bid-ask spreads, market impact, and potential capital gains tax realizations) that drag down net returns. Managers must ensure that gross expected alpha exceeds the total cost of trading generated by turnover.
Evaluating Portfolio Structure Efficiency
Portfolio structure efficiency assesses how effectively an active equity strategy converts active risk into excess return, given its stated investment mandate.
Quantitative Metrics for Structure Evaluation
- Sharpe Ratio: Evaluates risk-adjusted return relative to total risk.

- Information Ratio (IR): Evaluates risk-adjusted excess return relative to active risk (tracking error).
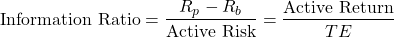
- Fundamental Law of Active Management (Grinold-Kahn):
Where IC represents manager skill (correlation between predicted and actual returns) and Breadth (N) represents the number of independent investment decisions per year.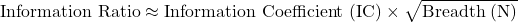
Evaluating Mandates
An efficient portfolio structure aligns active risk allocation with the core driver of the manager’s skill (IC):
- High-Breadth / Quantitative Managers: Should maintain broad diversification across many small active bets (
 is high) to maximize efficiency.
- High-Skill / Fundamental Managers: Should maintain a concentrated portfolio ( is low, but
 per stock is high) to avoid diluting key high-conviction ideas.
Long-Only, Long Extension, Long/Short, and Equitized Market-Neutral Approaches
Active equity managers structure portfolios across a spectrum of short-selling allowances, leverage, and net market exposures.
Comparison Matrix
| Property | Long-Only | Long Extension (e.g., 130/30) | Long/Short Equity | Equitized Market-Neutral |
| Gross Exposure | |  (  Long +  Short) |  to  |  ( Long + Short) |
| Net Market Exposure |  (Beta  ) | (Beta ) | Variable ( to  ) | (Beta  ) |
| Short-Selling Used? | No | Yes | Yes | Yes |
| Primary Alpha Source | Overweighting undervalued stocks | Exploiting undervalued AND overvalued stocks | Stock selection + Directional market exposure | Pure relative stock selection (Uncorrelated Alpha) |
| Key Risks | Absolute market drawdowns | Short squeeze risk, prime broker leverage cost | Short squeeze, market exposure mismatch | Leverage risk, execution leg risk, factor model error |
                       EQUITY APPROACHES & BETA EXPOSURES
                                      │
      ┌───────────────────────────────┼───────────────────────────────┐
      ▼                               ▼                               ▼
Market Neutral (Beta = 0)   Long Extension (Beta = 1.0)      Long-Only (Beta = 1.0)
Gross: 200% (100L / 100S)   Gross: 160% (130L / 30S)         Gross: 100% (100L / 0S)
Pure Uncorrelated Alpha     Enhanced Active Alpha            Traditional Long Alpha
Detailed Breakdown of Approaches
- Long-Only Approach:
- Mechanism: Holds long positions funded fully by equity capital.
- Limitation: Constrained by benchmark weighting—a manager can only underweight a security to . For small-cap index stocks with negligible weights (e.g.,
 ), the maximum negative active tilt is capped at
 , even if the manager expects catastrophic failure.
- Long Extension Approach (e.g., 130/30):
- Mechanism: Short-sells overvalued securities up to a fraction of the portfolio (e.g., ) and uses cash proceeds to buy additional long positions ( total long).
- Effects: Maintains net market exposure/beta equal to
 while removing the long-only constraint, allowing full expression of negative active conviction via shorting.
- Mechanism: Short-sells overvalued securities up to a fraction of the portfolio (e.g.,
- Long/Short Equity Approach:
- Mechanism: Holds long positions in expected winners and short positions in expected losers, varying net market exposure dynamically based on macroeconomic views.
- Effects: Provides downside market protection while seeking both equity risk premium and alpha.
- Equitized Market-Neutral Approach:
- Mechanism: Holds equal long and short dollar balances ( long / short) paired to eliminate systematic market risk (Beta = 0, Factor Neutral). Equitizes cash collateral via stock index futures to achieve benchmark equity exposure if desired.
- Effects: Generates pure alpha uncorrelated with general equity market direction, though highly dependent on leverage and prime brokerage lending rates.
- Mechanism: Holds equal long and short dollar balances (
