This comprehensive guide explores the pricing and valuation of futures contracts, examining the core differences between forward and futures contracts, comparing their respective values and prices, and detailing the economic mechanisms that cause forward and futures prices to differ in modern financial markets.
Introduction to Derivative Pricing and Market Mechanics
In global financial markets, managing price risk is a fundamental requirement for multinational corporations, financial institutions, and institutional investors. Derivative contracts, specifically forward and futures contracts, serve as primary instruments for hedging and speculative activities. Understanding the precise mechanics behind the pricing and valuation of futures contracts is essential for corporate treasurers, portfolio managers, and financial analysts seeking to optimize risk management strategies. While forward and futures contracts share the same foundational economic purpose—locking in an asset’s future delivery price—their structural designs, liquidity characteristics, and settlement procedures create distinct pricing and valuation profiles. This article provides a rigorous examination of how these instruments are valued, how their prices are determined, and why theoretical pricing models often yield divergences between the two derivatives.
Foundations of Forward and Futures Pricing
To understand how derivatives are valued, one must first distinguish between the price of a contract and the value of a contract. The price of a forward or futures contract is the delivery price specified in the contract that is agreed upon today for an asset to be delivered at a future date. At the inception of a standard forward or futures contract, the delivery price is set such that the initial value of the contract is zero to both parties.
As market conditions change—specifically regarding the spot price of the underlying asset, interest rates, storage costs, and convenience yields—the price locked into the contract remains fixed, but the value of the contract fluctuates. For a buyer, if the current market price for future delivery rises above the locked-in delivery price, the contract acquires a positive value. Conversely, if market prices fall, the contract has a negative value.
Global exchanges such as CME Group and the Intercontinental Exchange facilitate the standardized trading of futures contracts, ensuring continuous price discovery and transparent market valuation. Financial institutions like Goldman Sachs and JPMorgan Chase utilize these pricing frameworks daily to manage multi-billion-dollar portfolios across commodities, foreign exchange, and interest rate products.
A. Value Versus Price in Forward Contracts
A forward contract is a customized, over-the-counter (OTC) agreement between two private parties to buy or sell an asset at a specified future date at a predetermined price. Because they are not traded on an exchange, forward contracts carry counterparty credit risk and lack secondary market liquidity.
Valuation of Forward Contracts Over Time
The pricing of a forward contract is derived using the cost-of-carry model. For an investment asset that provides no income, the forward price ( ) is determined by compounding the current spot price (
 ) at the risk-free interest rate (
 ) over the time to maturity (
 ):

When valuing an existing forward contract during its life at time  , the value of the forward contract (
 ) to the long position is calculated by discounting the difference between the current forward price for the remaining maturity (
 ) and the original delivery price (
 agreed upon at inception):
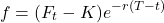
Because no cash changes hands at the inception of a forward contract, the initial value is zero. As the spot price of the underlying asset fluctuates, changes, causing the value of the contract to become positive for the buyer and negative for the seller, or vice versa. However, because no intermediate cash flows occur, the credit risk accumulates throughout the life of the contract, culminating at maturity.
B. Value Versus Price in Futures Contracts
Futures contracts are legally binding, standardized agreements traded on regulated exchanges. Unlike forward contracts, futures contracts are subject to daily settlement, known as marking-to-market.
Marking-to-Market and Daily Settlement Mechanics
At the end of every trading day, the profit or loss on a futures contract is calculated based on the daily settlement price. The margin account of the investor is adjusted accordingly. If a position gains value, cash is deposited into the investor’s account; if it loses value, cash is withdrawn.
Consequently, the value of a futures contract at the end of each trading day is reset to zero. Investors do not accumulate unrealized gains or losses over the life of the contract; instead, all gains and losses are realized daily. This daily cash flow mechanism drastically reduces counterparty credit risk compared to forward contracts, as the clearinghouse guarantees performance and mitigates default risk.
Comparative Analysis of Forward and Futures Contracts
To clearly delineate the structural and operational distinctions between these two derivative instruments, the following table summarizes their primary characteristics.
| Feature | Forward Contracts | Futures Contracts |
| Market Venue | Over-the-Counter (OTC) between private parties | Organized, regulated exchanges (e.g., CME Group) |
| Contract Customization | Fully customizable regarding size, delivery date, and asset specifications | Highly standardized terms, contract sizes, and delivery dates |
| Counterparty Risk | Subject to bilateral credit risk and potential default | Virtually eliminated via exchange clearinghouse guarantees |
| Liquidity | Illiquid; exiting requires entering an offsetting contract with the original counterparty | Highly liquid; positions can be easily offset in secondary markets prior to maturity |
| Margin Requirements | Typically no daily margin; credit lines and collateral depend on bilateral agreements | Strict initial margin and daily maintenance margin requirements |
| Cash Flow Timing | Single settlement occurs at maturity | Daily cash flows via marking-to-market settlements |
Why Forward and Futures Prices Differ?
In a theoretical world with constant interest rates and no transaction costs, the futures price and the forward price for an asset with the same maturity should be identical. However, in real-world financial markets, forward and futures prices frequently diverge. Understanding why these prices differ requires analyzing several core economic and structural factors.
1. Daily Marking-to-Market and Interest Rate Correlation
The most significant driver of price divergence between forwards and futures is the daily settlement mechanism of futures contracts. Because futures cash flows occur daily, an investor who makes a profit on a futures contract can reinvest those funds immediately at the prevailing risk-free interest rate. Conversely, an investor who incurs a loss must fund the margin call immediately.
When the price of the underlying asset is positively correlated with interest rates, a long futures position is advantageous. When the asset price rises, the investor receives cash daily, which can be reinvested at higher interest rates. When the asset price falls, the investor pays cash when interest rates are lower. Under these conditions, a futures contract will command a higher price than an equivalent forward contract because the daily cash flow profile provides a structural reinvestment advantage.
2. Liquidity and Transaction Costs
Market liquidity plays a critical role in pricing differentials. Standardized futures contracts benefit from deep secondary markets and transparent order books. Market participants can enter and exit positions with minimal bid-ask spreads. Forward contracts, being bilateral OTC agreements negotiated by institutions like Citigroup or Bank of America, often involve wider bid-ask spreads and higher liquidity premiums. These liquidity disparities can introduce minor pricing wedges between the two instruments.
3. Counterparty Credit Risk and Funding Costs
While exchange-clearinghouses eliminate most counterparty risk for futures contracts, OTC forward contracts expose participants to the risk of institutional default. To mitigate this, banks charge credit value adjustments (CVA) and funding value adjustments (FVA) on forward contracts. These risk premiums are embedded into the forward pricing structure, causing forward prices to differ from exchange-traded futures prices, which are insulated by standardized margin and guarantee fund structures.
Real-World Application in Corporate Risk Management
Multinational energy conglomerates and manufacturing giants actively navigate these pricing dynamics. For instance, global energy leaders such as ExxonMobil and BP utilize both futures contracts traded on organized exchanges and customized forward contracts executed through global banking networks to hedge exposure to crude oil, natural gas, and refined products.
When hedging long-term supply commitments that do not match standard exchange expiration dates, corporate hedgers often weigh the liquidity and standardization of futures against the tailored perfection of forward contracts. Recognizing why forward and futures prices diverge allows treasury desks to select the optimal instrument, minimizing financing costs and basis risk.
Conclusion
The pricing and valuation of futures contracts represent a cornerstone of quantitative finance and corporate risk management. While forward and futures contracts share foundational pricing roots via the cost-of-carry model, their operational differences—specifically daily marking-to-market, liquidity premiums, counterparty risk management, and interest rate stochasticity—ensure that forward and futures prices are rarely identical in practice. By mastering these distinctions, financial professionals can accurately value derivative portfolios, optimize corporate hedging strategies, and navigate complex market environments with precision.
