Credit Risk Modeling: Quantitative Frameworks, Structural Models, and Debt Valuation
Modern credit analysis evaluates debt obligations using quantitative metrics, probabilistic rating models, and structural cash flow dynamics. This comprehensive guide covers key concepts in credit risk management, ranging from foundational parameters to advanced valuation frameworks.
Fundamental Credit Parameters and CVA
Credit risk measurement relies on four core parameters that quantify potential counterparty exposure and market value adjustments.
Expected Loss (EL) = Exposure at Default (EAD) × Probability of Default (PD) × Loss Given Default (LGD)
| Credit Parameter | Definition | Key Characteristics & Measurement |
| Expected Exposure (EE) | The projected financial exposure to a counterparty at a future point in time, reflecting market value dynamics. | Accounts for potential future exposure (PFE) driven by market volatility (e.g., swap value changes over time). |
| Probability of Default (PD) | The likelihood that a borrower defaults on its contractual obligations over a specified time horizon. | Estimated via historical default rates, statistical credit scoring, or market-implied CDS spreads. |
| Loss Given Default (LGD) | The percentage of economic loss incurred if a default event occurs: 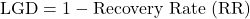 . | Depends heavily on debt seniority, collateral quality, industry distress, and economic cycles. |
| Credit Valuation Adjustment (CVA) | The market value difference between a risk-free bond/derivative and an equivalent credit-risky instrument. | Reflects the price of counterparty credit risk: 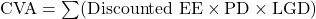 . |
Credit Scores and Credit Ratings
Credit evaluation systems categorize borrowers using ordinal or quantitative metrics to assess default probability across distinct asset classes.
Credit Scores (Consumer & Small Business)
- Focus: Retail borrowers, personal loans, mortgages, and small enterprise loans.
- Methodology: Automated statistical models (e.g., FICO, VantageScore, Altman Z-Score) utilizing historical payment history, credit utilization, debt duration, and recent inquiries.
- Output: Ordinal numerical scale (e.g., 300 to 850).
Credit Ratings (Corporate & Sovereign)
- Focus: Institutional corporate debt, municipal bonds, structured finance, and sovereign issuers.
- Providers: Nationally Recognized Statistical Rating Organizations (NRSROs) such as S&P Global, Moody’s, and Fitch Ratings.
- Categories:
- Investment Grade (IG): AAA / Aaa down to BBB- / Baa3. Features lower default probability and broad institutional eligibility.
- Non-Investment Grade (High Yield / Junk): BB+ / Ba1 down to D. Features higher default probability, wider credit spreads, and lower recovery expectations.
Expected Return Given Credit Rating Transition
Calculating the expected return of a bond undergoing a potential rating transition requires evaluating two components:
- Holding Period Cash Flows & Price Adjustment: Annual coupon plus total return derived from spread changes.
- Transition Probability Weighted Valuation: Summing the probability-weighted end-of-period bond prices across all potential transition states (upgrades, downgrades, defaults).
Bond Return Formula under Rating Transition
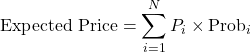
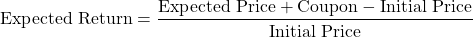
Where  represents the end-of-period bond price calculated using the new credit spread corresponding to rating state
 , modified duration
 , and spread change
 :
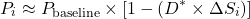
Worked Calculation Example
Consider a 5-year corporate bond with a modified duration of  years, currently rated BBB with a baseline yield of
 and initial price of USD100. Over a 1-year holding period, the bond pays a
 USD coupon. Rating transition probabilities and ending valuations are summarized below:
| Transition State | Rating | Probability (Probi) | Spread Change (ΔSi) | Estimated Ending Price (Pi) | Probability-Weighted Price |
| Upgrade | A |  |  (  ) | 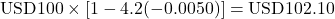 |  |
| Maintain | BBB |  |  (  ) |  |  |
| Downgrade | BB |  |  (  ) | 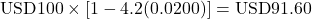 |  |
| Default | D |  | N/A (Recovery =  ) |  |  |
| Total |  | Expected Price: |  |
Calculation Steps:
- Expected Ending Price:
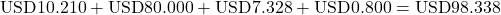
- Total Expected Return:
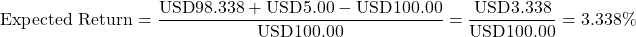
Structural vs. Reduced-Form Credit Models
Corporate credit risk models rely on two distinct mathematical paradigms: option theory on underlying assets (structural) versus stochastic default intensity processes (reduced-form).
                       Structural vs. Reduced-Form Overview
 ┌────────────────────────────────────────┐┌─────────────────────────────────────────┐
│            STRUCTURAL MODELS           │ │     REDUCED-FORM MODELS           │
 │ (e.g., Merton Model)                  │ │ (e.g., Jarrow-Turnbull, Duffie-Lando)   │ │                   │  • Firm's Asset Value (V) is dynamic   │ │  • Default is an exogenous surprise    │
 │  • Default triggers when V < Debt (K)   │ │  • Driven by Hazard Rate / Intensity   │
 │  • Equity = European Call Option        │ │  • Parameters fit directly to markets   │
└─────────────────────────────────────────┘└─────────────────────────────────────────┘| Dimension | Structural Models (Merton Model) | Reduced-Form Models |
| Core Concept | Default is endogenously driven by firm asset value  falling below debt face value  at maturity  . | Default is exogenously driven by a stochastic hazard rate process  . |
| Option Analogy | Equity = European Call Option on firm assets with strike . Debt = Risk-free debt minus put option on assets. | No explicit equity-option analogy; default intensity modeled directly via market inputs. |
| Assumptions | 1. Asset value follows Geometric Brownian Motion. 2. Debt consists of single zero-coupon bond with face value .3. Constant risk-free rate  . | 1. Default intensity depends on macroeconomic variables. 2. Default time is an unobserved stopping time. 3. LGD and default intensity are market-consistent. |
| Strengths | • Clear economic intuition based on balance sheet fundamentals. • Explains structural relationship between equity volatility and credit risk. | • Easily calibrated to real-time market prices (bonds and CDS). • Supports complex debt structures and unobservable asset values. |
| Weaknesses | • Assumes firm assets are continuously traded and observable. • Underestimates short-term credit spreads due to smooth diffusion paths. | • Lacks economic causation explaining why a default occurs. • Requires continuous market data calibration. |
Bond Valuation and Credit Spread Calculation
Credit-risky bond valuation discounts expected future cash flows using survival probabilities ( ) and hazard rates ().
Mathematical Formulation
For default hazard rate  and recovery rate
 :

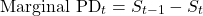
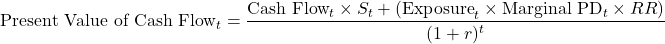
Calculation Example
Consider a 2-year corporate bond with a  annual coupon (par value USD100).
- Risk-free rate ():

- Annual hazard rate ():
 per year
- Recovery rate (): (
 )
Step 1: Compute Probabilities
- Year 1 Survival Probability:
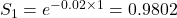 (
 )
- Year 1 Marginal PD:
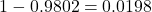 (
 )
- Year 2 Survival Probability:
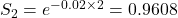 (
 )
- Year 2 Marginal PD:
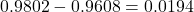 (
 )
Step 2: Valuation Table
| Year (t) | Expected Cash Flow (No Default) | Expected Cash Flow (Default Recovery) | Expected Cash Flow | Discount Factor (1.03)−t | Present Value |
| 1 | 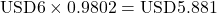 | 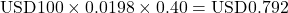 |  |  |  |
| 2 | 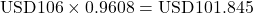 | 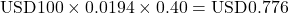 |  |  |  |
| Total | Price =  |
Step 3: Yield to Maturity (YTM) and Credit Spread
- Risk-Free Bond Price (same coupons discounted at ):
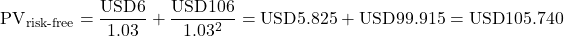
- Risky Bond Yield to Maturity (
 ): Solving
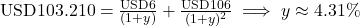
- Credit Spread:
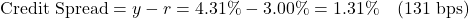
Term Structure of Credit Spreads
The term structure of credit spreads illustrates the relationship between credit spreads and debt maturity across different rating categories.
Determinants of Credit Spread Term Structure
- Credit Quality / Rating Level: High-grade issuers display upward-sloping spread curves, while distressed issuers display flat or inverted curves.
- Business Cycle & Liquidity: Economic contractions widen short-term spreads due to immediate default risk and lower market liquidity.
- Expectations of Future Default Intensity: Cumulative default probabilities increase over time for sound issuers, driving longer-term spreads higher.
Shape Interpretation Matrix
| Curve Shape | Typical Issuer Profile | Underlying Market Dynamics |
| Upward Sloping | Investment Grade (AAA to A) | Low immediate default risk. Spread increases over long horizons as default uncertainty accumulates. |
| Flat / Benchmark | Solid Mid-Tier (BBB) | Default risk is balanced and constant across short- and long-term horizons. |
| Inverted (Downward) | High Yield / Distressed (CCC/CC) | Severe short-term liquidity distress. If the firm survives immediate obligations, long-term survival probability improves. |
Securitized Debt vs. Corporate Debt Credit Analysis
Evaluating structured finance transactions requires distinct analytical techniques compared to traditional corporate debt analysis.
| Feature | Corporate Debt Analysis | Securitized Debt Analysis (ABS / MBS / CLO) |
| Primary Credit Source | Ongoing operational cash flow and enterprise value of an active operating company. | Cash flows generated by a isolated pool of financial assets (mortgages, auto loans, receivables). |
| Bankruptcy Risk | Governed by corporate bankruptcy laws and legal restructuring procedures. | Bankruptcy-Remote: Issued via a Special Purpose Vehicle (SPV) legally isolated from the originator. |
| Credit Enhancement | Corporate guarantees, debt covenants, and asset cross-collateralization. | Tranching & Subordination: Overcollateralization, excess spread, reserve accounts, and waterfall priority rules. |
| Structural Risks | Financial leverage, operating margin compression, management decisions, industry distress. | Prepayment Risk & Call Risk: Contraction risk during falling interest rates and extension risk during rising interest rates. |
| Model Focus | Fundamental financial ratio analysis, balance sheet leverage, and industry position. | Cash flow waterfall simulations, collateral loss modeling, and stress testing prepayment speeds. |
