Financial Analysis Techniques serve as the bedrock of modern corporate decision-making, strategic planning, and equity valuation, enabling corporate leaders, investment analysts, and financial managers to evaluate operational performance and risk profiles.
This definitive guide examines the core analytical frameworks, key liquidity, activity, solvency, and profitability ratios, DuPont return on equity decompositions, sector-specific performance metrics, and financial modeling practices employed by executives and investors across global capital markets.
Core Tools and Techniques Used in Financial Analysis
Financial analysts employ a structured toolkit to convert raw accounting data from balance sheets, income statements, and cash flow reports into actionable intelligence. Each technique provides a distinct perspective on financial health, and sophisticated practitioners combine them to overcome single-tool limitations.
Common-Size Financial Statement Analysis (Vertical Analysis)
Common-size analysis standardizes financial statements by expressing line items as percentages of a core base figure. On the income statement, all entries are divided by total net sales or revenue. On the balance sheet, items are expressed as a percentage of total assets or total liabilities plus equity.
- Primary Uses: Enables direct comparison across companies of vastly different scales, such as comparing Walmart with smaller regional retailers. It highlights structural expense profiles, gross margin efficiency, and capital allocation strategies without distortion from absolute size.
- Key Limitations: Vertical analysis does not reflect macroeconomic price changes, foreign exchange volatility, or differences in accounting choices (such as LIFO versus FIFO inventory valuation).
Horizontal and Trend Analysis
Horizontal analysis evaluates financial metrics across consecutive reporting periods, calculating absolute monetary changes and percentage changes year-over-year or quarter-over-quarter. Multi-year trend analysis establishes baseline compounding growth rates (CAGR) for revenues, margins, and cash generation.
- Primary Uses: Identifies multi-year inflection points, revenue momentum, cost inflation, and working capital expansion. It helps determine whether top-line expansion stems from organic volume growth, pricing power, or M&A activity.
- Key Limitations: Historical trends may not accurately predict future structural shifts in technology, regulation, or consumer preference. Base-year anomalies (such as a single year of high non-recurring expenses) can distort growth rates.
Ratio Analysis
Ratio analysis quantifies mathematical relationships between specific financial line items across balance sheets, income statements, and cash flow reports. Ratios are grouped into activity, liquidity, solvency, and profitability categories to assess operational trade-offs.
- Primary Uses: Facilitates rapid benchmarking against industry peer averages and historical performance. It converts complex financial statements into clear operational indicators.
- Key Limitations: Ratios rely on historical accounting values rather than current market replacement costs. Differing fiscal year-ends, aggressive revenue recognition, and off-balance-sheet financing can obscure underlying corporate reality.
Cash Flow Dynamics Analysis
Cash flow analysis examines the quality of earnings by evaluating cash generated from operations relative to reported net income. It measures free cash flow (FCF), capital allocation discipline, and operating cash conversion cycles.
- Primary Uses: Reveals whether reported profits are backed by actual cash inflows or driven by accrual accounting timing. It measures a company’s ability to fund capex, debt service, and shareholder dividends without external dilution.
- Key Limitations: Free cash flow fluctuates due to major capital investment timing, working capital swings, and inventory stocking cycles, requiring multi-year normalization.
Sensitivity and Scenario Analysis
Sensitivity and scenario modeling test how changes in key underlying variables—such as interest rates, raw material costs, sales volumes, or foreign currency exchange rates—impact net earnings and liquidity.
- Primary Uses: Quantifies operational leverage, financial risks, and downside capital protection. It allows management teams to stress-test capital projects before deploying funds.
- Key Limitations: Models rely on assumptions regarding variable correlations that may break down during severe market stress or systemic economic crises.
| Financial Analysis Technique | Core Primary Purpose | Key Operational Benefit | Notable Analytical Limitation |
| Common-Size Analysis | Structural standardization | Enables cross-sectional peer scale comparisons | Masks absolute scale and inflation impacts |
| Horizontal Trend Analysis | Temporal growth measurement | Identifies structural inflection points over time | Distorted by historical base-year anomalies |
| Ratio Analysis | Operational relationship benchmarking | Isolates liquidity, leverage, and efficiency drivers | Vulnerable to accounting policy divergence |
| Cash Flow Analysis | Earnings quality verification | Detects accrual accounting mismatches | High quarterly capital expenditure volatility |
| Sensitivity Analysis | Stress-testing forward assumptions | Quantifies exposure to external macroeconomic shocks | Relies on historical variable correlations |
Calculation and Interpretation of Core Financial Ratios
Evaluating corporate performance requires applying precise formulas across four foundational ratio categories: activity, liquidity, solvency, and profitability.
Activity Ratios (Efficiency Metrics)
Activity ratios evaluate how efficiently a company manages its operational assets and working capital balance sheet accounts.
- Inventory Turnover Ratio: Measures the frequency with which inventory is sold and replaced during a period.
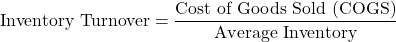
- Days Sales of Inventory (DSI): Indicates the average number of days inventory remains in stock before sale.
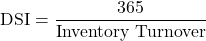
- Days Sales of Inventory (DSI): Indicates the average number of days inventory remains in stock before sale.
- Receivables Turnover Ratio: Evaluates the efficiency of trade credit collections.
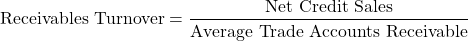
- Days Sales Outstanding (DSO): Measures the average collection period for receivables.
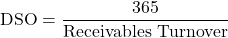
- Days Sales Outstanding (DSO): Measures the average collection period for receivables.
- Payables Turnover Ratio: Quantifies how quickly a company pays its trade suppliers.
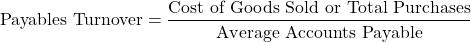
- Days Payable Outstanding (DPO): Reflects the average credit duration granted by suppliers.
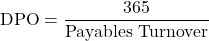
- Days Payable Outstanding (DPO): Reflects the average credit duration granted by suppliers.
- Total Asset Turnover: Measures the revenue generated per unit of capital deployed in assets.
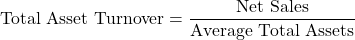
Interpretation: High inventory turnover and low DSO indicate efficient inventory management and effective customer collections. However, an excessively high inventory turnover may signal inventory shortages and missed sales opportunities, while an overly aggressive DSO policy could alienate creditworthy buyers.
Liquidity Ratios (Short-Term Solvency Metrics)
Liquidity ratios measure a company’s ability to meet short-term financial obligations without seeking external rescue capital.
- Current Ratio: Measures total current assets relative to total current liabilities.
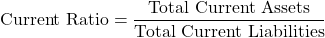
- Quick Ratio (Acid-Test Ratio): Excludes less liquid assets, such as inventory and prepaid expenses, from current assets.
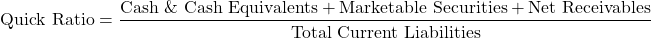
- Cash Ratio: Assesses short-term debt coverage using only highly liquid cash reserves.
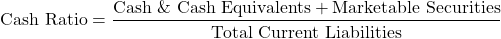
- Cash Conversion Cycle (CCC): Tracks the overall duration (in days) required to convert capital spent on raw inventory back into operational cash receipts.
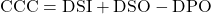
Interpretation: A current ratio above 1.5 to 2.0 generally indicates comfortable short-term liquidity. However, tech companies such as Apple and lean retailers like Walmart often operate with low or negative working capital and negative cash conversion cycles. They collect customer cash immediately while negotiating extended supplier payment terms (high DPO), effectively using supplier credit to fund daily operations.
Solvency Ratios (Long-Term Capital Structure Metrics)
Solvency ratios measure long-term financial stability, capital structure mix, and corporate debt service capabilities.
- Debt-to-Equity Ratio (D/E): Measures total contractual liabilities relative to shareholder equity capital.
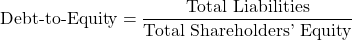
- Financial Leverage Ratio (Equity Multiplier): Measures total asset coverage relative to shareholder equity.
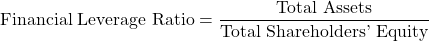
- Interest Coverage Ratio (Times Interest Earned): Assesses the safety cushion for making debt interest payments out of operating income.
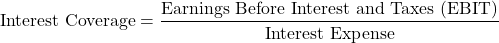
Interpretation: Capital-intensive industries, such as global energy firms like Shell, routinely operate with high debt loads to support long-term physical assets. However, an interest coverage ratio falling below 2.5 to 3.0 during economic downturns signals distress risk, as fixed debt service obligations can erode profitability.
Profitability Ratios (Operating Efficiency Metrics)
Profitability ratios measure a firm’s ability to convert revenues into net income and generate returns on invested capital.
- Gross Profit Margin: Measures the production efficiency of core products before indirect overhead expenses.
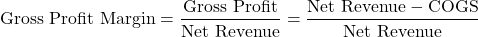
- Operating Profit Margin (EBIT Margin): Measures profitability after operating expenses, including depreciation, SG&A, and R&D.
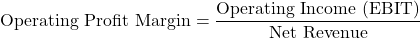
- Net Profit Margin: Reflects bottom-line profitability attributable to equity owners after all taxes and interest expenses.
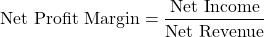
- Return on Assets (ROA): Measures operating efficiency relative to total corporate assets deployed.
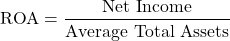
- Return on Equity (ROE): Quantifies total net accounting returns earned on shareholder capital.
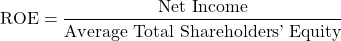
| Ratio Category | Ratio Name | Mathematical Formula | Core Analytical Focus |
| Activity | Inventory Turnover | 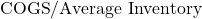 | Supply chain velocity |
| Activity | Days Sales Outstanding (DSO) | 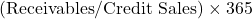 | Receivable collection speed |
| Liquidity | Current Ratio | 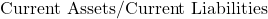 | General short-term debt buffer |
| Liquidity | Quick Ratio | 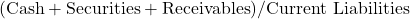 | Immediate liquid asset coverage |
| Solvency | Debt-to-Equity (D/E) | 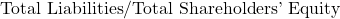 | Capital structure leverage |
| Solvency | Interest Coverage | 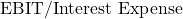 | Debt service safety margin |
| Profitability | Gross Margin | 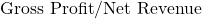 | Direct product pricing power |
| Profitability | Net Margin | 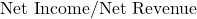 | Bottom-line profit retention |
| Profitability | Return on Equity (ROE) | 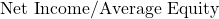 | Capital return efficiency |
Interrelationships Among Financial Ratios and Holistic Corporate Evaluation
Financial ratios should not be analyzed in isolation. Effective financial analysis examines how these metrics interact across operational, liquidity, leverage, and profit dimensions.
Trade-Offs Between Liquidity and Profitability
Holding excess cash balances and short-term liquid securities improves current and quick liquidity ratios, reducing short-term default risk. However, cash yields lower returns than long-term physical assets, core R&D, or growth acquisitions. Consequently, excessive liquidity can drag down total asset turnover, Return on Assets (ROA), and overall Return on Equity (ROE). Executive teams must strike a balance between maintaining liquidity for risk management and reinvesting capital to drive profit growth.
Volume-Margin Trade-Offs (High-Velocity vs. High-Margin Business Models)
Comparative financial analysis highlights two distinct operating strategies across industries:
- High-Volume, Low-Margin Model: Retailers such as Walmart operate with narrow net profit margins (often 2% to 3%). They generate high Return on Equity by driving high inventory turnover, high total asset turnover, and optimized working capital management.
- High-Margin, Lower-Velocity Model: Luxury goods manufacturers, enterprise software providers, and consumer technology firms like Apple generate strong returns through high gross margins (often exceeding 45% to 50%) and high net margins, which offset lower asset-to-sales ratios.
Working Capital Optimization and Cash Conversion Dynamics
An improving Cash Conversion Cycle (CCC) positively impacts liquidity and profitability. For example, extending supplier payment terms (higher DPO) increases operating cash flows without adding financial debt. Conversely, if extending DPO strains vendor relationships or causes missed early-payment discounts, direct goods costs may rise, eroding gross profit margins.
DuPont Analysis of Return on Equity: Components and Sensitivity
DuPont analysis breaks Return on Equity (ROE) into its underlying financial drivers. By separating ROE into distinct components, analysts can determine whether high returns stem from strong operational profitability, efficient asset management, or financial leverage.
The Three-Stage DuPont Decomposition
The 3-stage DuPont model divides Return on Equity into three core drivers: net profit margin, total asset turnover, and financial leverage (the equity multiplier).
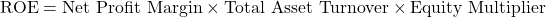
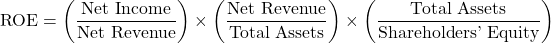
3-Stage Demonstration Example:
Consider a global manufacturing corporation with the following annual consolidated results:
- Net Revenue: USD100,000,000
- Net Income: USD10,000,000
- Total Assets: USD80,000,000
- Shareholders’ Equity: USD40,000,000
- Net Profit Margin:
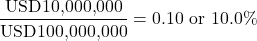
- Total Asset Turnover:
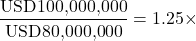
- Equity Multiplier (Financial Leverage):
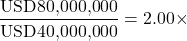
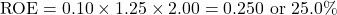
Verification:
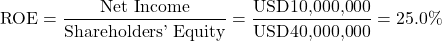
The Five-Stage DuPont Decomposition
The 5-stage DuPont model further separates net margin into tax burden, interest burden, and operating profit margin (EBIT margin), isolating the impacts of tax planning, financing costs, and core operations.
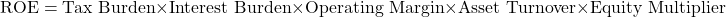
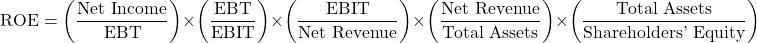
5-Stage Demonstration Example:
Assume the same enterprise expanded its financial disclosures with the following details:
- Net Revenue: USD100,000,000
- Operating Income (EBIT): USD20,000,000
- Annual Debt Interest Expense: USD4,000,000
- Earnings Before Taxes (EBT):
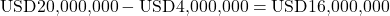
- Effective Corporate Income Tax Rate:
 (
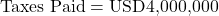 )
- Net Income:
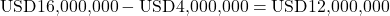
- Total Assets: USD100,000,000
- Shareholders’ Equity: USD50,000,000
- Tax Burden:
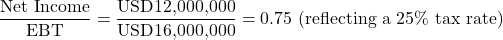
- Interest Burden:
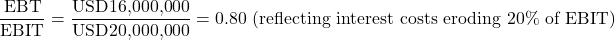
- Operating Profit Margin:
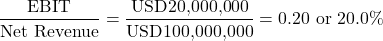
- Total Asset Turnover:
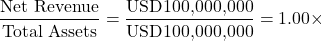
- Equity Multiplier:
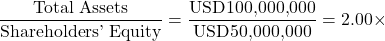
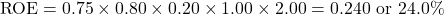
Verification:
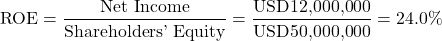
Component Sensitivity and Strategic Interpretation
Evaluating changes in DuPont components allows analysts to assess the quality and sustainability of a firm’s ROE.
| Scenario / Strategy Shift | Tax Burden | Interest Burden | Operating Margin | Asset Turnover | Financial Leverage | Overall Impact on ROE & Risk Profile |
| Core Operating Efficiency Improvement | Unchanged | Unchanged | Increases ( ) | Increases () | Unchanged | High-Quality Growth: Higher margins and faster turnover drive ROE without adding financial risk. |
| Debt-Funded Share Buyback Program | Unchanged | Decreases ( ) | Unchanged | Unchanged | Increases ( ) | Financial Engineering: Higher leverage boosts ROE, but increased interest expense raises default risk. |
| Aggressive Price Discounting Campaign | Unchanged | Unchanged | Decreases () | Increases () | Unchanged | Volume-Margin Trade-Off: Neutral to negative impact if margin decline outweighs volume gains. |
Major enterprise software corporations like Microsoft maintain high Return on Equity primarily through high operating margins and high asset turnover in cloud services, rather than relying on balance sheet leverage.
Industry-Specific Ratios in Corporate Financial Analysis
Standard financial ratios may not fully capture operating performance in specialized sectors. Analysts use targeted industry metrics to evaluate key performance drivers in these markets.
Retail and E-Commerce
- Same-Store Sales Growth (Comp Sales): Measures revenue growth from existing retail locations open for at least one year, excluding expansion effects.
- Sales per Square Foot: Measures physical retail floor efficiency.
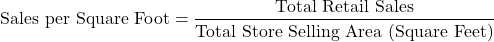
Banking and Financial Institutions
Because commercial banks such as JPMorgan Chase use debt and deposits as core operating assets, traditional liquidity and leverage ratios are less applicable.
- Net Interest Margin (NIM): Measures the net return on earning assets.
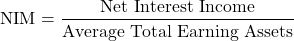
- Non-Performing Loan (NPL) Ratio: Evaluates asset quality and credit risk exposure.
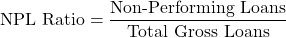
- Efficiency Ratio: Measures operating overhead relative to revenue.
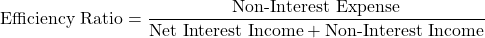
Real Estate Investment Trusts (REITs)
Because GAAP depreciation expenses artificially lower reported net income for real estate owners, REIT analysts use modified cash flow metrics.
- Funds From Operations (FFO): Adjusts net income for real estate depreciation and property sales gains/losses.
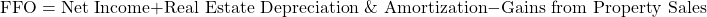
- Adjusted Funds From Operations (AFFO): Deducts recurring capital expenditures required to maintain properties.
Software-as-a-Service (SaaS) and Technology
- Annual Recurring Revenue (ARR): Measures annualized subscription contract value.
- Net Revenue Retention (NRR): Measures recurring revenue expansion from existing customers after accounting for churn and downgrades.
- LTV/CAC Ratio: Compares Customer Lifetime Value (LTV) to Customer Acquisition Cost (CAC), with ratios above 3.0
 indicating sustainable unit economics.
| Sector | Specialty Financial Ratio | Primary Measurement Focus | Operational Benchmark Standard |
| Retail | Same-Store Sales Growth | Organic retail store revenue expansion | Positive real growth above inflation |
| Banking | Net Interest Margin (NIM) | Yield spread earned on lending assets | Sector averages range between 2.5% and 3.5% |
| REITs | Funds From Operations (FFO) | Real estate operating cash generation | Preferred over net income for dividend coverage |
| SaaS | Net Revenue Retention (NRR) | Expansion and retention within customer accounts | Target metrics exceed 110% to 120% |
| Aviation | Revenue per Available Seat Mile | Passenger yield and capacity pricing | Must exceed Cost per Available Seat Mile (CASM) |
| Energy | Reserve Replacement Ratio | Sustainability of proven energy reserves | Target ratio exceeds 100% annually |
Earnings Modeling, Driver-Based Forecasting, and Pro Forma Financial Statements
Financial analysis techniques are forward-looking tools used to construct pro forma financial models and forecast future corporate earnings.
Driver-Based Revenue Forecasting
Rather than applying simple percentage growth assumptions, driver-based models break revenue down into operational components:
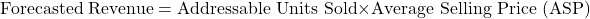
In subscription models, revenue forecasts incorporate starting subscriber counts, new user acquisitions, churn rates, and average revenue per user (ARPU):
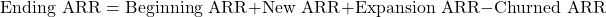
Integrating Pro Forma Statements
A complete financial model links the three core financial statements to maintain accounting balance across historical and projected periods:
- Income Statement Integration: Revenue forecasts drive variable COGS and operating expenses. Operating profit (EBIT) then informs tax and interest calculations.
- Balance Sheet Linking: Working capital accounts (receivables, inventory, payables) are projected using target activity ratio drivers (DSO, DSI, DPO). Net income feeds into retained earnings, while planned capital expenditures update property, plant, and equipment (PPE).
- Cash Flow Statement Balancing: Operating cash flow is calculated by adjusting pro-forma net income for non-cash expenses and working capital changes. The resulting net cash position updates balance sheet cash, ensuring accounting balance.
Regression Analysis and Financial Stress-Testing
Financial analysts use statistical regression analysis to evaluate relationships between macroeconomic indicators—such as GDP growth, interest rate shifts, and consumer confidence—and corporate sales volume.
During stress-testing, analysts adjust core operational drivers, such as reducing revenue growth by 15% while increasing debt financing costs by 200 basis points. This evaluates liquidity cushions, debt covenant compliance, and earnings volatility under adverse economic conditions.
Conclusions and Strategic Summary
Financial Analysis Techniques provide corporate leaders, investors, and advisors with the quantitative frameworks required to assess business performance, allocate capital efficiently, and model future profitability. Standard tools—including common-size statements, ratio analysis, DuPont decompositions, and driver-based financial models—convert accounting disclosures into actionable strategic insights.
By combining activity, liquidity, solvency, and profitability metrics with industry-specific indicators, analysts can evaluate the operational trade-offs driving corporate returns. As business models evolve across global markets, combining rigorous ratio analysis with dynamic pro forma forecasting remains essential for managing risk and driving long-term enterprise value creation.
