Financial reporting quality plays a paramount role in maintaining global capital market efficiency, protecting equity investors, and upholding corporate governance standards. High financial reporting quality ensures that financial disclosures deliver relevant, decision-useful, and transparent information that faithfully represents an enterprise’s underlying operational reality and financial performance.
Conversely, low financial reporting quality distorts economic truth, obscures operational vulnerabilities, and leads to severe capital misallocation across financial markets.
This comprehensive business article analyzes the core tenets of financial reporting quality, contrasting it with the quality of reported results, examining the full spectrum of reporting integrity, contrasting conservative and aggressive accounting choices, uncovering executive motivations and conducive fraud conditions, evaluating disciplining mechanisms, detailing non-GAAP presentation tactics, explaining specific balance sheet and income statement manipulation techniques, and highlighting vital warning signs for audit committees and financial analysts.
Comparing Financial Reporting Quality with Quality of Reported Results
To assess corporate performance accurately, financial analysts and business leaders must distinguish between financial reporting quality and the quality of reported financial results. Although these two concepts are interdependent, they address fundamentally different dimensions of corporate disclosures.
Defining Financial Reporting Quality and Results Quality
Financial reporting quality refers to the degree to which a company’s financial statements adhere to established accounting standards, such as International Financial Reporting Standards (IFRS) or US Generally Accepted Accounting Principles (US GAAP), and faithfully portray the economic transactions of the reporting period. High financial reporting quality requires transparency, completeness, relevance, and neutrality. It provides decision-useful information that enables investors and creditors to evaluate a company’s past performance and forecast its future cash flows accurately.
In contrast, the quality of reported results focuses on the economic sustainability, profitability, and financial condition of the business itself. It evaluates whether the reported earnings, cash flows, and balance sheet items reflect sustainable, repeatable, and high-return operational activities, rather than temporary market spikes, accounting anomalies, or high-risk business models.
Quality of Earnings, Cash Flow, and Balance Sheet Items
Evaluating the quality of reported results requires a granular examination across three core financial statements:
- Quality of Earnings: High-quality earnings are generated through recurring core business activities, exhibit low artificial volatility, are backed by cash flow, and are unlikely to reverse in subsequent reporting periods. Low-quality earnings rely heavily on non-operating gains, asset revaluations, changes in accounting estimates, or temporary cost-cutting measures.
- Quality of Cash Flow: High-quality cash flows derive primarily from steady operating activities rather than unsustainable working capital liquidation, delayed accounts payable, aggressive receivable factoring, or financing activities disguised as operational inflows.
- Quality of Balance Sheet: High-quality balance sheet items reflect conservative asset valuations, low financial leverage, transparent impairment testing, minimal off-balance-sheet commitments, and clear solvency metrics.
The relationship between reporting quality and results quality creates four distinct analytical scenarios, detailed in the table below:
| Reporting Quality Level | Results Quality Level | Analytical Implication and Corporate Reality | Real-World Corporate Example |
| High | High | Transparent disclosures reflecting strong, sustainable, cash-backed earnings and robust balance sheet solvency. | Apple Inc. maintains conservative revenue recognition, transparent segment disclosures, and massive cash flow generation. |
| High | Low | Transparent and compliant disclosures that faithfully report underlying business distress, earnings decline, or operational risks. | A traditional retailer transparently reporting declining same-store sales and taking clear, immediate inventory write-downs. |
| Low | High | Structurally strong operating performance obscured by opaque, non-compliant, or overly complex financial statement presentations. | A fast-growing tech firm with high organic sales growth using poor segment breakdown disclosures or non-standard revenue metric definitions. |
| Low | Low | Misleading or aggressive accounting choices designed to conceal deteriorating business fundamentals, poor cash flows, or insolvency. | Wirecard AG used fabricated trustee accounts to conceal severe operational losses and missing cash reserves totaling EUR1.9 billion (~USD2.1 billion). |
Spectrum for Assessing Financial Reporting Quality
Evaluating financial reporting quality requires recognizing that accounting disclosures exist on a continuum ranging from high-integrity, decision-useful financial statements to outright financial fraud. Financial analysts classify corporate reporting along this spectrum to gauge the reliability of reported financial numbers.
[ High Quality ]  =======================================================>  [ Fraudulent ]
   Decision-Useful     Biased Choice     Earnings Management     Non-GAAP     Outright Falsification
    & Sustainable       (Aggressive/         (Real/Accrual)      Distortions    (Fictitious Data)
     Financials        Conservative)
The financial reporting spectrum comprises five primary categories:
High-Quality, Decision-Useful Financial Statements
The company provides transparent, neutral, and complete disclosures in full compliance with IFRS or US GAAP. Reported results reflect sustainable operational economics, clear cash flow generation, and conservative balance sheet valuations.
Compliant Financial Statements with Biased Accounting Choices
The financial statements comply with official accounting standards but employ deliberately aggressive or conservative accounting choices. Management selects estimates and policies to slant reported results toward a desired earnings trajectory while remaining within legal boundaries.
Compliant Financial Statements with Active Earnings Management
Management complies with standard accounting rules but actively uses accrual manipulation or real transaction timing (e.g., slashing research and development spending at year-end or discounting inventory) to alter reported earnings, smooth income, or meet earnings-per-share (EPS) targets.
Non-Compliant Disclosures and Misleading Non-GAAP Presentations
Financial reporting departs from fundamental accounting principles or overuses non-standard, non-GAAP metrics designed to obscure core operational underperformance, underlying debt obligations, or recurring cash burn.
Fraudulent Financial Reporting
The financial report features deliberate non-compliance, fabricated sales, non-existent assets, altered documents, or unrecorded liabilities. This represents a complete breakdown of financial reporting quality.
| Spectrum Tier | Characteristics of Disclosures | Impact on Analyst Evaluation | Primary Financial Risk |
| Tier 1: High Quality | Neutral, transparent, GAAP/IFRS compliant, fully backed by organic cash flow. | High confidence in valuation models and earnings forecasts. | Minimal accounting risk; standard market risk applies. |
| Tier 2: Biased Choice | Fully compliant, but management systematically chooses aggressive options. | Earnings power may be inflated; future margin compression likely. | Reversal of aggressive accruals in future periods. |
| Tier 3: Earnings Management | Legal rules stretched; real business operations altered to meet short-term EPS targets. | Distorts operational efficiency and long-term capital allocation. | Impairment of long-term competitiveness due to deferred expenditure. |
| Tier 4: Misleading Non-GAAP | Heavy emphasis on custom metrics excluding core, recurring operational costs. | Requires significant analytical adjustments to reconstruct real earnings. | Mispricing of equity; hidden leverage and solvency risks. |
| Tier 5: Fraudulent Reporting | Fictitious revenue, unrecorded liabilities, forged bank confirmations. | Financial statements are worthless for economic analysis. | Complete loss of invested equity, SEC enforcement, bankruptcy. |
Conservative versus Aggressive Accounting Practices
The selection of accounting policies and management estimates dictates whether a firm’s financial reporting leans toward conservatism or aggressiveness. Neither extreme represents pure neutrality, but understanding the distinction is vital for comparative financial analysis.
Aggressive Accounting
Aggressive accounting involves selecting accounting choices, estimates, and deferral methods designed to inflate current-period reported earnings, operating cash flows, or asset balances, while deferring expenses and liabilities into future periods.
- Revenue Recognition: Recognizing revenue before performance obligations are fully satisfied, accelerating unearned contract revenue, or recording gross revenue instead of net agency commissions.
- Expense Deferral: Capitalizing routine operational and maintenance costs as long-term intangible or fixed assets, thereby amortizing expenses over multiple years rather than expensing them immediately.
- Useful Life & Residual Values: Extending the estimated useful lives of plant, property, and equipment (PP&E) to minimize annual depreciation charges.
- Loss Provisions: Underestimating allowances for doubtful accounts, loan loss reserves, or inventory obsolescence provisions.
Conservative Accounting
Conservative accounting chooses accounting policies and estimates that recognize expenses and potential losses immediately while deferring the recognition of revenues and gains until they are fully realized.
- Immediate Expensing: Expensing technology development, software customization, and pre-opening costs immediately as incurred.
- High Reserve Allocation: Maintaining high bad-debt reserves, warranty provisions, and inventory write-down allowances during strong economic periods.
- Accelerated Depreciation: Applying accelerated depreciation methods (such as double-declining balance) to recognize larger expenses in early asset years.
Impact on Multi-Period Financial Results
While aggressive accounting inflates current-period profits, it creates an inevitable future earnings cliff. As capitalized expenses accumulate on the balance sheet, future depreciation, amortization, and write-downs erode future margins. Conversely, conservative accounting depresses initial reported profits but creates “cookie-jar reserves” that can cushion earnings during economic downturns, obscuring true performance volatility.
Motivations and Conducive Conditions for Low-Quality Financial Reports
Understanding why executives manipulate financial reporting quality requires examining both internal management pressures and external market environments.
Management Motivations for Low-Quality Reporting
Executives encounter severe structural incentives to issue financial reports that lack transparency or manipulate economic results:
- Capital Market Expectations: Failing to meet Wall Street analyst consensus quarterly EPS estimates by even USD0.01 can trigger severe equity price declines. Management frequently manages earnings to preserve valuation multiples.
- Executive Compensation Structure: Executive incentive bonuses, equity grants, and stock options are often tied directly to target EPS, return on equity (ROE), or revenue growth thresholds.
- Debt Covenant Compliance: Companies carrying high leverage must maintain minimum debt service coverage ratios or maximum leverage thresholds specified in credit agreements to avoid technical default.
- Corporate Transactions and Fundraising: Firms preparing for Initial Public Offerings (IPOs), secondary equity offerings, or debt issuances have strong incentives to inflate reported margins and balance sheet strength.
- Career Protection: Senior executives face termination or reputational damage when corporate turnarounds stall, incentivizing them to conceal deteriorating business lines.
Conditions Conducive to Low-Quality or Fraudulent Reporting
Low-quality financial reporting thrives under specific operational and governance environments. The classic Fraud Triangle framework identifies three mandatory elements:
                  [ INCENTIVE / PRESSURE ]
                  /                      \
                 /                        \
                /                          \
 [ OPPORTUNITY ] -------------------------- [ RATIONALIZATION ]
Opportunity
Weak internal accounting controls, complex corporate structures with numerous international subsidiaries, ineffective board audit committees, complex related-party transactions, and high management discretion over critical accounting estimates create structural opportunities for financial manipulation.
Incentive or Pressure
Intense competitive industry pressures, declining product demand, excessive debt loads, rapid technological obsolescence, or severe macroeconomic downturns generate intense pressure on management to conceal poor performance.
Attitude or Rationalization
An uncompromised tone at the top, where executive leadership prioritizes short-term stock gains over ethical compliance, enables managers to rationalize improper practices as temporary measures needed to protect shareholder value.
A notable example occurred at Toshiba Corporation, where an independent investigation revealed that top executive leadership set aggressive profit targets (“Challenges”) across divisions. Division managers systematically overstated operating profits by JPY151.8 billion (~USD1.2 billion) over seven years by manipulating percentage-of-completion cost estimates in infrastructure projects and delaying loss recognition.
Similarly, Luckin Coffee Inc. experienced a major breakdown in reporting quality when management fabricated USD310 million in revenue between April 2019 and January 2020 by forging corporate coupon transactions. This fraudulent reporting was driven by intense pressure to maintain post-IPO growth expectations. The discovery led to delisting and a USD180 million SEC fraud settlement.
Mechanisms Disciplining Financial Reporting Quality and Their Limitations
To safeguard global financial markets, multiple institutional mechanisms exist to discipline financial reporting quality. However, each mechanism contains structural limitations that sophisticated manipulators can exploit.
Governance, Audit, and Regulatory Disciplining Mechanisms
Regulatory Frameworks and Enforcement
Government agencies, such as the US Securities and Exchange Commission (SEC) and the UK Financial Reporting Council (FRC), enforce compliance with accounting standards, mandate disclosure filings, and impose civil penalty fines or criminal prosecutions for reporting violations.
Independent External Audits
Public accounting firms conduct independent audits under Auditing Standards to issue an opinion on whether financial statements are presented fairly, in all material respects, in accordance with GAAP or IFRS.
Corporate Audit Committees
Independent audit committees, composed of non-executive board directors, oversee management’s financial reporting process, monitor internal controls, and hire independent external auditors.
Capital Market Participants
Sell-side analysts, institutional investors, short sellers, credit rating agencies, and financial journalists scrutinize corporate disclosures, identifying accounting anomalies and penalizing low-quality reporters through stock downgrades or short positions.
Structural Limitations of Disciplining Mechanisms
Despite multi-layered oversight, disciplining mechanisms face persistent real-world constraints:
- Auditor Conflicts of Interest: External audit firms are compensated by the companies they audit. Fearing client loss or seeking lucrative non-audit consulting mandates can weaken auditor independence.
- Sample-Based Auditing Limitations: External audits rely on statistical sampling and selective testing rather than inspecting 100% of corporate transactions, allowing sophisticated balance sheet manipulation to pass undetected.
- Board and Audit Committee Capture: Audit committee members may lack technical accounting expertise or rely entirely on management-provided summaries, impairing their ability to challenge aggressive accounting estimates.
- Regulatory Lag: Regulatory enforcement actions typically occur years after financial reporting fraud has damaged public investors, offering minimal real-time investor protection.
The collapse of Wirecard AG highlights these limitations. External auditors repeatedly issued clean audit opinions despite persistent warnings from short sellers and financial journalists regarding unverified escrow balances in Asia, demonstrating how audit sampling and information asymmetry can impair disciplining oversight.
Presentation Choices and Non-GAAP Measures Influencing Analyst Opinions
Corporate executives frequently utilize discretionary presentation choices within regulatory boundaries to project favorable financial trends and influence analyst perception.
Misuse of Non-GAAP Alternative Performance Measures
Companies increasingly highlight non-GAAP (or non-IFRS) financial measures in earnings releases and investor presentations. While non-GAAP metrics like “Adjusted EBITDA”, “Core Operating Profit”, or “Free Cash Flow before Restructuring” are intended to clarify underlying operational trends, they can be weaponized to conceal weak results.
Common presentation tactics include:
- Excluding Recurring Operating Charges: Arbitrarily stripping out recurring cash items, such as annual employee stock-based compensation (SBC), acquisition integration expenses, restructuring fees, or litigation settlements, framing them as “one-off, non-recurring events.”
- Asymmetric Exclusions: Excluding losses or write-downs from non-GAAP figures while retaining one-off gains, asset sales, or tax credits in adjusted operating income.
- Redefining Free Cash Flow: Calculating free cash flow by adding back capitalized software expenditure or excluding equipment financing cash outflows.
Segment Aggregation and Classification Tactics
Management possesses discretion over how operating segments are reported:
- Opaque Segment Aggregation: Combining underperforming or loss-making business lines with highly profitable divisions into a single broad reporting segment, masking revenue drops in core units.
- Operating versus Non-Operating Line Item Placement: Shifting core operating expenses (such as logistics or administrative overhead) down the income statement into non-operating lines, artificially inflating reported Operating Income and Gross Margin.
In 2020, General Electric Company agreed to pay a USD200 million penalty to settle SEC charges regarding misleading disclosures in its Power and Insurance divisions. The SEC found that GE Power generated nearly half of its 2017 operating profit by modifying prior cost estimates and monetizing unbilled receivables internally through GE Capital, without transparently disclosing these practices to public investors. Furthermore, Bausch Health Companies Inc. (formerly Valeant Pharmaceuticals) relied on aggressive non-GAAP adjustments to mask underlying debt pressures and core pharmaceutical sales declines.
Accounting Methods for Managing Earnings, Cash Flow, and Balance Sheet Items
Management can manipulate financial statements across all three core statements using discretionary accounting choices, timing shifts, and subjective estimates.
Earnings Management Techniques
Earnings management involves altering reported net income to achieve desired financial targets:
- Premature Revenue Recognition: Recognizing sales prior to full performance obligation completion under IFRS 15 / ASC 606, such as shipping goods to distributors with undisclosed return rights (“channel stuffing”) or billing customers before delivery (“bill-and-hold” arrangements).
- Percentage-of-Completion Abuse: Overestimating the stage of completion on long-term construction or software implementation contracts to accelerate current revenue and defer estimated cost overruns.
- Cost Capitalization: Deferring current operational costs by classifying them as long-term balance sheet assets. This was demonstrated when WorldCom capitalized USD3.8 billion in routine line costs as capital expenditures.
- Provision and Reserve Manipulation: Adjusting bad debt provisions, inventory reserves, or legal liabilities up or down depending on whether current income needs to be suppressed or boosted.
Cash Flow Management Techniques
Although cash flow from operations (CFO) is often viewed as immune to accrual manipulation, management can artificially inflate reported CFO:
- Cash Flow Reclassification: Classifying routine operating cash outflows as investing cash outflows (e.g., capitalizing software development costs) or reclassifying financing inflows as operating receipts.
- Supplier Payables Stretching: Deliberately delaying vendor payments past period-end to boost operating cash flow artificially, followed by rapid cash disbursements in the next quarter.
- Reverse Factoring and Supply Chain Finance: Utilizing third-party financial institutions to pay suppliers while recording the obligation as trade payables rather than bank debt, hiding true leverage while preserving reported CFO.
- Receivable Monetization: Selling accounts receivable to financial institutions without recourse just prior to period-end, accelerating cash inflows from future periods into current CFO.
Balance Sheet Management Techniques
Balance sheet management focuses on concealing financial leverage and inflating asset valuations:
- Off-Balance-Sheet Structures: Utilizing Special Purpose Entities (SPEs), joint ventures, or variable interest entities to hold debt obligations and distressed assets off the consolidated balance sheet.
- Impairment Delays: Refusing to write down impaired goodwill, software intangibles, or obsolete inventory, preserving reported asset totals and equity value.
- Lease Classification Shifts: Structuring commercial leases to avoid capitalization where permitted, understating lease liabilities.
Accounting Warning Signs and Methods for Detecting Information Manipulation
To protect capital, financial analysts and audit committees employ quantitative models and forensic accounting techniques to detect low-quality financial reporting and potential manipulation.
Key Red Flags in Financial Statements
Systematic manipulation of financial reports leaves distinct operational and financial traces. Key warning signs include:
- Divergence Between Earnings and Operating Cash Flow: Net income growing consistently while operating cash flow stagnates or drops is a clear red flag for aggressive accrual manipulation.
- Surging Days Sales Outstanding (DSO): Accounts receivable growing significantly faster than total revenue indicates premature revenue recognition, aggressive credit terms, or uncollectible sales.
- Decelerating Inventory Turnover: Inventory accumulation outstripping revenue growth points to product obsolescence, deferred inventory write-downs, or improper overhead capitalization.
- Frequent Accounting Policy Changes: Repeated changes in depreciation schedules, revenue recognition methods, or asset reserve estimates without clear business justifications.
- Unexplained Growth in Asset Accounts: Rapid increases in vague balance sheet lines such as “Other Current Assets”, “Unbilled Receivables”, or “Capitalized Soft Costs.”
- Abnormal Executive and Auditor Turnover: Sudden resignations of Chief Financial Officers, internal audit leaders, or external independent auditors.
Quantitative Detection Frameworks and Models
Financial analysts use established statistical models to evaluate corporate financial reporting quality:
Beneish M-Score Model
The Beneish M-Score is a mathematical model utilizing eight accounting ratios to calculate the statistical probability that a company has manipulated its reported earnings. An M-Score greater than -1.78 indicates a high probability of financial manipulation.
The model evaluates:
- DSRI (Days Sales in Receivables Index): Measures the ratio of DSO in year
 to year
 . A large increase indicates revenue acceleration.
- GMI (Gross Margin Index): Compares gross margins. Deteriorating margins increase pressure to manipulate earnings.
- AQI (Asset Quality Index): Measures the proportion of non-current assets that are not tangible PP&E. A rising AQI signals improper cost capitalization.
- SGI (Sales Growth Index): Tracks revenue growth momentum. High-growth firms face greater pressure when growth slows.
- DEPI (Depreciation Index): Compares depreciation rates. A DEPI greater than 1 indicates extending asset lives to boost income.
- SGAI (Sales, General, and Administrative Expenses Index): Evaluates SG&A efficiency relative to sales.
- LVGI (Leverage Index): Measures total debt to total assets ratio changes to assess balance sheet leverage pressure.
- TATA (Total Accruals to Total Assets): Measures net income minus operating cash flow divided by total assets. High positive accruals signal low earnings quality.
Altman Z-Score Model
The Altman Z-Score assesses corporate bankruptcy risk using five financial ratios (Working Capital/Total Assets, Retained Earnings/Total Assets, EBIT/Total Assets, Market Value of Equity/Total Liabilities, and Sales/Total Assets). A declining Z-Score highlights financial distress, increasing management incentives to issue low-quality financial reports.
Cash Flow to Net Income Ratio Analysis
Tracking the multi-year ratio of Operating Cash Flow to Operating Income (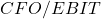 ) provides a continuous gauge of reporting integrity. Ratios persistently below 1.0 indicate that reported operating profits are not translating into actual cash.
Conclusion
Financial reporting quality represents the foundation of institutional trust, capital allocation, and governance across global business markets. Evaluating corporate performance requires looking beyond top-line revenue growth and diluted EPS figures to assess the integrity, neutrality, and sustainability of reported financial numbers.
As demonstrated by real-world corporate collapses—from Wirecard AG and Toshiba Corporation to SEC enforcement actions at General Electric Company and Luckin Coffee Inc.—low financial reporting quality destroys corporate value, exposes investors to capital losses, and undermines market stability.
To navigate complex financial statements effectively, executive leaders, audit committees, and professional financial analysts must combine thorough accounting policy analysis with quantitative forensic tools like the Beneish M-Score, scrutinize non-GAAP adjustments, track cash flow conversions, and maintain a rigorous analytical skepticism. Safeguarding capital market integrity requires continuous vigilance over financial reporting quality at every level of corporate governance.
