In modern global finance, Portfolio Management: Institutional (SWF) represents the pinnacle of multi-generational asset stewardship, enterprise risk governance, and complex multi-asset construction.
Managing sovereign wealth funds (SWFs), state pension plans, and large-scale public endowments requires balancing long-term wealth preservation, financial risk mitigation, liquidity engineering, and rigorous ethical and ESG compliance across global capital markets.
As sovereign institutions like Norges Bank Investment Management, China Investment Corporation, Public Investment Fund, and Abu Dhabi Investment Authority oversee portfolios exceeding USD1.00 trillion each, mastering advanced techniques in Portfolio Management: Institutional (SWF) is essential for fund managers, policy advisors, and investment executives worldwide.
Financial Risks in Institutional Portfolio Management
Institutional investors face complex financial risks that can undermine long-term capital preservation and target purchasing power if not identified and quantified accurately. In the context of Portfolio Management: Institutional (SWF), financial risks originate from broad market movements, counterparty exposures, interest rate shifts, currency fluctuations, and macro-inflationary dynamics.
Market and Interest Rate Risk
Market risk represents the systematic exposure of equity, fixed income, and private asset holdings to macroeconomic contractions, geopolitical conflicts, and broader volatility spikes. For sovereign funds with perpetual investment horizons, market risk must be differentiated between short-term mark-to-market fluctuations and permanent loss of capital.
Interest rate risk impacts fixed-income duration and equity valuations. Institutional portfolios with extended fixed-income durations experience substantial capital erosion during aggressive rate-tightening cycles. Institutional managers calculate modified duration and key-rate durations across the yield curve to measure sensitivity to non-parallel yield curve shifts:
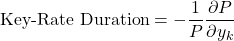
Currency and Inflation Risk
Currency risk is paramount for commodity-funded SWFs, such as Middle Eastern funds or the Norwegian Government Pension Fund Global managed by Norges Bank Investment Management. When a fund collects revenue in local currency or foreign commodity proceeds (such as crude oil traded in USD) but finances domestic fiscal budgets, unhedged foreign exchange volatility directly affects domestic purchasing power.
Inflation risk poses a structural threat to real returns. Sovereign wealth funds aiming for a real return target of 4.00% above inflation must construct portfolios containing inflation-hedging assets, such as inflation-linked bonds (TIPS), infrastructure, commodities, and real estate.
Credit and Counterparty Risk
Credit risk encompasses default risk, credit migration risk, and credit spread widening across public corporate bonds, private debt, and derivative counterparties. Institutional managers monitor Credit Default Swap (CDS) spreads and Expected Loss (EL) metrics:
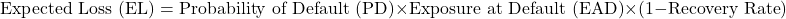
Financial Risk Exposures and Mitigation Strategies
| Financial Risk Category | Primary Exposure Metric | Portfolio Source | Mitigation Strategy | Institutional Benchmark Example |
| Market Risk | Value at Risk (VaR), Expected Shortfall (ES) | Global equities, high-yield credit, private equity | Multi-asset diversification, defensive options overlay, dynamic beta hedging | MSCI World Index, FTSE All-World |
| Interest Rate Risk | Duration, Key-Rate Duration, Convexity | Sovereign debt, investment-grade corporate bonds | Interest rate swaps, treasury futures duration matching, laddered maturities | Bloomberg Global Aggregate Index |
| Currency Risk | FX Volatility, Tracking Error against FX basket | Cross-border equity, direct foreign real estate | Passive FX forward overlay, natural liability matching, strategic currency basket | Custom FX Basket (USD, EUR, JPY, GBP) |
| Credit Risk | Credit Spreads, Default Probabilities, Loss Given Default | Private credit, emerging market debt, OTC derivatives | Credit derivatives (CDS), strict rating mandates, ISDA/CSA agreements | Markit CDX, iTraxx Indexes |
| Inflation Risk | Real Return Spreads, CPI Correlation | Cash, Nominal fixed-income instruments | Real assets (infrastructure, timberland), TIPS, floating-rate debt | Real Return Mandates (CPI + 4.00%) |
Environmental and Social Risks in Sovereign Strategies
Environmental and social (E&S) risks have evolved from qualitative concerns into material financial factors for institutional asset owners. In modern Portfolio Management: Institutional (SWF), failing to address climate transition, environmental degradation, and human rights issues exposes sovereign funds to regulatory sanctions, asset stranding, and severe reputation loss.
Transition and Physical Climate Risks
Climate risks are classified into physical risks and transition risks:
- Physical Risks: Direct operational disruptions and capital destruction caused by extreme weather events, rising sea levels, and changing agricultural yield patterns. Physical risks hit direct real estate, agriculture, and infrastructure investments.
- Transition Risks: Financial losses stemming from legal, technological, and market shifts during the transition to a low-carbon economy. Hydrocarbon-reliant SWFs face dual exposures: domestic fiscal revenues drop when oil prices decline, and legacy fossil fuel holdings risk becoming stranded assets.
Social Risk and License to Operate
Social risks include labor standard violations, community displacement, privacy breaches, and poor human capital practices within portfolio companies. Sovereign funds like Government Pension Investment Fund (GPIF) of Japan, which manages over USD1.60 trillion in assets, integrate social indicators (such as workforce diversity, supply chain auditing, and health and safety metrics) into their active manager evaluations and index selection processes.
Evaluating non-financial risk requires integrating qualitative ESG scorecards into quantitative Risk-Adjusted Return on Capital (RAROC) frameworks. Institutional investors utilize Scenario Analysis based on NGFS (Network for Greening the Financial System) pathways to stress-test assets under  ,
 , and
 warming scenarios.
Managing Risks in Long-Term Direct Investments
Direct investments in private equity, core infrastructure, and real estate are central to Portfolio Management: Institutional (SWF) strategies aimed at capturing excess returns. However, direct investments lack the daily liquidity, standardized oversight, and mark-to-market pricing of public assets. Institutional asset owners, such as Singapore’s Temasek Holdings and GIC, deploy specialized structural tools to mitigate execution, operational, and illiquidity risks.
Governance Rights and Board Representation
Direct institutional investors demand structural governance protections in shareholder agreements, including:
- Board Representation and Veto Power: Securing board seats and veto rights over capital expenditures, debt issuance, strategic mergers, and management compensation.
- Tag-Along and Drag-Along Rights: Protecting minority ownership positions during third-party acquisition offers.
- Anti-Dilution Clauses: Utilizing weighted-average or full-ratchet anti-dilution protections to shield equity value during down-rounds.
Capital Staging and Co-Investment Structures
Institutional investors mitigate early-stage execution risk by staging capital commitments. Rather than disbursing USD500 million upfront, capital calls are conditioned on reaching pre-defined operational and cash-flow milestones. Co-investing alongside established private equity sponsors allows institutions like Canada Pension Plan Investment Board (CPPIB) to gain direct asset exposure while leveraging general partner (GP) underwriting expertise, reducing fee drag from standard 2-and-20 fee structures.
Enterprise Risk Management Systems for Institutional Asset Owners
An Enterprise Risk Management (ERM) system provides an overarching framework to identify, aggregate, measure, and govern risks across all asset classes, business units, and operational subsidiaries of a sovereign investor.
Strengths and Weaknesses of Enterprise Risk Management Systems
While robust ERM systems strengthen institutional oversight, structural weaknesses can emerge if models operate in silos or rely on outdated assumptions:
- Strengths:
- Holistic Risk Aggregation: Consolidates market, credit, operational, liquidity, and ESG risks across public and private portfolios into single executive dashboards.
- Alignment with Risk Appetite Statements: Ensures investment managers operate strictly within parameters mandated by sovereign boards and parliament.
- Multi-Asset Stress Testing: Simulates catastrophic tail events (such as stagflation shocks or global banking crises) across equities, fixed income, real estate, and derivatives simultaneously.
- Weaknesses:
- Model Risk and Historical Correlation Breakdown: ERM engines rely on historical covariance matrices that break down during severe market stress, when asset correlations approach 1.00.
- Illiquid Asset Valuation Lag: Private market valuations update quarterly or annually, creating an artificial smoothing effect that conceals true risk exposure in ERM engines.
- Bureaucratic Rigidity: Excessive compliance layers can slow execution, preventing investment teams from seizing tactical opportunities.
Recommendations for ERM System Enhancement
To address these vulnerabilities, sovereign board directors and chief risk officers should implement three core upgrades:
- Deploy Forward-Looking Scenario Generators: Supplement backward-looking Value at Risk (VaR) calculations with stochastic, forward-looking Monte Carlo stress tests incorporating climate transition and geopolitical shock variables.
- Implement De-Smoothed Valuation Frameworks: Apply statistical de-smoothing algorithms (such as the Geltner-Ngo approach) to private equity and real estate appraisals before feeding assets into ERM risk engines.
- Integrate Real-Time Operational Risk Monitoring: Connect automated trade monitoring, cybersecurity threat detection, and counterparty credit surveillance into a unified risk dashboard.
Liquidity Risk Management and the Illiquidity Premium
Managing liquidity risk is a foundational pillar of Portfolio Management: Institutional (SWF). Institutional portfolios must maintain sufficient liquidity to fulfill fiscal transfer mandates, meet capital calls for private commitments, pay pension benefits, and manage collateral variations on derivative positions.
Portfolio Liquidity Tiering Structure
Institutional investors divide assets into distinct liquidity buckets based on transaction settlement timelines and market impact costs:
- Tier 1: High-Liquidity Buffer (0–5 Days Settlement): Cash equivalents, short-term sovereign treasury bills, and liquid developed-market government bonds. Reserved for immediate spending requirements, margin calls, and sudden capital calls.
- Tier 2: Secondary Liquidity (5–30 Days Settlement): Developed-market large-cap equities, liquid corporate bonds, and exchange-traded funds (ETFs). Usable for dynamic rebalancing and medium-term operational funding.
- Tier 3: Illiquid Real Assets (3 Months to 10+ Years Lock-up): Private equity, venture capital, direct real estate, forestry, and core infrastructure investments.
Capturing the Illiquidity Premium
The illiquidity premium represents the excess return demanded by investors to compensate for locking up capital in non-public, illiquid assets. For long-term investors like Abu Dhabi Investment Authority (managing over USD1.10 trillion) and China Investment Corporation (managing USD1.57 trillion), holding large Tier 3 asset allocations allows funds to harvest an expected annualized illiquidity premium of 1.50% to 3.50% above comparable public market benchmarks.
Asset Class Liquidity Spectrum and Illiquidity Premium Analysis
| Asset Class | Settlement Horizon | Lock-up / Commitment Period | Expected Illiquidity Premium | Primary Liquidity & Risk Management Tools |
| Sovereign Cash & T-Bills | Same-day (T+0) | None | 0.00% (Baseline Benchmark) | Sweep accounts, overnight repurchase agreements (repos) |
| Public Developed Equities | Standard (T+1) | None | 0.00% (Liquid Market) | Derivative overlays, ETF rebalancing, liquid futures execution |
| Direct Core Infrastructure | 6–18 Months | 10 to 25 Years | 1.50% – 2.50% per annum | Credit facility lines, co-investment syndication, milestone funding |
| Private Equity Buyouts | 3–12 Months | 7 to 12 Years | 2.50% – 3.50% per annum | Secondary market stake sales, distribution-in-kind management |
| Direct Commercial Real Estate | 3–9 Months | 5 to 10 Years | 1.50% – 2.00% per annum | Debt refinancing, JV recapitalization, pre-leased anchor tenants |
Asset Allocation and Portfolio Construction
Strategic Asset Allocation (SAA) establishes the long-term target weights across global asset classes, serving as the primary driver of institutional risk and return profiles. Aligning SAA with spending commitments and return targets requires balancing mean-variance efficiency with downside liquidity constraints.
Portfolio Optimization Framework
Institutional portfolio construction solves for expected utility while accounting for liability or expenditure obligations:
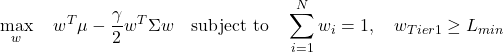
Where  represents vector weights,
 represents expected asset returns,
 is the variance-covariance matrix,
 is the risk aversion parameter, and
 is the minimum required Tier 1 liquidity buffer.
Addressing Identified Portfolio Mismatches
When portfolio monitoring reveals structural mismatches—such as an over-allocation to illiquid private assets relative to upcoming spending mandates—institutional managers should execute targeted corrective steps:
- Re-tier Liquidity Buffers: Adjust capital deployment schedules by reducing new private equity fund commitments while redirecting quarterly distributions back into Tier 1 liquid Treasuries.
- Utilize Secondary Private Markets: Sell seasoned private equity LP positions on secondary markets (often at small discounts to Net Asset Value) to quickly raise liquid cash reserves.
- Deploy Contingent Liquidity Lines: Establish pre-negotiated syndicated revolving credit facilities at the fund holding company level to meet sudden capital calls without forcing asset sales during market drawdowns.
Ethical Governance and Standards in Manager Selection
Sovereign wealth funds and pension boards delegate trillions of dollars to external asset managers worldwide. Maintaining strict ethical standards and avoiding conflicts of interest during manager selection is vital for institutional credibility and compliance with global codes of conduct, such as those published by the CFA Institute.
Independence and Objectivity (Standard I(B))
Individuals involved in institutional manager selection must maintain absolute independence and objectivity. Acceptable practices require:
- Zero Compensation / Gifts: Board members, chief investment officers, and consultant advisors must reject lavish entertainment, gifts, or travel accommodation from asset managers bidding for mandates.
- Prohibition of Pay-to-Play Practices: Mandating that asset managers certify they have made no political contributions or placement fee kickbacks to trustees or government officials to win public mandates.
Conflicts of Interest and Transparency (Standard VI(A) & VI(B))
- Full Conflict Disclosure: Selection committee members must immediately disclose any personal ownership, family connection, or previous employment relationship with bidding fund managers and recuse themselves from voting.
- Soft-Dollar Transparency: External equities managers must explicitly account for any soft-dollar research credits generated from institutional commission flows, ensuring that client brokerage commissions directly benefit the asset owner portfolio.
- Objective RFP Matrices: Utilizing standardized Request for Proposal (RFP) scoring frameworks based strictly on verifiable track records, operational due diligence (ODD), fee structures, and risk-adjusted alpha generation.
Derivatives vs. Cash Market Techniques in Exposure Management
Institutional investors frequently modify asset allocations, adjust risk factors, or hedge market risks. Deciding between physical cash market transactions (buying/selling underlying securities) and derivative overlays (futures, options, swaps) involves evaluating transaction costs, market impact, execution speed, and balance sheet leverage.
Comparative Cost-Benefit Framework
Cash market adjustments require selling physical securities (e.g., USD5.00 billion of global equities) and transferring proceeds into alternative assets (e.g., sovereign bonds). This process incurs bid-ask spreads, custody settlement fees, potential cross-border capital gains taxes, and significant market impact costs.
Conversely, establishing exposure via derivative contracts (such as synthetic futures or total return swaps) requires minimal upfront cash (initial margin of 3.00% to 10.00%), reducing execution drag while maintaining liquidity in base cash holdings.
Cash Market Transactions vs. Derivative Overlay Strategies
| Parameter | Cash Market Transactions (Physical Execution) | Derivative Overlay Strategies (Futures, Swaps, Options) |
| Upfront Capital Required | 100% of nominal position value | 3% to 10% (Initial margin requirement) |
| Transaction & Execution Costs | High (brokerage commissions, stamp duties, FX conversion) | Very Low (tight bid-ask spreads, low exchange clearing fees) |
| Market Impact | Substantial for multi-billion dollar trades | Minimal due to high liquidity in exchange-traded derivatives |
| Counterparty Credit Risk | Negligible (settled via DvP deliver-versus-payment) | Requires ongoing management (ISDA/CSA bilateral collateralized margin) |
| Operational & Tax Complexity | High (global cross-border tax reclaim, multi-custody settlement) | Medium to High (daily margin management, roll-risk governance) |
| Long-Term Asset Ownership | Full voting rights, direct corporate action control | No proxy voting rights; synthetic exposure only |
Derivative Overlays in Tactical Asset Allocation and Rebalancing
Tactical Asset Allocation (TAA) involves taking short- to medium-term positions away from Strategic Asset Allocation (SAA) targets to exploit market mispricings. Derivative overlays enable institutional managers to execute TAA shifts and systematic rebalancing rapidly without disrupting underlying physical asset managers.
Equitizing Cash and Duration Adjustments
When institutional portfolios receive large cash inflows (such as quarterly sovereign oil revenues or corporate dividend distributions), uninvested cash creates cash drag. Institutional managers equitize cash by entering long index futures positions (e.g., S&P 500 or Euro Stoxx 50 futures), matching equity market returns immediately while maintaining operational cash reserves.
Similarly, fixed-income duration can be adjusted dynamically using interest rate swaps or Treasury futures overlays:
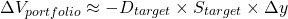
Where  is target duration,
 is portfolio scale, and
 is expected yield movement.
Synthetic Rebalancing Architecture
During major market shifts (e.g., equities surging while bonds decline), a portfolio’s equity weight may exceed SAA policy limits (e.g., rising from 50.00% to 58.00%). Rather than forcing external equity managers to liquidate underlying stock holdings—which triggers capital gains taxes and manager disruption—the institutional overlay desk sells equity index futures and buys interest rate futures. This synthetic rebalancing returns the portfolio to target weights instantly at a fraction of standard cash execution costs.
ESG Considerations in Managing Long-Term Institutional Portfolios
Integrating Environmental, Social, and Governance (ESG) criteria into long-term institutional strategies has shifted from voluntary stewardship to a core risk-management discipline. Sovereign funds and global asset managers like BlackRock recognize that long-term sustainable returns depend on resilient social and ecological systems.
Active Ownership vs. Negative Exclusion
Institutional investors deploy two primary ESG implementation strategies:
- Active Ownership and Engagement: Asset owners utilize vote execution, shareholder resolutions, and direct executive dialogues to push portfolio companies toward net-zero targets and enhanced ESG reporting. Sovereign leaders like Norges Bank Investment Management publish clear voting guidelines and engage directly with board chairs across thousands of global companies annually.
- Negative Exclusion Screening: Explicitly barring investments in companies or sectors that violate fund values or international treaties (e.g., controversial weapons, tobacco, thermal coal mining, or persistent human rights violators).
Double Materiality and Regulatory Alignment
Institutional funds increasingly adopt the principle of double materiality, assessing both how ESG trends affect financial portfolio value (financial materiality) and how portfolio assets impact broader society and the environment (environmental materiality). Funds align reporting structures with international frameworks, such as the Task Force on Climate-related Financial Disclosures (TCFD) and International Sustainability Standards Board (ISSB) standards, ensuring full transparency for government overseers, capital markets, and public stakeholders.
Conclusion
Mastering Portfolio Management: Institutional (SWF) requires a multi-faceted approach that integrates sophisticated financial risk measurement, enterprise risk governance, structured liquidity management, and active ESG stewardship. As sovereign wealth funds and global pension institutions navigate shifting interest rate regimes, structural inflation pressures, and energy transition dynamics, maintaining financial discipline and high ethical standards remains vital. By balancing derivative overlay techniques with physical cash market allocations, capturing illiquidity premiums in private markets, and maintaining robust Enterprise Risk Management systems, institutional investors can protect public wealth and deliver sustainable multi-generational returns.
