Financial Reporting of Long-Term Liabilities and Equity forms the bedrock of modern corporate financial accounting, providing investors, executive decision-makers, and credit rating agencies with critical insights into an enterprise’s structural capital obligations and long-term solvency.
The balance sheet presentation and corresponding disclosures of complex commitments—such as operating and finance leases, defined benefit pension plans, and executive equity awards—directly affect key valuation metrics, debt covenant calculations, and corporate tax strategies.
This article delivers a comprehensive analysis of the accounting treatments under International Financial Reporting Standards (IFRS) and US Generally Accepted Accounting Principles (US GAAP) for long-term debt, lease structures, retirement plans, and share-based compensation, illustrating key concepts with real-world corporate financial data from global market leaders.
Accounting for Leases: Lessee and Lessor Perspectives
Lease accounting underwent a fundamental global transformation with the issuance of IFRS 16 (Leases) and Financial Accounting Standards Board (FASB) Accounting Standards Codification (ASC) Topic 842 (Leases). These standards eliminated off-balance-sheet operating lease accounting for lessees, ensuring that virtually all long-term lease obligations are recognized directly on the balance sheet as Right-of-Use (ROU) assets and corresponding lease liabilities.
Lessee Financial Reporting under IFRS 16 and ASC 842
From the lessee’s perspective, a lease transfers the right to control the use of an identified asset for a specific period of time in exchange for consideration. At lease commencement, the lessee measures the lease liability at the present value of the remaining lease payments, discounted using the interest rate implicit in the lease or, if that rate cannot be readily determined, the lessee’s incremental borrowing rate. Concurrently, the lessee capitalizes an ROU asset equal to the initial lease liability, adjusted for any lease payments made at or before commencement, initial direct costs incurred, and lease incentives received.
While IFRS 16 applies a single-lessee model treating all leases as financing arrangements, ASC 842 retains a dual classification model for lessees:
- Finance Leases (ASC 842) / All Leases (IFRS 16): The lessee recognizes front-loaded expense profiles. Depreciation (or amortization) of the ROU asset is recorded straight-line over the shorter of the asset’s useful life or lease term, while interest expense on the lease liability declines over time as the principal is amortized.
- Operating Leases (ASC 842): The lessee recognizes a single, straight-line lease expense on the income statement combining ROU asset amortization and interest cost, maintaining parity with traditional operating lease expense profiles while preserving full balance sheet recognition.
A practical example of lessee accounting is demonstrated by global carrier Delta Air Lines, Inc. In its fiscal 2024 financial reporting, Delta reported operating lease ROU assets of USD6,644 million (comprising USD2,910 million in fleet assets and USD3,734 million in ground facilities and equipment) alongside total lease liabilities of USD7,424 million across operating and finance categories. Delta reported annual operating lease costs of USD974 million and variable lease costs of USD2,902 million, illustrating the scale of capital commitments brought onto the corporate balance sheet under ASC 842.
Lessor Financial Reporting: Classification and Income Recognition
Lessor accounting under both standard frameworks hinges on whether the contract transfers substantially all the risks and rewards incidental to ownership of the underlying physical asset. Lessors classify leases into three distinct categories:
- Operating Leases: The underlying asset remains on the lessor’s balance sheet and continues to be depreciated over its estimated useful life. Rental income is recognized straight-line over the lease term.
- Sales-Type Leases: Transferred when control of the underlying asset passes to the lessee, meeting any of five criteria (such as ownership transfer, bargain purchase options, lease term covering the major part of economic life, or present value of payments meeting or exceeding substantially all fair value). The lessor derecognizes the underlying asset, recognizes a net investment in the lease (present value of lease payments plus unguaranteed residual value), and records immediate selling profit or loss.
- Direct Financing Leases (US GAAP): Applicable when risks and rewards are transferred, but control is not passed to the lessee, and third-party credit enhancements are present. Selling profit is deferred and recognized over the lease term via interest income.
A classic global enterprise operating as a primary lessor is McDonald’s Corporation. McDonald’s owns a vast global real estate portfolio and leases land and buildings to franchise operators. The company acts as a primary lessor under operating lease arrangements, generating multi-billion-dollar recurring rental revenue streams that are recognized straight-line over long-term franchise terms.
Comparative Overview of Lease Accounting
| Lease Dimension | Lessee (IFRS 16) | Lessee (ASC 842 – Finance) | Lessee (ASC 842 – Operating) | Lessor (Operating) | Lessor (Sales-Type) |
| Balance Sheet Assets | ROU Asset | ROU Asset | ROU Asset | Property, Plant & Equipment | Net Investment in Lease |
| Balance Sheet Liabilities | Lease Liability | Lease Liability | Lease Liability | Unearned Rent (if prepaid) | None (Derecognized asset) |
| Income Statement Impact | Amortization + Interest Expense | Amortization + Interest Expense | Single Operating Lease Expense | Rental Income – Depreciation | Immediate Gain/Loss + Interest Income |
| Cash Flow Classification | Principal (Financing), Interest (Operating/Financing) | Principal (Financing), Interest (Operating) | Operating Cash Outflow | Operating Cash Inflow | Capital Outflow / Operating Inflow |
Financial Reporting of Employee Benefits and Share-Based Compensation
Human capital management requires corporate entities to structure sophisticated retirement and equity compensation schemes. Financial reporting for these arrangements requires precise actuarial measurements for pension obligations and complex fair value option pricing models for share-based awards under ASC 718 and IFRS 2.
Defined Contribution Plans vs. Defined Benefit Plans
Retirement plan reporting is divided by the allocation of investment and longevity risks between the employer and the employee.
Defined Contribution (DC) Plans
Under defined contribution plans (such as 401(k) arrangements in the United States or superannuation schemes in Australia), the employer’s obligation is strictly limited to an agreed-upon periodic contribution to an independent fund. Financial reporting is straightforward: the employer recognizes a periodic expense equal to the required contribution earned by employees during the accounting period. If contributions remain unpaid at period-end, a current liability is recorded. Neither actuarial assumptions nor balance sheet asset/liability remeasurements are required, as the investment risk rests entirely with the plan participant.
Defined Benefit (DB) Plans
Defined benefit plans guarantee specified post-employment payments calculated via formulas linked to employee tenure, salary progression, and retirement age. The employer bears both investment and actuarial risks. Accounted for under IAS 19 (Employee Benefits) and ASC 715 (Compensation – Retirement Benefits), DB accounting requires estimating the Projected Benefit Obligation (PBO) or Defined Benefit Obligation (DBO) using actuarial assumptions including discount rates, salary growth rates, employee turnover, and mortality tables.
The net funded status reported on the balance sheet reflects the difference between the fair value of plan assets and the PBO/DBO:
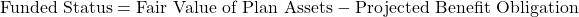
If the PBO exceeds plan assets, a net defined benefit liability is recognized; if plan assets exceed the PBO, a net defined benefit asset is recorded (subject to asset ceiling caps).
Net Periodic Pension Cost recognized in the income statement includes the following structural components:
- Service Cost: Present value of benefits earned by employees during the current period (operating cost).
- Interest Cost: Accrual of interest on the PBO using the chosen actuarial discount rate.
- Expected Return on Plan Assets: Deducted from pension cost (under US GAAP) based on expected long-term asset return rates.
- Remeasurements & Actuarial Gains/Losses: Under IFRS (IAS 19), actuarial gains and losses and actual return on assets exceeding discount rates are recognized immediately in Other Comprehensive Income (OCI) and are never recycled to profit or loss. Under US GAAP (ASC 715), actuarial gains and losses can be deferred in Accumulated Other Comprehensive Income (AOCI) and amortized into income over time using the corridor approach.
Industrial titan The Boeing Company illustrates the material financial weight of defined benefit obligations. In its fiscal 2024 Form 10-K disclosures, Boeing reported an Accumulated Benefit Obligation (ABO) for its pension plans of USD53,671 million. Managing pension obligations of this scale requires extensive actuarial updates to reflect shifting interest rate regimes, as small fluctuations in corporate bond yield discount rates can shift reported net liabilities by billions of dollars.
Stock-Based Compensation Plans
Share-based compensation aligns employee and executive incentives with long-term shareholder returns. Accounting for share-based payments is governed by ASC 718 (Compensation – Stock Compensation) and IFRS 2 (Share-based Payment).
Classification: Equity-Settled vs. Cash-Settled Awards
- Equity-Settled Awards: Include Restricted Stock Units (RSUs), Performance Share Units (PSUs), and employee stock option grants settled in common equity shares. Compensation expense is measured based on the grant-date fair value of the equity instruments and recognized over the requisite service period (vesting period) with a corresponding credit to Additional Paid-in Capital (APIC) within equity. Subsequent changes in share price do not alter the recognized total compensation cost.
- Cash-Settled Awards: Include Stock Appreciation Rights (SARs) settled in cash. The award is recorded as a liability and remeasured at fair value at each reporting date until settlement, with changes in fair value recognized immediately in operating profit.
Fair Value Measurement and Valuation Frameworks
For stock options, grant-date fair value is estimated using option-pricing models such as the Black-Scholes-Merton (BSM) formula or binomial lattice models. Key inputs include the grant-date stock price, strike price, risk-free interest rate, expected dividend yield, expected option term, and expected stock price volatility. For performance awards with market-based conditions (e.g., Total Shareholder Return targets), Monte Carlo simulations are deployed to estimate fair value at the grant date.
Global technology leader Microsoft Corporation relies heavily on share-based incentive plans to attract and retain top software engineering talent. In its fiscal year 2024 Annual Financial Report, Microsoft reported stock-based compensation expense of USD10,734 million, up from USD9,611 million in fiscal 2023. This non-cash expense added USD10,734 million back into operating cash flows while increasing stockholders’ equity, which reached USD268,477 million at fiscal year-end 2024 (including USD173,144 million in retained earnings).
Similarly, European software leader SAP SE accounts for its employee share purchase plans and long-term incentive (LTI) schemes under IFRS 2, reporting share-based payments across its global management reports to reflect alignment between total rewards and shareholder value creation.
Comparison of Retirement and Share-Based Compensation Accounting
| Feature | Defined Contribution (DC) | Defined Benefit (DB) | Equity-Settled Share Compensation | Cash-Settled Share Compensation |
| Primary Standard | IAS 19 / ASC 715 | IAS 19 / ASC 715 | IFRS 2 / ASC 718 | IFRS 2 / ASC 718 |
| Valuation Metric | Contribution due | Present value of PBO/DBO minus Plan Assets | Grant-date fair value (BSM / Monte Carlo) | Period-end mark-to-market fair value |
| Balance Sheet Impact | Accrued payable (if unpaid) | Net defined benefit liability or asset | APIC credit (Shareholders’ Equity) | Current or non-current liability |
| P&L Impact Pattern | Periodic contribution expense | Service cost, interest, returns, OCI amortization | Amortized straight-line over vesting period | Periodically adjusted for stock price fluctuations |
| Actuarial / Market Risk | Employee bears risk | Employer bears risk | Fixed at grant date (no equity remeasurement) | Employer bears stock volatility risk |
Financial Statement Presentation and Disclosures of Long-Term Liabilities and Equity
Rigorous financial reporting requires that long-term commitments and share equity transactions are clearly presented across the face of financial statements and supported by detailed footnote disclosures.
Balance Sheet Structuring and Classification Rules
Long-term liabilities must be clearly separated between current maturities (obligations due within 12 months or operating cycle) and non-current obligations.
+---------------------------------------------------------------------------------+
|                           CONSOLIDATED BALANCE SHEET                            |
+---------------------------------------------------------------------------------+
| NON-CURRENT LIABILITIES:                                                        |
|   Long-Term Debt, net of current maturities & unamortized issuance costs       |
|   Non-Current Operating Lease Liabilities                                       |
|   Non-Current Finance Lease Liabilities                                         |
|   Net Defined Benefit Pension Obligations                                       |
|   Deferred Corporate Tax Liabilities                                            |
|                                                                                 |
| STOCKHOLDERS' EQUITY:                                                           |
|   Common Stock (Par Value)                                                      |
|   Additional Paid-in Capital (APIC) [Includes Share-Based Compensation Credit]  |
|   Retained Earnings                                                             |
|   Accumulated Other Comprehensive Income (Loss) (AOCI) [DB Plan Remeasurements] |
|   Treasury Stock (at Cost)                                                      |
+---------------------------------------------------------------------------------+
Presentation Principles
- Long-Term Debt: Debt issuance costs are presented as a direct deduction from the carrying amount of the related debt liability (rather than deferred assets). Senior debt, convertible notes, and debentures are disaggregated when material.
- Lease Liabilities: Operating and finance lease liabilities must be presented separately from standard funded debt, either on the face of the balance sheet or within footnote disaggregation.
- Shareholders’ Equity: Capital accounts explicitly track common stock at par, APIC originating from equity-settled compensation and stock issuances, cumulative retained earnings, and AOCI containing pension actuarial adjustments and cash flow hedge gains/losses.
Footnote Disclosures for Long-Term Liabilities
Regulatory disclosures mandated by the US Securities and Exchange Commission (SEC) and International Accounting Standards Board (IASB) require qualitative and quantitative note disclosures:
- Maturity Schedules: A 5-year rollout of contractual debt principal repayments and undiscounted lease commitments, followed by a reconciliation of undiscounted cash flows to present values recorded on the balance sheet.
- Interest Rates & Covenants: Details regarding coupon rates, effective interest rates, collateral pledged, and restrictive financial debt covenants (e.g., maximum leverage ratios, minimum interest coverage).
- Lease Discount Assumptions: Disclosure of the weighted-average remaining lease term and weighted-average discount rate applied across operating and finance lease portfolios.
Consumer technology leader Apple Inc. provides clear examples of disclosures regarding long-term liabilities and share-based compensation. In its fiscal 2024 Form 10-K (for the fiscal year ended September 28, 2024), Apple disclosed term debt obligations alongside commercial paper issuances, detailing maturity schedules ranging from one to thirty years, coupon rates, and effective interest rate swaps. Apple’s disclosures outline capital return allocations, combining billions in annual stock repurchases with equity grant disclosures under its restricted stock unit plans.
Footnote Disclosures for Share-Based Compensation
To prevent hidden equity dilution, ASC 718 and IFRS 2 mandate comprehensive footnote disclosures regarding share incentive programs:
- Methodology and Valuation Assumptions: Disclosures outlining option pricing models (BSM or Binomial) and specific weighted-average inputs: risk-free rates, volatility, expected life, and dividend yields.
- Activity Schedules: Reconciliation of options/RSUs outstanding at the beginning of the period, granted, forfeited, exercised, and expired, along with weighted-average grant-date fair values.
- Unrecognized Compensation Expense: Total unrecognized compensation cost related to non-vested awards and the weighted-average period over which that expense is expected to be recognized.
- Intrinsic Value: Total intrinsic value of options exercised and RSUs vested during the fiscal year.
Required Disclosure Matrix
| Financial Instrument | Mandatory Quantitative Footnote Disclosures | Key Valuation / Accounting Assumptions |
| Long-Term Senior Debt | 5-Year maturity rollout, fair value of fixed-rate debt | Effective interest rate, credit risk adjustments |
| Operating & Finance Leases | Undiscounted cash flow schedule, weighted-average term | Incremental borrowing rates, renewal options |
| Defined Benefit Pension | PBO breakdown, plan asset allocation, benefit payments | Discount rate, long-term return rate, salary growth |
| Share-Based Compensation | Activity tables, unrecognized expense, vesting timelines | Volatility, dividend yield, risk-free rate, expected life |
Strategic Managerial Implications and Investor Considerations
Understanding the Financial Reporting of Long-Term Liabilities and Equity is vital for corporate management, executive boards, and institutional investors evaluating balance sheet strength, earnings quality, and corporate governance.
Financial Ratio and Covenant Impact
Capitalizing operating leases under IFRS 16 and ASC 842 alters key balance sheet leverage and operational efficiency metrics:
- Debt-to-Equity & Gross Leverage: Capitalized lease liabilities increase total reported liabilities, elevating leverage ratios (e.g., Net Debt / EBITDA).
- EBITDA Adjustments: Under IFRS 16, replacing rental expense with ROU depreciation and interest expense increases reported EBITDA, requiring credit analysts to adjust historic leverage metrics.
- Interest Coverage Ratios: Incorporating lease interest and pension interest costs into interest expense metrics lowers EBIT-to-Interest coverage ratios, requiring careful navigation of credit facility debt covenants.
Earnings Quality and Dilution Management
Executive teams must manage the non-cash earnings drag imposed by equity compensation programs. While share-based awards preserve immediate cash reserves, they cause shareholder dilution. Corporate financial managers frequently deploy share repurchase programs (as executed by Microsoft and Apple) to sterilize equity dilution, using free cash flow to buy back shares issued under RSU grants.
Furthermore, pension accounting choices—such as selecting high discount rates to reduce reported PBO liabilities or aggressive expected return rates on plan assets—can mask structural funding deficits. Investors and corporate advisors scrutinize AOCI balances and footnote disclosures to identify off-balance-sheet pension liabilities and evaluate true earnings quality.
Conclusion
Mastering the Financial Reporting of Long-Term Liabilities and Equity is essential for maintaining corporate transparency, compliance, and capital allocation discipline. Standardized reporting frameworks under IFRS and US GAAP ensure that complex lease obligations, defined benefit pension liabilities, and executive share awards are brought into clear view on corporate financial statements.
Real-world financial practices from global enterprises—including Delta Air Lines’ multi-billion-dollar ROU lease portfolios, Boeing’s extensive pension obligations, and Microsoft’s share-based compensation programs—demonstrate how long-term liabilities and equity structures shape corporate balance sheets.
For corporate executives, financial managers, and institutional investors, a thorough understanding of these financial reporting rules provides the foundation for accurate enterprise valuation, effective capital structure management, and sound strategic decision-making.
