Valuing a derivative using a one-period binomial model provides financial professionals, corporate treasurers, and investors with a foundational mathematical framework to price options and other contingent claims accurately.
In modern corporate finance and risk management, understanding how derivative instruments behave under different market trajectories is essential for hedging exposure, optimizing capital structures, and making informed strategic decisions.
Global financial institutions such as JPMorgan Chase and Goldman Sachs rely heavily on discrete-time valuation models to price complex over-the-counter contracts before scaling them into multi-period frameworks.
This comprehensive guide explores the structural mechanics of the one-period binomial model, details the step-by-step valuation process, explains the pivotal concept of risk neutrality, and examines practical corporate applications.
Understanding the Architecture of the One-Period Binomial Model
The binomial option pricing model operates on the principle that over a single discrete time period, an underlying asset’s price can move to only one of two possible states: an upward state or a downward state. This simplified view strips away the continuous-time complexities found in advanced stochastic calculus, making it an ideal pedagogical and practical tool for understanding derivative pricing.
The Underlying Asset Dynamics
To begin valuing any derivative, analysts must establish the current spot price of the underlying asset, denoted as  . Over a single period of length
 , the asset price is assumed to experience one of two multiplicative movements:
- An upward movement factor, denoted by
 , where
 .
- A downward movement factor, denoted by
 , where
 .
Consequently, at the end of the period, the asset price will reach either the upward price node  or the downward price node
 . For example, if a technology stock currently trades at USD100, and the upward factor is
 while the downward factor is
 , the stock price at the end of the single period will be either USD120 or USD90.
Up and Down Movements
The calibration of parameters and links directly to the volatility of the underlying asset and the length of the time period. In standard financial modeling frameworks, these parameters are often derived from the asset’s annualized volatility and the risk-free rate of return. By ensuring that the binomial tree matches the variance and expected return of the underlying asset, financial engineers ensure that the discrete model approximates continuous-time behavior as the number of time periods increases.
How to Value a Derivative Using a One-Period Binomial Model
Valuing a derivative—such as a European call option or put option—using this framework requires moving backward through the single-period tree. This process, known as backward induction, ensures that the derivative is priced consistently with the principle of no arbitrage.
Mapping Payoffs at Expiration
The first step in the valuation process is to determine the payoff of the derivative at the expiration of the single period under both possible price states. Let  represent the value of the derivative if the underlying asset moves to the upward node , and
 represent the value if the asset moves to the downward node .
For a European call option with a strike price  , the terminal payoffs are calculated as follows:
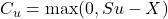
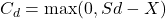
Similarly, for a European put option, the terminal payoffs are:
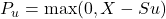
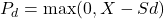
Calculating the Hedge Ratio or Delta
To determine the current value of the derivative,  , analysts construct a risk-free portfolio consisting of a holding in the underlying asset and a short position in the derivative. This is achieved by calculating the hedge ratio, commonly referred to as Delta (
 ):
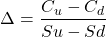
The hedge ratio tells the investor how many units of the underlying asset are required to hedge one unit of the derivative. By combining the underlying asset and the derivative in the exact proportion dictated by Delta, the portfolio’s terminal value becomes completely independent of whether the asset price moves up or down.
Constructing a Risk-Free Portfolio
Because the constructed portfolio is risk-free at the end of the period, its rate of return must equal the risk-free interest rate, denoted as  . By discounting the guaranteed future payoff of the hedged portfolio back to the present value using the risk-free rate, analysts solve directly for the current value of the derivative.
| Model Parameter | Definition / Representation | Economic Significance |
| Spot Price () | Current market price of the underlying asset | Baseline value from which future states originate |
| Up Factor () | Multiplier representing favorable asset movement | Reflects positive market shocks and volatility |
| Down Factor () | Multiplier representing unfavorable asset movement | Reflects negative market shocks and volatility |
| Hedge Ratio () | Ratio of option price change to asset price change | Determines the exact shares needed for risk neutralization |
| Risk-Free Rate () | Continuous or discrete risk-free borrowing/lending rate | Benchmarks the time value of money without credit risk |
The Role of Risk Neutrality in Derivatives Pricing
One of the most profound insights in modern financial economics is that the pricing of derivatives does not depend on the actual, real-world probabilities of upward or downward price movements. Instead, derivatives can be priced under the assumption of risk neutrality.
Risk-Neutral Probabilities Explained
Under a risk-neutral pricing framework, all investors are assumed to be indifferent to risk, meaning that every asset is expected to earn the risk-free rate of return. To implement this, the model calculates risk-neutral probabilities rather than relying on historical or subjective probabilities of asset price changes.
The risk-neutral probability of an upward movement, denoted as  , is formulated as:

(or using discrete compounding,  ).
The risk-neutral probability of a downward movement is simply  .
Why Risk-Neutral Valuation Works
The beauty of risk-neutral valuation lies in its universality and absence of arbitrage. Because derivative prices are determined entirely by the no-arbitrage condition between the underlying asset and the derivative, the risk preferences of market participants cancel out of the pricing equation. Once the risk-neutral probabilities and  are established, the current value of the derivative is simply the expected value of its future payoffs, discounted back to the present at the risk-free rate:
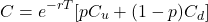
This elegant formula underpins countless financial software systems utilized by global investment banks and corporate finance divisions.
Real-World Implementation by Global Enterprises
While the one-period model is conceptually foundational, its core logic scales directly into multi-period binomial trees used by multinational corporations to manage complex financial risks.
Application at Financial Powerhouses Like JPMorgan Chase
Major financial institutions like JPMorgan Chase employ sophisticated variations of binomial and trinomial pricing models to value exotic options, American-style derivatives, and structured notes. Because American options permit early exercise, standard closed-form formulas like Black-Scholes are insufficient. Binomial trees evaluate the decision to exercise at every node along the path, providing trading desks with accurate pricing boundaries and robust risk-management metrics.
Corporate Hedging at Companies Like Apple and Microsoft
Multinational corporations such as Apple and Microsoft routinely engage in foreign exchange hedging and commodity risk management. When these technology giants issue foreign currency debt or secure raw material supply contracts with embedded options, their treasury departments utilize binomial models to evaluate the fair value of these derivatives. Accurately valuing these instruments prevents overpayment for hedging overlays and ensures strict compliance with financial reporting standards such as hedge accounting rules.
Comparing Binomial Models with Alternative Pricing Frameworks
Financial professionals choose valuation models based on computational efficiency, contract flexibility, and the underlying asset’s behavior.
Binomial Trees Versus the Black-Scholes Model
The Black-Scholes model provides an analytical, closed-form solution for European options under continuous-time assumptions. However, it struggles with path-dependent features or early exercise provisions. The binomial model bridges this gap by breaking time into discrete intervals. As the number of periods in a binomial tree approaches infinity, the binomial price converges to the Black-Scholes price for European options, while retaining the flexibility to handle American-style exercise features effortlessly.
Evaluating Model Limitations and Assumptions
Despite its widespread utility, the one-period binomial model relies on simplifying assumptions. It assumes constant volatility and a constant risk-free rate over the single period—conditions that rarely hold in turbulent modern markets. Furthermore, transaction costs, bid-ask spreads, and market liquidity constraints are initially abstracted away, requiring analysts to apply appropriate adjustments when translating theoretical prices into live market executions.
Conclusion and Strategic Takeaways
Valuing a derivative using a one-period binomial model offers essential clarity into the mechanics of option pricing and risk management. By breaking asset price movements into discrete upward and downward states, analysts can construct risk-free hedged portfolios and leverage risk-neutral probabilities to determine fair value without arbitrating real-world risk preferences. From financial institutions like Goldman Sachs structuring complex derivatives to corporate enterprises managing foreign exchange exposure, mastering the binomial framework remains a vital core competency in professional finance and managerial economics.
