Yield-Based Bond Convexity and Portfolio Properties form the analytical bedrock of modern fixed-income portfolio management, enabling institutional investors, corporate treasurers, and portfolio managers to accurately measure, forecast, and hedge interest rate risk beyond traditional duration metrics.
As global interest rate environments fluctuate, relying solely on Modified Duration exposes fixed-income portfolios to significant pricing errors, particularly during large yield movements.
This comprehensive analysis explores how to calculate and interpret bond convexity, apply the convexity adjustment, compute precise percentage price changes using duration and convexity, aggregate portfolio-level metrics, and navigate the inherent limitations of these risk measures in real-world capital markets.
Understanding Yield-Based Bond Convexity and Its Interpretation
To navigate fixed-income markets effectively, financial analysts must understand why standard duration falls short when managing large interest rate shocks. Modified duration assumes a linear relationship between bond prices and yield changes, creating a straight-line tangent approximation on the curved price-yield relationship curve. However, the true price-yield relationship of a standard, non-optional bond is convex—it slopes downward and bows upward toward the origin. Because of this curvature, duration always underestimates bond prices when yields fall and overestimates them when yields rise.
Convexity is the mathematical measure of this curvature, quantifying the second derivative of the bond price-yield function divided by the bond price. Formally, yield-based convexity ( ) is expressed as:
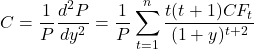
Where  is the clean or full price of the bond,
 represents the cash flow at time
 ,
 is the yield-to-maturity, and
 is the total number of periods.
Interpreting convexity requires recognizing it as a measure of risk mitigation and price volatility enhancement. A higher convexity means the bond’s price is more responsive to favorable yield declines (accelerating price gains) and less sensitive to unfavorable yield increases (dampening price losses). Major global asset management firms, such as BlackRock, actively leverage high-convexity instruments to construct robust portfolios that outperform during volatile interest rate regimes.
The convexity adjustment is the additional percentage price return added to the linear duration-based approximation to account for this curvature. Because the second-order Taylor series expansion includes a positive squared yield change term multiplied by one-half of convexity, the convexity adjustment is always positive for standard fixed-rate bonds. This means that regardless of whether interest rates increase or decrease, the convexity effect always works in favor of the bondholder, mitigating downside price depreciation and amplifying upside price appreciation.
Calculating Percentage Price Change Using Duration and Convexity
When managing fixed-income securities, market participants must project how a bond price will react to specific basis point shifts in the yield curve. Utilizing both modified duration ( ) and convexity (), the estimated percentage price change of a bond (
 ) is calculated using the following second-order Taylor series approximation:
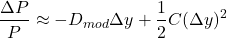
Where  represents the change in yield expressed in decimal format (e.g., a 100 basis point increase is
 ).
Step-by-Step Numerical Example
Consider a corporate bond issued by JPMorgan Chase trading at a full price of USD950.00, with a modified duration of  years and a convexity measure of
 . Assume that macroeconomic indicators prompt the Federal Reserve to adjust monetary policy, resulting in a yield decrease of 150 basis points (
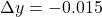 ).
- Calculate the Duration Effect (First-Order Approximation):
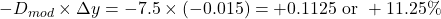
- Calculate the Convexity Effect (Second-Order Approximation):
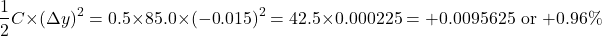
- Combine Effects for Total Estimated Percentage Price Change:
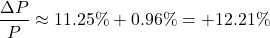
- Calculate the New Estimated Bond Price:
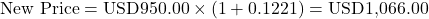
Without the convexity adjustment, the analyst would have estimated a price of USD1,056.25 (an 11.25% gain). The convexity adjustment of USD9.75 accounts for the curvature benefit, providing a significantly more accurate valuation. Similar precision is vital for institutional investors at firms like Vanguard when rebalancing multi-million-dollar fixed-income portfolios.
Calculating Portfolio Duration and Convexity
Institutional fixed-income mandates require portfolio managers to evaluate aggregate risk characteristics rather than analyzing individual bonds in isolation. Portfolio duration and portfolio convexity are calculated as the weighted average of the durations and convexities of the individual securities comprising the portfolio, where the weights are determined by the market value of each holding relative to the total portfolio value.
Let  represent the market value weight of bond
 in the portfolio, such that
 . The formulas are defined as:
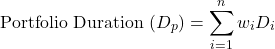
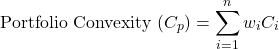
Portfolio Aggregation Analysis
To illustrate this mechanism, examine a simplified multi-asset fixed-income portfolio managed by a corporate treasury team.
| Bond Asset | Market Value (USD) | Portfolio Weight (wi) | Modified Duration (Di) | Convexity (Ci) |
| Asset Alpha | USD3,000,000 | 0.30 | 4.20 | 25.0 |
| Asset Beta | USD5,000,000 | 0.50 | 8.50 | 82.0 |
| Asset Gamma | USD2,000,000 | 0.20 | 12.10 | 185.0 |
| Total / Weighted Sum | USD10,000,000 | 1.00 |  |  |
Using the weighted summation approach:
- Portfolio Duration (
 ):
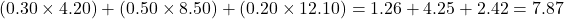 years.
- Portfolio Convexity (
 ):
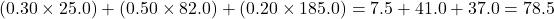 .
This aggregation allows risk managers to model how the entire pool of assets will react to market shocks. If interest rates rise by 100 basis points across the board, the portfolio’s estimated percentage decline can be efficiently computed using the composite metrics.
Limitations of Duration and Convexity Measures
While yield-based duration and convexity provide powerful analytical insights, financial professionals must understand their structural limitations to avoid severe miscalculations during periods of market stress.
Assumption of Parallel Yield Curve Shifts
Standard duration and convexity assume that the entire yield curve shifts in a parallel fashion—meaning short-term, medium-term, and long-term interest rates all move by the exact same number of basis points. In actual market environments, yield curves frequently experience non-parallel shifts, such as steepening, flattening, or butterfly twists. When the term structure twists, a weighted average portfolio duration fails to accurately capture the localized price responses of different maturity sectors.
Presence of Embedded Options
Bonds containing embedded options, such as callable corporate bonds or puttable municipal bonds, exhibit negative or highly unstable convexity profiles. For instance, when interest rates drop significantly, a callable bond approaches its call price, causing its price appreciation to cap out. This phenomenon, known as negative convexity, breaks the standard positive convexity assumption and renders traditional duration and convexity formulas invalid for accurate risk forecasting.
Large Yield Movements and Taylor Series Residuals
The duration-convexity approximation relies on a second-order Taylor series expansion. When yield changes are exceptionally large—such as extreme monetary tightening cycles exceeding 300 basis points—higher-order terms (skewness and kurtosis of price-yield curves) become non-negligible. Relying solely on duration and convexity for massive rate shocks introduces measurable residuals and estimation errors.
Conclusion
Mastering yield-based bond convexity and portfolio properties is essential for effective risk management and strategic fixed-income allocation. By moving beyond linear duration approximations and incorporating convexity adjustments, financial analysts can capture the true curvature of price-yield dynamics. Furthermore, calculating weighted portfolio duration and convexity empowers institutional investors to maintain precise control over portfolio volatility while remaining cognizant of structural limitations such as non-parallel yield curve shifts and embedded options.
