Navigating modern corporate finance requires a rigorous understanding of The Capital Asset Pricing Model, Market Model, and Other Factor-Based Equity Models to accurately estimate a company’s required return on equity and optimize investment portfolios.
This comprehensive guide explores the theoretical underpinnings, practical methodologies, and multi-factor extensions that drive contemporary valuation, capital budgeting, and asset management across global financial markets.
Introduction to Equity Valuation and Required Return
Determining the appropriate cost of capital is one of the most critical responsibilities for financial executives, corporate treasurers, and institutional investors. The required return on equity represents the minimum rate of return that shareholders demand for providing capital to a firm, compensating them for the time value of money and the inherent risk of the investment. Whether a multinational conglomerate like Apple is evaluating a multi-billion-dollar capital expenditure or an institutional asset manager is rebalancing a diversified equity portfolio, accurate return estimation prevents capital misallocation and aligns corporate strategy with shareholder value creation.
Over the decades, financial economics has evolved from simplistic single-factor assessments to sophisticated multi-factor quantitative architectures. Understanding these models allows decision-makers to dissect market anomalies, isolate specific risk premiums, and price corporate securities with greater precision.
The Capital Asset Pricing Model: Mechanics and Application
Foundational Principles of CAPM
Developed by William Sharpe, John Lintner, and Jan Mossin, the Capital Asset Pricing Model (CAPM) remains the cornerstone of modern financial economics. The model posits that the expected return of a security is linearly related to its systematic risk, which is measured by beta ( ). Unsystematic risk—firm-specific uncertainty—is assumed to be fully diversified away in an efficient portfolio, leaving only systemic market risk to be priced by investors.
The standard CAPM equation is expressed as:
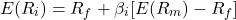
Where:
 is the required return on equity for asset
 .
 is the risk-free rate, typically proxied by government debt yields such as USD-denominated United States Treasury bonds.
 is the measure of the asset’s sensitivity to market movements.
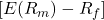 is the equity market risk premium (EMRP), representing the excess return demanded by investors for holding the aggregate market portfolio over the risk-free rate.
Practical Implementation Challenges
While CAPM offers elegant simplicity and intuitive theoretical backing, practitioners encounter several implementation hurdles when applying it in real-world corporate finance:
- Selecting the Risk-Free Rate: Analysts must choose a maturity horizon that matches the company’s investment timeframe, frequently utilizing long-term government bonds to evaluate long-term corporate projects.
- Estimating the Market Risk Premium: Historical averages can distort forward-looking expectations, forcing analysts to adjust EMRP based on macroeconomic cycles, inflation trends, and geopolitical stability.
- Calculating Beta: Beta relies on historical regression analysis of stock returns against a market benchmark (such as the S&P 500). Corporate structural changes, leverage adjustments, and estimation period variations can cause instability in beta coefficients.
The Market Model: Practical Regression and Estimation
Distinguishing CAPM from the Market Model
Although frequently confused with CAPM, the Market Model is an empirical statistical model rather than an equilibrium economic pricing model. While CAPM requires the intercept to equal the risk-free rate and the expected excess return to align strictly with market pricing, the Market Model estimates actual statistical relationships via Ordinary Least Squares (OLS) linear regression.
The Market Model equation is specified as:
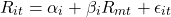
Where:
 is the rate of return on security at time
 .
 is the rate of return on the market index at time .
 is the intercept term (Jensen’s alpha), representing the average return of the security when the market return is zero.
- is the slope coefficient reflecting systematic risk.
 is the zero-mean random error term capturing firm-specific shocks.
Corporate Finance Applications
Financial analysts leverage the Market Model extensively in event studies, performance attribution, and regulatory compliance. For instance, when evaluating how a major acquisition announcement impacts shareholder wealth, analysts examine abnormal returns by subtracting predicted benchmark returns from actual realized returns during the event window. This isolates corporate announcements from broad market movements.
Arbitrage Pricing Theory: Beyond a Single Market Factor
The Multi-Factor Insight of Stephen Ross
Recognizing the restrictive assumptions of CAPM—specifically its reliance on a single market beta—Stephen Ross introduced Arbitrage Pricing Theory (APT) in 1976. APT is rooted in the law of one price, asserting that in competitive markets, two assets with identical risk characteristics must command identical expected returns. If pricing discrepancies arise, arbitrageurs will exploit them until equilibrium is restored.
Unlike CAPM, which restricts systematic risk to market volatility, APT accommodates an arbitrary number of macroeconomic factors that systematically influence asset returns. The general multi-factor APT specification takes the form:
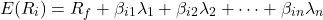
Where  represents the risk premium associated with the
 -th macroeconomic factor, and
 measures the asset’s sensitivity to that specific factor.
Key Macroeconomic Risk Drivers in APT
In practical APT implementations, economists typically isolate major systemic drivers influencing enterprise valuation, including:
- Inflation Rates: Unanticipated changes in inflation erode corporate profit margins and alter consumer purchasing power.
- Industrial Production: Shifts in aggregate output serve as proxies for broader economic growth and business cycle phases.
- Term Structure of Interest Rates: Changes in the yield curve slope affect corporate borrowing costs and capital expenditure financing.
- Credit Spreads: Fluctuations in default risk premiums signal corporate financial health and liquidity availability.
Multi-Factor Models in Modern Equity Investing
Evolution Toward Quantitative Factor Investing
Modern equity management has embraced multi-factor models that merge theoretical factor structures with empirical asset pricing anomalies. Pioneered by Eugene Fama and Kenneth French, multi-factor models expand explanatory power by incorporating firm-specific characteristics that historically predict outperformance.
The Fama-French Three-Factor and Five-Factor Frameworks
The classic Fama-French Three-Factor Model extends CAPM by introducing two size and value dimensions:
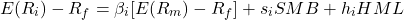
Where:
- SMB (Small Minus Big): Measures the historical excess return of small-cap stocks over large-cap stocks.
- HML (High Minus Low): Measures the excess return of value stocks (high book-to-market ratios) over growth stocks (low book-to-market ratios).
Subsequent empirical research expanded this framework into the Fama-French Five-Factor Model by adding profitability (RMW – Robust Minus Weak) and investment (CMA – Conservative Minus Aggressive) factors. Large multinational enterprises, such as industrial manufacturing giant General Electric, exhibit distinct factor sensitivities across cyclical economic phases, making multi-factor models indispensable for institutional portfolio risk management.
Comparative Analysis of Equity Models
To appreciate how these methodologies differ in scope, complexity, and corporate application, the following comparative framework summarizes their structural attributes:
| Equity Model | Core Theoretical Foundation | Primary Risk Factors | Typical Corporate and Institutional Use Case |
| Capital Asset Pricing Model (CAPM) | Equilibrium market pricing | Single market beta () | Standard corporate cost of equity estimation and capital budgeting. |
| Market Model | Statistical linear regression | Market index returns | Event studies, stock performance benchmarking, and regression analysis. |
| Arbitrage Pricing Theory (APT) | Law of one price / Arbitrage-free equilibrium | Multiple macroeconomic variables | Macro risk hedging and diversified portfolio risk attribution. |
| Fama-French Multi-Factor Models | Empirical asset pricing anomalies | Market, Size, Value, Profitability, Investment | Quantitative equity portfolio management and style-based asset allocation. |
Real-World Corporate Applications and Global Insights
Global corporations and asset managers implement these models daily to navigate complex capital markets. For example, technology giants like Microsoft utilize rigorous cost of equity estimates derived from modified CAPM and multi-factor variants to evaluate venture investments, cloud infrastructure spending, and mergers and acquisitions.
Furthermore, institutional investors managing multi-asset portfolios rely on factor-based equity models to decompose portfolio risk. By identifying whether portfolio returns stem from broad market exposure, value tilts, or profitability characteristics, investment committees can construct resilient portfolios capable of weathering macroeconomic shocks.
Conclusion
Estimating the required return on equity remains a dynamic discipline bridging economic theory and quantitative finance. While the Capital Asset Pricing Model and the Market Model provide intuitive, foundational benchmarks for corporate financial analysis, the complexities of modern markets necessitate multi-factor frameworks like Arbitrage Pricing Theory and the Fama-French models. By understanding the mechanics, strengths, and limitations of each model, financial leaders and investors can make superior capital allocation decisions in an increasingly interconnected global economy.
