Free Cash Flow Valuation provides financial professionals, investors, and corporate strategists with a rigorous analytical framework to determine the intrinsic value of a business by focusing on cash generation rather than accounting earnings.
In modern corporate finance, accounting profit can be distorted by non-cash accruals, revenue recognition policies, and depreciation methods.
Free cash flow models circumvent these distortions by isolating the actual cash generated by operations that is available for distribution to capital providers.
This article explores the mechanics, models, adjustments, and strategic applications of free cash flow valuation for modern enterprises.
Core Concepts: Free Cash Flow to the Firm versus Free Cash Flow to Equity
Understanding the fundamental distinction between Free Cash Flow to the Firm (FCFF) and Free Cash Flow to Equity (FCFE) is essential for executing an accurate valuation. These two metrics represent different cash flow streams available to different capital providers within a corporate structure.
Defining Free Cash Flow to the Firm
Free Cash Flow to the Firm represents the cash flow available to all providers of capital—both debt holders and equity shareholders—after accounting for operating expenses, taxes, and necessary investments in fixed assets and working capital. Because FCFF is available to all capital providers, it is discounted using the Weighted Average Cost of Capital (WACC), which reflects the blended required return of debt and equity investors.
When analyzing global conglomerates like Nestlé, analysts use FCFF to evaluate the overall earning power of core operations regardless of how the firm is financed.
Defining Free Cash Flow to Equity
Free Cash Flow to Equity represents the cash flow remaining after all operating expenses, interest payments, net debt repayments, and investments in working capital and fixed assets have been satisfied. FCFE is the cash flow specifically available to common shareholders. Consequently, FCFE is discounted at the Cost of Equity, which reflects the required rate of return demanded by equity investors for taking on the residual risk of the firm.
Ownership Perspective Implicit in the FCFE Approach
The FCFE approach embodies a direct equity-owner perspective. Under this framework, the analyst evaluates the firm from the viewpoint of a controlling shareholder or a buyer of the entire equity stake. Crucially, FCFE accounts for the company’s financial policy, including debt issuance and retirement. If a company decides to alter its leverage ratio by borrowing additional funds, those debt proceeds increase the cash available to equity holders in the current period, thereby boosting FCFE. Conversely, debt principal repayments reduce FCFE. This perspective recognizes that equity owners bear the ultimate residual risk and enjoy the ultimate residual claim on corporate cash flows.
Reconciling Financial Statements: Adjusting Net Income, EBIT, EBITDA, and CFO
Financial analysts frequently begin valuation modeling with standard accounting figures reported on the income statement or statement of cash flows. To transition from these accounting metrics to true economic cash flows, specific adjustments are required.
Adjustments from Net Income, EBIT, and EBITDA
Net Income is an accounting measure that includes non-cash expenses such as depreciation and amortization, as well as non-operating items. To derive FCFF from EBIT (Earnings Before Interest and Taxes), an analyst must subtract taxes adjusted for interest deductibility, add back non-cash charges like depreciation and amortization, and adjust for changes in working capital and fixed capital investment.
When starting from EBITDA, analysts must adjust for depreciation and amortization, taxes, net working capital investments, and fixed capital expenditures. Because EBITDA excludes depreciation, it ignores the capital expenditures required to maintain existing productive capacity, making direct use of EBITDA as a cash flow proxy problematic without substantial adjustments.
Adjustments from Cash Flow from Operations
Cash Flow from Operations (CFO), reported under US GAAP or IFRS, serves as a common starting point for calculating both FCFF and FCFE. However, CFO requires modification. To derive FCFF from CFO, analysts must add back after-tax interest expense, because interest is treated as an operating outflow under some accounting standards or is paid to debt holders who form part of the total capital provider group.
The table below outlines the conceptual bridges from standard financial metrics to FCFF and FCFE.
| Starting Metric | Bridge to FCFF | Bridge to FCFE |
| Net Income | Add: Net Interest Expense 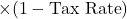 , Add: Non-Cash Charges, Less: Fixed Capital Investment, Less: Working Capital Investment | Add: Non-Cash Charges, Less: Fixed Capital Investment, Less: Working Capital Investment, Plus: Net Borrowing |
| EBIT | Less: Adjusted Taxes, Add: Non-Cash Charges, Less: Fixed Capital Investment, Less: Working Capital Investment | Less: Adjusted Taxes, Add: Non-Cash Charges, Less: Fixed Capital Investment, Less: Working Capital Investment, Less: Interest , Plus: Net Borrowing |
| CFO | Add: Interest Expense , Less: Non-Operating Cash Flows, Less: Non-Sustaining Capital Expenditures | Less: Non-Sustaining Capital Expenditures, Plus: Net Borrowing |
Practical Calculation and Real-World Application
To illustrate the practical computation of FCFF and FCFE, consider a well-established multinational enterprise such as Microsoft. Financial models rely on verified historical financial data to project future cash flows.
Suppose a fictional or simplified reporting period for a major technology firm shows the following figures (all values in USD):
- Net Income: USD72,000 million
- Depreciation and Amortization: USD14,000 million
- Interest Expense: USD2,500 million
- Tax Rate: 21%
- Capital Expenditures (CapEx): USD18,000 million
- Increase in Net Working Capital: USD3,000 million
- New Debt Issued: USD5,000 million
- Debt Repaid: USD2,000 million
Calculating FCFF
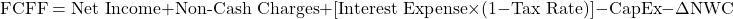
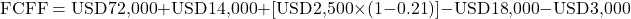
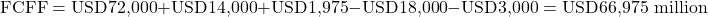
Calculating FCFE
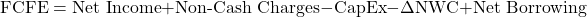
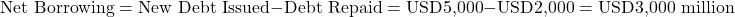
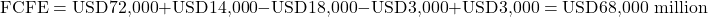
These calculated figures represent the precise cash available to all capital providers and equity holders, respectively, serving as the primary inputs for multi-stage valuation models.
Approaches for Forecasting Free Cash Flow and Capital Structure Dynamics
Forecasting free cash flow requires a granular understanding of a company’s business drivers, competitive environment, and macroeconomic backdrop. Analysts typically project revenue growth, operating profit margins, working capital requirements as a percentage of revenue, and capital expenditures relative to depreciation.
Forecasting Methodologies
- Percentage of Sales Method: Projects income statement items and working capital accounts as historical percentages of forecasted revenues.
- Driver-Based Forecasting: Connects operational metrics (such as unit sales volume, average selling prices, and store openings) directly to financial statement line items.
- Capital Intensity Modeling: Projects fixed capital investments based on strategic corporate plans, plant expansions, and technological upgrade cycles.
Impact of Corporate Actions on Future Cash Flows
Corporate financial decisions directly alter future cash flow streams:
- Dividends: While dividend payments represent a cash outflow for the firm, they do not directly alter FCFF or FCFE because FCFE measures cash generated available for distribution, regardless of whether it is paid out or retained. However, high dividend payouts reduce cash reserves and may necessitate external financing if investment opportunities exceed internal cash generation.
- Share Repurchases: Share buybacks utilize accumulated cash or newly issued debt to retire equity. This reduces cash balances (lowering future interest income) and reduces share count, impacting per-share metrics.
- Share Issues: Issuing new equity infuses cash into the business, increasing cash balances and altering the capital structure, which lowers leverage and affects the weighted average cost of capital.
- Changes in Leverage: Altering the debt-to-equity mix impacts interest expense tax shields and financial risk. Increasing leverage boosts FCFE in the short term through debt proceeds, but increases fixed interest burdens, potentially increasing volatility in future FCFE.
Comparative Analysis: FCFE Models versus Dividend Discount Models and Proxy Evaluations
Valuation theory offers multiple paths to equity valuation, each with distinct advantages and limitations.
Comparing FCFE Models and Dividend Discount Models
The Dividend Discount Model (DDM) values a stock by discounting future dividends back to present value. While DDM is conceptually straightforward, many sound, growing corporations—such as Alphabet—pay little or no dividends, hoarding cash for internal expansion or executing share repurchases instead.
In contrast, the FCFE model measures cash flow potential rather than actual cash distributions. Even if a company chooses not to pay dividends, FCFE captures what could be distributed to shareholders without impairing operations. Consequently, FCFE models are applicable to a broader range of companies than traditional DDM frameworks.
Evaluating Net Income and EBITDA as Proxies for Cash Flow
Relying solely on Net Income or EBITDA as direct proxies for free cash flow introduces significant valuation errors:
- Net Income Limitations: Net income includes non-cash depreciation, amortization, and arbitrary accounting accruals while ignoring mandatory capital expenditures required to maintain business operations.
- EBITDA Limitations: EBITDA ignores capital expenditures, changes in net working capital, and tax obligations. Treating EBITDA as free cash flow assumes that replacement capital expenditures are zero and that working capital financing requires no cash, which is rarely true in competitive industries.
Valuation Models: Single-Stage, Two-Stage, and Three-Stage Frameworks
Selecting the appropriate valuation model depends on the stability of the company’s growth profile.
Single-Stage (Stable-Growth) Model
The single-stage model assumes that FCFF or FCFE grows at a constant, sustainable rate indefinitely. This model is best suited for mature, stable companies operating in mature industries with growth rates roughly equal to long-term nominal GDP growth.
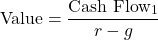
where  is the required rate of return and
 is the constant growth rate.
Two-Stage and Three-Stage Models
For firms experiencing high initial growth that eventually decelerates to a stable rate, multi-stage models are required:
- Two-Stage Model: Assumes an initial period of high growth followed by a sudden drop to a permanent stable growth rate.
- Three-Stage Model: Incorporates an initial high-growth phase, a transitional middle phase where growth declines linearly, and a final mature stable-growth phase. This model is ideal for growth-oriented technology firms or emerging market enterprises.
Terminal Value Estimation Approaches in Multistage Models
In multi-stage valuation, a substantial portion of a company’s total value is derived from the terminal value (TV), representing the value of cash flows beyond the explicit forecast horizon. Two primary approaches are used to estimate terminal value:
Gordon Growth Model Approach
This method assumes that cash flows grow at a constant rate forever beyond the forecast horizon:
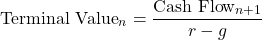
While mathematically rigorous, this approach is highly sensitive to small changes in the terminal growth rate and the discount rate .
Exit Price Multiple Approach
This method estimates terminal value by applying an industry-standard valuation multiple—such as Enterprise Value to EBITDA or Price-to-Earnings—to the company’s final forecast year metric. While intuitive and closely aligned with market sentiment, this approach relies on relative valuation and can introduce market mispricing errors if sector multiples are temporarily inflated or depressed.
Valuation Diagnostics: Sensitivity Analysis and Investment Decision-Making
Valuation models are built upon numerous forward-looking assumptions, making sensitivity analysis an indispensable tool for financial analysts.
Explaining Sensitivity Analysis in Valuations
Sensitivity analysis involves flexing key model inputs—such as the revenue growth rate, operating margins, capital expenditure intensity, weighted average cost of capital, and terminal growth rate—to observe their impact on estimated intrinsic value. By constructing valuation matrices, analysts can determine whether an investment thesis is robust across various economic scenarios or overly dependent on overly optimistic growth assumptions.
Evaluating Overvaluation, Fair Valuation, and Undervaluation
Once the intrinsic value per share is calculated using FCFF or FCFE models, it is compared directly against the current market price of the stock:
- Undervalued: If the estimated intrinsic value exceeds the current market price, the stock is undervalued, suggesting a potential buying opportunity.
- Fairly Valued: If intrinsic value aligns closely with the market price, the stock is fairly valued, reflecting efficient pricing by the market.
- Overvalued: If intrinsic value falls below the current market price, the stock is overvalued, indicating a potential sell or avoid recommendation.
Conclusion
Free cash flow valuation remains the gold standard for institutional investors, corporate executives, and financial analysts seeking to uncover the true economic worth of a business.
By moving beyond accounting earnings, correctly adjusting financial statements, applying appropriate multi-stage growth frameworks, and conducting rigorous sensitivity testing, analysts can make informed, data-driven investment decisions in complex global markets.
