An arbitrage-free valuation of a fixed-income instrument is a pricing methodology that yields a theoretical fair value equal to the sum of the present values of its expected future cash flows, discounted using a series of spot rates or forward rates that reflect market conditions.
This framework ensures that the calculated price prevents market participants from earning a riskless profit without capital investment (arbitrage).
In efficient financial markets, securities with identical future cash flow risk profiles must trade at identical prices (the Law of One Price). Under the arbitrage-free framework:
- The model reproduces the market prices of benchmark risk-free securities, such as Treasury bonds or zero-coupon spot yield curves.
- Every cash flow occurring at a specific future date
 is discounted using the specific discount factor derived from the spot rate
 corresponding to that exact time horizon.
- Cash flows are treated as a package of individual zero-coupon bonds (strips).
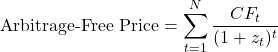
Where  represents the cash flow at period , and
 represents the zero-coupon spot rate for period .
If a security’s market price deviates from its calculated arbitrage-free value, trading desks can construct an arbitrage portfolio:
- If the security is overpriced: Sell (short) the overpriced instrument and purchase a replicating portfolio of zero-coupon Treasury bonds that replicates the cash flow sequence.
- If the security is underpriced: Buy the underpriced instrument and short-sell the replicating portfolio of zero-coupon Treasury bonds.
By locking in offsetting cash flows, the investor realizes a riskless cash inflow today. Market forces swiftly eliminate these pricing discrepancies through buying and selling pressures, driving market prices back to arbitrage-free equilibrium.
Calculating the Arbitrage-Free Value of an Option-Free, Fixed-Rate Coupon Bond
To compute the arbitrage-free value of a standard option-free, fixed-rate coupon bond, each future coupon payment and the principal repayment must be discounted at the spot rate corresponding to its exact payment maturity date, rather than using a single uniform yield-to-maturity (YTM).
Valuation Formula
For a bond with maturity  , annual coupon payment
 , face value
 , and zero-coupon spot rate curve
 :
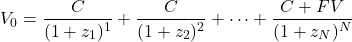
Practical Valuation Example
Consider a 3-year option-free bond with a face value of USD1,000 paying an annual coupon rate of 5.00% (USD50 annual coupon). The prevailing benchmark spot rate curve is as follows:
- Year 1 Spot Rate (
 ): 3.50%
- Year 2 Spot Rate (
 ): 4.20%
- Year 3 Spot Rate (
 ): 4.80%
Step-by-Step Discounting Calculation
- Year 1 Cash Flow (
 ): USD50.00
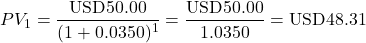
- Year 2 Cash Flow (
 ): USD50.00
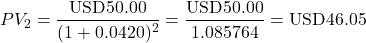
- Year 3 Cash Flow (
 ): USD1,050.00 (Coupon + Principal)
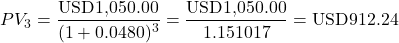
Summation of Discounted Cash Flows
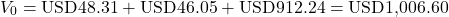
The arbitrage-free value of the bond is USD1,006.60. If the bond trades in the open market at USD1,012.00, it is overvalued relative to the spot curve, presenting a short-sale opportunity via stripping.
The Binomial Interest Rate Tree Framework
A binomial interest rate tree is a discrete-time, lognormal model representing possible future paths that short-term interest rates (one-period forward rates) can follow over time. It serves as a core engine for pricing fixed-income instruments, particularly those containing embedded options (such as callable or putable corporate bonds).
Structural Properties of a Binomial Interest Rate Tree
- Nodes and Periods: The tree consists of discrete periods
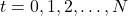 . At each node, a short-term rate applies for that specific period.
- Branching Mechanics: From any given node at time , interest rates can move to two possible states at time
 :
- An up-state (higher short-term rate,
 )
- A down-state (lower short-term rate,
 )
- An up-state (higher short-term rate,
- Lognormal Rate Distribution: Interest rates are assumed to follow a lognormal process, ensuring two structural benefits:
- Rates cannot drop below zero (non-negativity constraint).
- Volatility is proportional to the level of interest rates (higher rates exhibit higher absolute volatility).
                      /--- Node 2,uu (r_2,uu)
        /--- Node 1,u
       /              \--- Node 2,ud (r_2,ud)
Node 0
(r_0)  \              /--- Node 2,ud (r_2,ud) [Recombining]
        \--- Node 1,d
                      \--- Node 2,dd (r_2,dd)
Mathematical Relationship Between Nodes
The relationship between short rates at a given time step is governed by the underlying interest rate volatility parameter  :
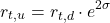
Because the tree recombines (meaning an up-then-down movement yields the same interest rate as a down-then-up movement), a tree with  time steps contains
 nodes at the final step, keeping computational overhead manageable.
Calibrating a Binomial Interest Rate Tree
A binomial interest rate tree must be calibrated so that it accurately reproduces the observed market term structure of spot rates. If an uncalibrated tree is used, the model will misprice plain-vanilla risk-free bonds, rendering option valuations invalid.
The Calibration Process Step-by-Step
Calibration involves an iterative process using real-world market benchmarks (such as Treasury zero-coupon yield curves or par yields):
+-----------------------------------------------------------------------+
| Step 1: Input Observed Spot Rate Curve & Volatility Assumption (σ)    |
+-----------------------------------------------------------------------+
                                   |
                                   v
+-----------------------------------------------------------------------+
| Step 2: Set Root Node Interest Rate (r_0) Equal to 1-Period Spot Rate  |
+-----------------------------------------------------------------------+
                                   |
                                   v
+-----------------------------------------------------------------------+
| Step 3: Establish Spatial Node Relationship (r_t,u = r_t,d * e^(2σ))  |
+-----------------------------------------------------------------------+
                                   |
                                   v
+-----------------------------------------------------------------------+
| Step 4: Iteratively Solve for Fundamental Down-Rate (r_t,d) via Solver|
|         (Match Benchmark Par Bond / Zero-Coupon Bond Market Price)    |
+-----------------------------------------------------------------------+
                                   |
                                   v
+-----------------------------------------------------------------------+
| Step 5: Verify Tree Pricing Against Benchmark Treasury Securities     |
+-----------------------------------------------------------------------+
- Select Benchmark Instruments: Identify current market prices for zero-coupon bonds or par coupon bonds for maturities corresponding to the tree’s time steps.
- Set Root Rate (
 ): Set the initial node rate equal to the current observed 1-period spot rate ().
- Determine Volatility (): Input an assumed benchmark interest rate volatility , derived from historical data or implied from swaptions / interest rate cap markets.
- Iterative Root-Finding for Subsequent Nodes:
- At period
 , express the up-rate
 as
 .
- Price a 2-period benchmark bond using backward induction through nodes
 and
 .
- Adjust
 until the calculated tree value matches the market price of the 2-period benchmark bond.
- At period
- Forward Progression: Repeat this numerical search for periods
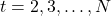 .
Once calibrated, discounting any benchmark zero-coupon bond through the interest rate tree will produce a value matching its spot-curve valuation.
Backward Induction Valuation Methodology
Backward induction is the mathematical process used to value securities on a lattice or tree structure by working backward from the final maturity date to the valuation date (Time 0).
Core Rule of Backward Induction
The value of a fixed-income instrument at any interior node  at time is calculated as the expected future value at time , discounted back to time using the node’s short rate
 :
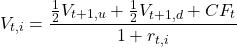
Where:
 is the bond value at the upper adjacent node at time .
 is the bond value at the lower adjacent node at time .
- is any coupon cash flow received at time .
 represents the equal risk-neutral probability assigned to up and down movements in a calibrated tree.
Numerical Example: Backward Induction Calculation
Consider a 2-year option-free bond with a 6.00% annual coupon (USD60) and face value of USD1,000.
Calibrated Interest Rate Tree
- Time 0 (): 4.00%
- Time 1 Up-rate (): 6.50%
- Time 1 Down-rate (): 4.80%
               Time 1           Time 2 (Maturity)
                             /--- Node (2,uu): Cash Flow = 1,060
               r_1,u = 6.50%
             /               \--- Node (2,ud): Cash Flow = 1,060
r_0 = 4.00%
             \               /--- Node (2,ud): Cash Flow = 1,060
               r_1,d = 4.80%
                             \--- Node (2,dd): Cash Flow = 1,060
Backward Induction Steps
Step 1: Maturity Values (Time 2)
At maturity ( ), the bond pays the face value plus final coupon:
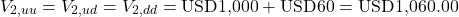
Step 2: Valuation at Time 1
Calculate values at nodes and by discounting Time 2 payoffs at Time 1 rates, then adding the Time 1 coupon (USD60):
- Node Value (
 ):
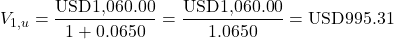
- Node Value (
 ):
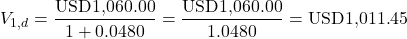
Step 3: Valuation at Time 0 ( )
Discount the expected value from Time 1 back to Time 0 using short rate  :
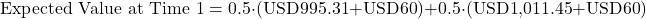
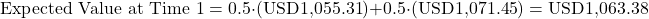
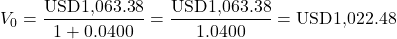
The arbitrage-free value derived via backward induction is USD1,022.48.
Comparing Pricing: Spot Yield Curve vs. Arbitrage-Free Binomial Lattice
Two primary frameworks exist for valuing fixed-income securities: static spot curve discounting and dynamic binomial lattice discounting.
Methodological Comparison
| Structural Feature | Zero-Coupon Spot Yield Curve | Arbitrage-Free Binomial Lattice |
| Handling of Volatility | Static (Assumes zero interest rate volatility) | Dynamic (Explicitly incorporates interest rate volatility ) |
| Suitable Securities | Option-free fixed income | Instruments with embedded options (Callable, Putable, Ratchet) |
| Discounting Mechanism | Single spot rate applied to each discrete payment date | Branching paths of short-term interest rates |
| Path Dependency | Cannot evaluate state-contingent decisions | Evaluates exercise decisions dynamically at each node |
| Pricing Output (Option-Free) | Identical to Binomial Tree | Identical to Spot Curve |
Strategic Applications
- Option-Free Bonds: Pricing an option-free bond on a calibrated binomial interest rate tree yields the exact same price as discounting cash flows using the spot curve. This occurs because the calibration process aligns tree expectation pathways with the spot curve.
- Bonds with Embedded Options: The spot yield curve fails when bonds contain embedded options. For example, a issuer’s decision to call a bond depends on whether prevailing short rates drop below the coupon rate at future dates. The binomial lattice models these state-contingent decisions at each node by comparing the option-free node value with the execution strike price.
Pathwise Valuation in a Binomial Framework
Pathwise valuation is an alternative, mathematically equivalent approach to backward induction for pricing fixed-income instruments within a binomial interest rate tree. Instead of rolling backwards node-by-node, pathwise valuation explicitly maps out every unique path an interest rate sequence can follow from Time 0 to maturity.
Key Principles of Pathwise Valuation
- Path Enumeration: For an -period tree, there are
 unique interest rate paths.
- Path Discount Factor: A path-specific discount factor is calculated by multiplying the single-period discount factors along that exact path.
- Path Present Value: Cash flows along a path are discounted using that path’s specific discount factor sequence.
- Overall Security Value: The security’s value equals the simple arithmetic average of the present values across all paths (since each path carries an equal probability of
 in a standard risk-neutral tree).
Pathwise Valuation Formula
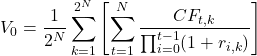
Numerical Example: Pathwise Pricing
Using a 2-period framework ( paths) for a 2-year bond paying a USD60 annual coupon and USD1,000 principal at maturity:
- Period 1 rates:
 ,

Path 1 (Upper-Upper): r_0 (4.00%) -> r_1,u (6.50%)
Path 2 (Upper-Lower): r_0 (4.00%) -> r_1,u (6.50%)
Path 3 (Lower-Upper): r_0 (4.00%) -> r_1,d (4.80%)
Path 4 (Lower-Lower): r_0 (4.00%) -> r_1,d (4.80%)
Path Discount Calculation
- Path 1 (
 ):
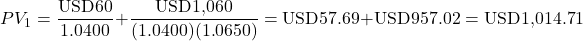
- Path 2 ():(Identical single-period discount rates as Path 1 for a 2-period option-free bond)
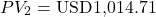
- Path 3 (
 ):
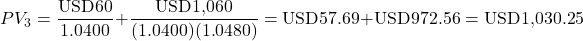
- Path 4 ():
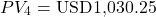
Averaging Across All Paths
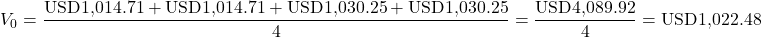
This result matches the backward induction outcome (USD1,022.48).
Monte Carlo Forward-Rate Simulation and Its Applications
While binomial trees work well for standard instruments, they face structural limitations when valuing complex, path-dependent fixed-income securities. In these cases, financial institutions rely on Monte Carlo simulation.
Mechanics of Monte Carlo Simulation
A Monte Carlo forward-rate simulation generates thousands of randomly selected forward-rate paths based on specified interest rate volatility and drift assumptions:
- Path Generation: Stochastic differential equations generate
 interest rate paths (e.g.,
 to
 simulations).
- Calibration via Drift Adjustment: Raw simulated paths are adjusted by adding a constant drift term
 to every path. This step ensures that discounting risk-free benchmark cash flows across all paths matches their current market spot prices.
- Cash Flow Evaluation: Security cash flows are evaluated along each individual path.
- Discounting & Present Value: Cash flows along each path are discounted using that path’s specific interest rate sequence.
- Averaging: The arbitrage-free value equals the arithmetic mean of present values across all simulated paths.
       /======================= Simulated Path 1 ========================>
      /------------------------ Simulated Path 2 ------------------------>
Root /------------------------- Simulated Path 3 ------------------------>
Node \------------------------- Simulated Path ... ---------------------->
      \------------------------ Simulated Path M-1 ---------------------->
       \======================= Simulated Path M ------------------------>
Applications: Valuing Mortgage-Backed Securities (MBS)
The primary application of Monte Carlo simulations in fixed income is pricing Mortgage-Backed Securities (MBS) and complex collateralized debt obligations.
Why Binomial Trees Fail for MBS (Path Dependency)
MBS cash flows depend heavily on homeowner prepayment behavior, which is fundamentally path-dependent:
- If interest rates drop significantly, homeowners refinance, triggering high prepayments.
- If interest rates later rise back to initial levels, prepayment rates do not simply return to normal. Homeowners who already refinanced no longer have an incentive to refinance again (the refinancing burnout effect).
- Because cash flows at a node depend on the historical sequence of rates rather than just the current node rate, a recombining binomial tree cannot capture this behavior. Monte Carlo simulations track historical rate paths directly, accommodating path dependency.
Term Structure Models and Their Financial Applications
Term structure models are mathematical frameworks that describe the time evolution of interest rates across maturities. Portfolio managers, risk managers, and quantitative traders use these models to price exotic derivatives, measure portfolio risk metrics (such as Option-Adjusted Spread and Effective Duration), and conduct stress tests.
Term structure models are broadly categorized into Equilibrium Models and Arbitrage-Free Models.
Categorization Matrix of Term Structure Models
| Category | Model Name | Primary Mathematical Equation | Primary Characteristic / Application |
| Equilibrium | Vasicek Model | 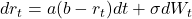 | Incorporates mean reversion; allows rates to become negative. |
| Equilibrium | Cox-Ingersoll-Ross (CIR) | 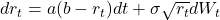 | Incorporates mean reversion; prevents negative rates via  . |
| Arbitrage-Free | Ho-Lee Model | 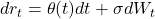 | First arbitrage-free model; calibrates to current yield curve using time-dependent drift  . |
| Arbitrage-Free | Black-Derman-Toy (BDT) | 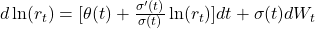 | Lognormal yield model; prevents negative rates; widely used for corporate callable bonds. |
| Arbitrage-Free | Hull-White Model | 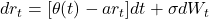 | Extended Vasicek model; incorporates both mean reversion and exact term structure fitting. |
1. Equilibrium Term Structure Models
Equilibrium models start with fundamental economic assumptions regarding macro variables, risk aversion, and capital supply/demand. They derive the yield curve endogenously.
- Vasicek Model: Assumes short-term interest rates exhibit mean-reverting behavior toward a long-term mean level
 at a speed
 . Its primary limitation is that short rates can theoretically turn negative due to constant volatility .
- Cox-Ingersoll-Ross (CIR) Model: Resolves the negative rate issue of the Vasicek model by scaling volatility with the square root of the current short rate (
 ). As rates approach zero, volatility vanishes, keeping rates positive.
Key Drawback of Equilibrium Models: They generally do not fit the current market yield curve exactly. As a result, they can misprice benchmark instruments, making them less suitable for derivative pricing where arbitrage-free alignment is required.
2. Arbitrage-Free Term Structure Models
Arbitrage-free models take the observed market yield curve as a given input and calibrate parameters so the model reproduces market prices.
- Ho-Lee Model: Uses a time-dependent drift function to fit the initial term structure exactly. However, it assumes constant volatility and permits negative interest rates.
- Black-Derman-Toy (BDT) Model: A lognormal model where short rates are lognormally distributed, preventing negative rates. It allows interest rate volatility to vary over time, making it a standard choice for pricing embedded options in fixed-income markets.
- Hull-White Model: Enhances the Vasicek model by making drift time-dependent (). This enables the model to fit the current yield curve while maintaining mean-reverting interest rate dynamics.
Corporate Applications in Financial Markets
Major financial institutions, investment funds, and corporate treasuries rely on term structure models for key operations:
- Valuation of Embedded Options: Investment banks use calibrated models (like BDT or Hull-White) to price callable, putable, and convertible bonds issued by corporations like Apple Inc. and Microsoft Corp.
- Option-Adjusted Spread (OAS) Calculation: By separating credit and liquidity spreads from embedded option risk, risk managers can determine whether a structured bond offers sufficient yield compensation.
- Dynamic Hedging: Financial institutions use term structure models to derive key sensitivity metrics (such as Effective Duration and Effective Convexity) to hedge interest rate risk across complex fixed-income portfolios.
