Equity analyst research reports serve as fundamental analytical blueprints within modern capital markets, enabling institutional and retail investors to evaluate company performance, industry dynamics, and equity valuations.
An in-depth understanding of equity analyst research reports is vital for business executives, financial managers, and investment professionals who rely on these documents to assess corporate strategy, gauge market sentiment, and make capital allocation decisions.
This comprehensive article examines the essential elements required in a thorough company research report, provides a comparative analysis of sell-side and buy-side research methodologies and conclusions, and explores why identical quantitative valuation frameworks yield disparate intrinsic value estimates based on varying analyst assumptions regarding revenue growth, profitability margins, reinvestment rates, and capital structure financing.
Essential Elements of a Detailed Company Research Report
A rigorous, institutional-grade equity research report must synthesize vast amounts of quantitative financial data and qualitative strategic intelligence into a structured, highly actionable document. Professional financial analysts follow structured frameworks to ensure that every critical driver of corporate value is evaluated systematically. The core sections detailed below constitute the foundational framework of exhaustive company research reports.
Investment Summary, Rating, and Target Price
The opening section of equity analyst research reports serves as an executive brief designed for rapid decision-making. It contains the primary investment thesis, the stock rating (such as Buy, Hold, or Sell), the target price over a 12-to-18-month horizon, and the current market price. The thesis highlights the key catalysts expected to unlock shareholder value, such as product launches, margin expansion, market share gains, or regulatory approvals. A concise summary of risk-reward asymmetry is included alongside key financial metrics, including market capitalization, enterprise value, price-to-earnings (P/E) multiples, and dividend yield.
Business Description, Industry Dynamics, and Competitive Moat
To evaluate future growth, analysts must dissect the firm’s business model, revenue streams, geographic footprint, and customer concentration. This section evaluates macro-environmental trends and industry structural forces using frameworks such as Porter’s Five Forces and Total Addressable Market (TAM) mapping. A critical component is the identification of the company’s competitive moat—whether derived from network effects, cost leadership, switching costs, intellectual property, or brand equity. For example, when evaluating tech leaders like Apple, analysts closely examine hardware ecosystem lock-in and services recurring revenues, whereas reports on automotive giants such as Toyota Global focus on manufacturing efficiency, supply chain scale, and global dealership distribution networks.
Historical Financial Performance and Financial Statement Modeling
An exhaustive report provides a granular examination of historical financial statements across a minimum of three to five years, followed by detailed multi-year forward projections. Analysts build integrated three-statement financial models—linking the income statement, balance sheet, and cash flow statement—to forecast future operational trends. Key financial ratios are thoroughly analyzed across four dimensions:
- Profitability: Gross margin, operating margin, net profit margin, Return on Equity (ROE), and Return on Invested Capital (ROIC).
- Liquidity and Solvency: Current ratio, quick ratio, net debt-to-EBITDA, and interest coverage ratios.
- Operational Efficiency: Asset turnover, inventory turnover, and cash conversion cycle days.
- Cash Flow Generation: Free cash flow to equity (FCFE), free cash flow to firm (FCFF), and cash conversion rates relative to net income.
Valuation Frameworks and Quantitative Methodologies
The valuation section represents the core quantitative engine of equity analyst research reports. To determine intrinsic value, analysts deploy both absolute and relative valuation methodologies:
- Discounted Cash Flow (DCF) Analysis: Multi-stage DCF models project explicit free cash flows over a 5-to-10-year horizon before applying a terminal value calculated via the Gordon Growth Method or Exit Multiple approach, discounted at the Weighted Average Cost of Capital (WACC).
- Relative Valuation / Trading Comps: Multiples such as EV/EBITDA, P/E, Price-to-Sales (P/S), and Price-to-Book (P/B) are benchmarked against peer group medians and historical averages.
- Precedent Transactions: Historical acquisition multiples within the sector are examined to establish private market transaction benchmarks.
- Dividend Discount Models (DDM): Applied primarily to mature, capital-intensive, or financial institutions like global banks.
Risk Analysis, Scenario Modeling, and ESG Considerations
Institutional investors require clear visibility into potential downside exposure. A thorough research report details operational, financial, regulatory, geopolitical, and macroeconomic risk factors. Analysts conduct sensitivity analyses and scenario modeling (Bull Case, Base Case, and Bear Case) to illustrate how target prices shift under varying operational conditions. Furthermore, Environmental, Social, and Governance (ESG) evaluations have become mandatory, assessing carbon transition risks, labor practices, board independence, and executive compensation alignment. Enterprise software providers like Microsoft are frequently evaluated on cloud cybersecurity resilience and data privacy governance structures alongside financial metrics.
| Report Section | Key Analytical Focus | Primary Output / Deliverable |
| Investment Summary | Thesis, catalysts, risk/reward balance | Target Price, Rating (Buy/Hold/Sell), Expected Return % |
| Business & Industry Analysis | Moat analysis, TAM expansion, competitive forces | Qualitative competitive advantage assessment |
| Financial Analysis & Modeling | Three-statement historical & 5-year projections | Forecasted EPS, Free Cash Flow, Margins, ROIC |
| Valuation Methodology | DCF, Trading Comps, Precedent Transactions | Implied Intrinsic Value & Multiple Comparison Matrix |
| Risk & Sensitivity Analysis | Operational, regulatory, macro risks, ESG | Bull/Base/Bear scenario price targets & sensitivity tables |
Comparing Sell-Side and Buy-Side Equity Analyst Reports and Their Conclusions
Although sell-side and buy-side analysts utilize similar analytical techniques, their research reports serve fundamentally distinct institutional mandates, audiences, and commercial objectives. Understanding the operational divide between sell-side research published by investment banks and buy-side research produced within asset management firms is essential for interpreting their final conclusions.
Institutional Objectives, Audience, and Distribution Channels
Sell-side equity analysts work for brokerage firms, investment banks, and independent research providers such as Goldman Sachs, Morgan Stanley, and UBS. Their primary objective is to market research broadly to institutional clients, retail traders, and internal sales desks. Sell-side equity analyst research reports are published externally to stimulate equity trading volume (generating brokerage commissions) and demonstrate sector expertise that supports investment banking underwriting, corporate advisory, and equity capital market transactions.
Conversely, buy-side analysts work for institutional asset owners, mutual funds, hedge funds, pension funds, and private wealth managers such as BlackRock and Fidelity Investments. Their research reports are highly confidential, proprietary internal memos prepared exclusively for portfolio managers and investment committees. The primary goal of buy-side research is alpha generation—outperforming market benchmarks by deploying capital into mispriced securities while managing portfolio risk.
Incentive Structures, Conflict Management, and Objectivity
The structural differences between sell-side and buy-side organizations create distinct operational incentives and potential conflicts of interest:
- Sell-Side Dynamics: Historically, sell-side research faced scrutiny regarding investment banking conflicts of interest, where optimistic reports were published to secure lucrative deal mandates. While regulatory firewall mandates (such as Global Research Settlements and MiFID II) strictly separate research from corporate finance, sell-side analysts maintain incentives to preserve executive access. Consequently, sell-side reports often display a structural “optimism bias,” with a disproportionate distribution of “Buy” ratings relative to “Sell” ratings.
- Buy-Side Dynamics: Buy-side analysts are compensated based on the measurable investment performance of their recommendations within fund portfolios. If a buy-side analyst recommends purchasing a stock that underperforms, the fund incurs real capital losses, impacting team compensation and institutional assets under management (AUM). Therefore, buy-side reports exhibit rigorous objectivity, skepticism, and a strong emphasis on risk management.
Depth of Research, Reporting Timelines, and Format
Sell-side equity analyst research reports are designed for external readability and standardized client distribution. They range from concise 2-to-5-page earnings flash notes to comprehensive 50-to-100-page thematic or initiation reports. They follow consistent formatting conventions, including standardized financial model outputs, public disclosures, and mandatory compliance disclaimers.
Buy-side research reports vary widely in format depending on the fund’s investment horizon. A hedge fund analyzing event-driven arbitrage might utilize a concise, bulleted memo emphasizing immediate catalysts, liquidity constraints, and downside protection. A long-only value fund may construct exhaustive internal investment memos dissecting accounting quality, management integrity, supply chain channel checks, and historical capital allocation efficiency. Buy-side reports skip marketing boilerplate and focus directly on conviction levels, trade structuring, and portfolio risk interactions.
Divergence in Research Conclusions and Actionable Recommendations
The final conclusions rendered in sell-side versus buy-side research reflect their differing operating environments:
- Sell-Side Conclusions: Conclude with standardized rating nomenclature (e.g., Outperform, Neutral, Underperform), a explicit 12-month target price (e.g., target price of USD180 against a current price of USD150), and standardized earnings-per-share (EPS) estimates.
- Buy-Side Conclusions: Conclude with direct portfolio allocation instructions. Rather than providing a single point-estimate target price, buy-side conclusions recommend specific trade parameters: position sizing percentage (e.g., “Allocate 2.5% of fund AUM”), execution entry bands (e.g., “Accumulate stock between USD135 and USD145”), options hedging strategies, exit stop-loss limits, and portfolio correlation risk factors.
| Dimension | Sell-Side Research Reports | Buy-Side Research Reports |
| Primary Audience | External institutional/retail clients & sales desks | Internal portfolio managers & investment committees |
| Primary Goal | Generate trading volume & institutional prestige | Maximize fund return (alpha) & preserve capital |
| Publication Status | Publicly distributed to clients and media | Strictly proprietary & confidential internal memos |
| Rating Bias | Structurally optimistic (high % of Buy ratings) | Highly critical, skeptical, and objective |
| Compensation Driver | Client vote, brokerage volume, deal support | Portfolio performance, hit rate, risk-adjusted returns |
| Final Recommendation | Standardized rating (Buy/Hold/Sell) & Target Price | Actionable sizing, entry/exit price bands, risk limits |
| Coverage Scope | Broad coverage (15–25 companies per analyst) | Deep focus on high-conviction ideas & watchlist stocks |
Valuation Variance in Identical Modeling Frameworks: The Role of Analyst Assumptions
A common phenomenon in financial markets occurs when two equity analysts utilize the exact same quantitative model—such as a Discounted Cash Flow (DCF) framework—to analyze the same company, yet arrive at vastly different target valuations. This divergence occurs because valuation models are dynamic mathematical functions dependent on qualitative judgment and forward-looking inputs. Minor variances in operational assumptions propagate through financial forecasts, creating substantial divergences in calculated intrinsic value.
The core variables responsible for valuation disparities within equity analyst research reports include revenue growth, profitability trajectories, reinvestment requirements, and financing capital structures.
+-----------------------------------------------------------------------------------+
|                           INPUT ASSUMPTION VARIANCE                               |
+--------------------------+--------------------------+-----------------------------+
| Revenue Drivers          | Profitability Drivers    | Investment & Capital Drivers|
| • Top-down vs. Bottom-up | • Gross Margin Expansion | • CapEx Intensity           |
| • TAM & Penetration Rates| • Operating Leverage     | • Working Capital Efficiency|
| • Pricing Power          | • Fixed Overhead Scalability• WACC & Capital Structure    |
+--------------------------+--------------------------+-----------------------------+
                                       |
                                       v
+-----------------------------------------------------------------------------------+
|                        FINANCIAL MODEL TRANSFORMATIONS                            |
|                 (Free Cash Flow to Firm & Terminal Value Calculations)            |
+-----------------------------------------------------------------------------------+
                                       |
                                       v
+-----------------------------------------------------------------------------------+
|                            DIVERGENT VALUATION OUTPUT                             |
|  Bull Case Target: USD150/share   |  Base Case: USD95/share  |  Bear Case: USD52/share|
+-----------------------------------------------------------------------------------+
Revenue Growth Assumptions: Market Sizing, Adoption Curves, and Pricing Power
Revenue projection is the primary driver of top-line forecasting in financial modeling. Analysts must estimate total market expansion, competitive share gain or loss, and pricing power.
- Top-Down vs. Bottom-Up Forecasting: A top-down analyst projects total industry TAM and assigns a target market share percentage to the firm. A bottom-up analyst models unit sales volumes, production capacity constraints, store count additions, and average selling prices (ASP).
- Adoption Curves and Disruption: When evaluating high-growth or disruptive companies like Tesla or AI hardware leader NVIDIA, optimistic analysts assume rapid adoption curves, sustained pricing premiums, and expanding recurring software subscription revenues. Conservative analysts factor in technological obsolescence, competitive price erosion, supply bottlenecks, and market saturation. A 3% variance in projected 10-year revenue compound annual growth rate (CAGR) can alter a company’s modeled DCF enterprise value by 30% to 50%.
Profitability Assumptions: Margin Trajectories, Operating Leverage, and Cost Structures
Converting top-line revenue into operating cash flows requires assumptions regarding gross margins and operating margins (EBIT/EBITDA margins).
- Operating Leverage Dynamics: Analysts evaluate fixed versus variable cost structures. Bullish analysts project strong operating leverage, assuming fixed overhead costs scale slowly relative to revenue expansion, expanding operating margins over time. Bearish analysts assume rising input costs, higher research and development (R&D) requirements, and aggressive sales and marketing expenses needed to retain market share.
- Structural Input Volatility: In consumer staples and food production companies like Nestlé, operating margins are highly sensitive to raw material cost inflation, agricultural commodity fluctuations, and packaging transportation overheads. An analyst assuming successful price pass-through to end consumers will model margin stability, whereas an analyst projecting consumer pushback will model margin compression, leading to significantly lower net income forecasts.
Investment Assumptions: Reinvestment Rates, CapEx Intensity, and Working Capital Dynamics
Cash flow available to equity and debt holders depends on the capital required to fund ongoing operations and growth. Free Cash Flow to Firm (FCFF) is calculated as:
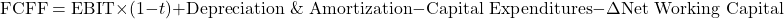
- Capital Expenditure (CapEx) Intensity: Capital-intensive industries require heavy ongoing reinvestment. For instance, semiconductor foundry TSMC spends over USD30 billion annually on advanced chip fabrication facilities (fabs). An analyst who models lower maintenance CapEx relative to revenue projects higher free cash flow generation. Conversely, an analyst who models sustained high CapEx intensity to maintain technological leadership forecasts reduced net cash flows, lowering intrinsic valuation.
- Working Capital Efficiency: Assumptions regarding inventory turnover, accounts receivable collection periods, and supplier payment terms (accounts payable) directly impact modeled cash conversion. Small changes in working capital requirements as a percentage of revenue growth can drain or boost projected annual cash balances.
Financing and Capital Structure Assumptions: Cost of Capital, WACC, and Capital Structure Evolution
The discount rate applied to future cash flows—the Weighted Average Cost of Capital (WACC)—exerts a compounding effect on valuation outputs. WACC is calculated as:
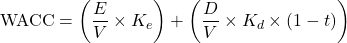
Where  is equity market value,
 is debt market value,
 ,
 is cost of equity,
 is cost of debt, and
 is the corporate tax rate.
- Cost of Equity () Sensitivity: Calculated via the Capital Asset Pricing Model (CAPM):
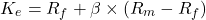
Small adjustments to the risk-free rate ( ), the equity risk premium (
 ), or the company’s equity beta (
 ) significantly alter . An analyst assigning a beta of 1.3 to a growth stock will derive a higher discount rate than an analyst assigning a beta of 1.0, reducing the present value of distant cash flows.
- Terminal Value Sensitivity: In a DCF, terminal value frequently accounts for 60% to 80% of total calculated enterprise value. The terminal growth rate (
 ) assumption represents long-term sustainable GDP growth (typically 2.0% to 3.0%). If Analyst A uses WACC = 8.5% and
 , the terminal capitalization rate
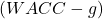 is 6.0%. If Analyst B conservatively uses WACC = 10.0% and
 , the capitalization rate expands to 8.0%. This 2.0% difference in capitalization rate reduces the calculated terminal value by 25%.
- Capital Structure Optimization: Energy majors like Shell manage significant debt obligations alongside ongoing share repurchase programs. Analysts assuming aggressive debt paydown model declining interest expense and lower financial risk, whereas analysts assuming sustained debt leverage incorporate higher debt risk premiums (), elevating WACC and depressing modeled equity value.
To illustrate how assumption variances alter valuation outcomes within an identical 10-year DCF framework, consider the quantitative sensitivity scenario below for a hypothetical global enterprise with base revenue of USD10,000 million (USD10 billion):
| Valuation Variable | Bear Case Assumptions | Base Case Assumptions | Bull Case Assumptions |
| 10-Year Revenue CAGR | 4.0% | 8.0% | 12.0% |
| Steady-State EBIT Margin | 15.0% | 20.0% | 25.0% |
| CapEx as % of Revenue | 9.0% | 7.0% | 5.0% |
| WACC (Discount Rate) | 11.0% | 9.5% | 8.0% |
| Terminal Growth Rate () | 1.5% | 2.5% | 3.0% |
| Calculated Enterprise Value | USD8,250 million | USD16,800 million | USD31,500 million |
| Implied Equity Value Per Share | USD52.00 | USD95.00 | USD150.00 |
As demonstrated above, using identical mathematical DCF formulas on the same initial corporate financial baseline yields target valuations ranging from USD52.00 to USD150.00 per share. This spread highlights why equity analyst research reports must be evaluated through the lens of underlying qualitative and quantitative assumptions rather than taking final target prices at face value.
Strategic Conclusion and Key Takeaways for Business Leaders
Equity analyst research reports are central to capital allocation, financial reporting, and corporate governance within global capital markets. For executive leadership, investors, financial managers, and academic researchers, understanding the structural anatomy of these reports provides valuable strategic context:
- Exhaustive Structure: A rigorous research report integrates qualitative strategic positioning, competitive moat analysis, three-statement modeling, absolute and relative valuation frameworks, and granular risk sensitivity testing.
- Institutional Context Matters: Sell-side reports provide broad market coverage, industry benchmarking, and liquidity generation, but may exhibit structural optimism bias. Buy-side reports offer unhedged, risk-adjusted proprietary conclusions designed directly for portfolio execution and risk mitigation.
- Critical Evaluation of Assumptions: Intrinsic valuation models are highly sensitive to forward-looking operational inputs. Minor variances in forecasted revenue growth, operating margins, CapEx intensity, and discount rates create divergent target prices.
By systematically evaluating the underlying assumptions embedded within equity research, business professionals can better interpret capital market signals, communicate effectively with investor relations desks, and execute capital strategies that drive sustainable, long-term shareholder value.
