Private Company Valuation serves as an indispensable discipline in corporate finance, financial analysis, and strategic investment management, enabling equity research analysts, private equity investors, and corporate advisors to establish the fair market value of non-publicly traded enterprises.
This comprehensive guide examines the structural features distinguishing private and public entities, analyzes key valuation approaches—including income, market, and asset-based methods—and demonstrates step-by-step mathematical calculations required to estimate normalized earnings, discount rates, control premiums, and discounts for lack of marketability across global businesses.
Contrasting Public and Private Company Features for Valuation
Determining the economic worth of an enterprise requires an understanding of how institutional structures, regulatory requirements, and ownership profiles impact financial performance and risk. While public corporations operate under standardized disclosure regimes and continuous public market pricing, private enterprises exhibit specific operating and financial characteristics that directly influence Private Company Valuation.
+------------------------------------+------------------------------------+
| Feature                            | Public Companies                   |
+------------------------------------+------------------------------------+
| Liquidity & Marketability          | Continuous exchange trading        |
| Information Transparency           | Mandatory SEC/IFRS filings         |
| Access to Capital                  | Direct public debt & equity        |
| Ownership Structure                | Dispersed public shareholders      |
| Management & Control               | Separated ownership & management   |
+------------------------------------+------------------------------------+
Liquidity and Share Marketability
Publicly traded corporations such as Apple and Microsoft benefit from frictionless secondary trading on major stock exchanges. Investors can convert equity stakes into cash almost instantaneously with nominal transaction fees and minimal market impact. Conversely, shares in private firms like Cargill or Mars, Incorporated lack an established trading venue. Selling a private equity position entails substantial search costs, legal fees, due diligence periods, and price concessions, creating a marketability deficit that valuation professionals must address through explicit discount factors.
Information Transparency and Accounting Standards
Public companies are subject to rigorous regulatory oversight, requiring quarterly and annual audited statements compiled under International Financial Reporting Standards (IFRS) or Generally Accepted Accounting Principles (GAAP). Private businesses maintain varying levels of disclosure quality. Financial reporting in smaller private entities is often driven by tax minimization strategies rather than economic truth, resulting in distorted earnings figures that require extensive normalization adjustments.
Capital Access and Cost of Capital
Public entities enjoy direct access to primary equity markets and commercial bond markets, allowing them to optimize their capital structures at lower marginal costs. Private companies rely primarily on founder equity, retained earnings, commercial bank loans, private credit, or venture capital funding. This restricted capital access increases financial distress risk and yields a higher weighted average cost of capital (WACC).
Ownership Concentration and Agency Dynamics
Public firms exhibit dispersed shareholder bases, creating classical agency problems where executive management acts separately from capital providers. In contrast, private companies feature concentrated ownership—frequently centered on founders, families, or private equity funds like Blackstone. While concentrated ownership eliminates traditional agency costs, it introduces key-person dependencies, potential oppression of minority shareholders, and overlapping personal and corporate expenses.
| Valuation Dimension | Public Companies | Private Companies | Valuation Impact on Private Firms |
| Share Liquidity | High (Exchange Traded) | Low / Non-existent | Requires Discount for Lack of Marketability (DLOM) |
| Financial Reporting | Audited (GAAP/IFRS) | Variable / Tax-Focused | Requires Earnings Normalization Adjustments |
| Capital Access | Broad (Public Debt/Equity) | Restricted (Banks/VC/PE) | Elevates Cost of Equity and Total WACC |
| Governance Structure | Independent Board | Owner-Managed / Family | Key-Person Risk & Minority Discount Considerations |
| Strategic Horizon | Quarterly Market Pressures | Long-Term / Family Goals | Adjusts Investment & Reinvestment Projections |
Uses of Private Business Valuation and Key Areas of Focus for Financial Analysts
Private Company Valuation is required across financial, corporate, legal, and regulatory environments. Financial analysts must tailor their analytical scope to the underlying purpose of the appraisal.
Primary Uses of Private Business Valuation
- Transactional Contexts: Mergers and acquisitions (M&A), private equity leveraged buyouts (LBOs), venture capital funding rounds in growth firms like ByteDance or Stripe, management buyouts (MBOs), and Initial Public Offerings (IPOs).
- Legal and Tax Compliance: Tax appraisals for gift and estate transfers, corporate reorganizations, shareholder buyout disputes, insolvency proceedings, and marital dissolution litigation.
- Financial Reporting: Purchase price allocations (PPA) under IFRS 3 / ASC 805, goodwill impairment testing, and executive share-based compensation valuation under Section 409A.
- Strategic Planning: Partner buy-sell agreements, capital budgeting decisions, and corporate performance monitoring.
Core Focus Areas for Financial Analysts
When conducting a Private Company Valuation, financial analysts focus on four core operational pillars:
- Lifecycle Stage and Competitive Moat: Assessing whether the target firm is an early-stage venture, a high-growth scale-up like Klarna, a mature cash-generator, or a distressed asset. Analysts evaluate market share retention, customer acquisition costs, and competitive barriers.
- Management Depth and Key-Person Risk: Private middle-market businesses frequently depend on a single founder or executive officer for sales generation, client relationships, and operational direction. Analysts evaluate succession plans and key-person life insurance to determine risk premiums.
- Quality of Earnings (QoE): Rigorously scrutinizing historical income statements to eliminate accounting distortions, personal discretionary expenses, and non-arm’s-length related-party transactions.
- Capital Structure and Non-Operating Assets: Distinguishing core operating assets from redundant, non-operating assets (e.g., excess real estate holdings, corporate aircraft, non-functional cash balances) to ensure accurate Enterprise-to-Equity value bridges.
Cash Flow Estimation Issues and Adjustments for Normalized Earnings
Historical financial statements of private companies rarely reflect the true underlying economic earning power of the business. Consequently, financial analysts perform normalization adjustments to determine Normalized EBITDA or Normalized Free Cash Flow.
Common Adjustments to Reported Financials
- Owner Compensation Realignment: Founder-owners often draw compensation above or below market rates depending on corporate tax strategies. Analysts replace actual executive compensation with arm’s-length replacement costs based on industry benchmark data.
- Discretionary and Personal Expenses: Private firm accounts frequently contain personal travel, country club memberships, non-business automobiles, and personal legal fees. These non-essential items must be added back to operating income.
- Related-Party Rent Adjustments: If a private business leases operating facilities from an entity owned by the same proprietor, the rent charged may diverge from market rates. Analysts adjust property lease expenses to fair market rental rates.
- Non-Recurring and Out-of-Period Items: Eliminating one-off legal settlements, restructuring costs, gains or losses on asset sales, hurricane losses, or extraordinary bad debt write-offs.
Normalized EBITDA Reconciliation Example
Consider a mid-sized private manufacturing firm, Global Tech Solutions Inc., which reported an EBITDA of USD8,000,000 for the fiscal year. The company’s income statement includes owner compensation of USD2,500,000 (market benchmark replacement cost is USD800,000), personal auto expenses of USD150,000, related-party real estate rent of USD600,000 (market rent is USD1,000,000), and a single legal settlement expense of USD450,000.
| Line Item | Reported Value | Adjustment Direction | Adjustment Amount | Normalized Value |
| Reported EBITDA | USD8,000,000 | — | — | USD8,000,000 |
| Executive Compensation Adjustment | USD2,500,000 | Add-back (Overpayment) | +USD1,700,000 | USD800,000 Benchmark |
| Discretionary Personal Expenses | USD150,000 | Add-back | +USD150,000 | USD0 |
| Related-Party Lease Adjustment | USD600,000 | Deduction (Underpayment) | -USD400,000 | USD1,000,000 Market |
| Non-Recurring Legal Settlement | USD450,000 | Add-back | +USD450,000 | USD0 |
| Normalized EBITDA | — | — | +USD1,900,000 | USD9,900,000 |
After adjusting for non-arm’s-length transactions and non-recurring items, the true underlying economic earning power of the firm reflects a Normalized EBITDA of USD9,900,000.
Discount Rate Adjustments for Private Companies
Estimating the discount rate—specifically the cost of equity ( ) and Weighted Average Cost of Capital (
 )—for private companies presents analytical challenges due to the absence of public share price observations and public credit ratings.
Key Adjustment Factors for Private Firm Risk
- Size Premium (
 ): Empirical financial literature demonstrates that smaller firms exhibit higher return volatility, restricted capital access, and higher business failure rates than large-cap equities. Analysts incorporate an explicit size premium based on market capitalizations of comparable public deciles.
- Specific Company Risk Premium (
 ): Captures unsystematic risks unique to the target firm, such as severe customer concentration (e.g., a single client accounting for 35% of revenue), key-person dependency, product line obsolescence, regulatory exposures, or weak internal accounting controls.
- Capital Structure Selection: Because private company market debt-to-equity ratios cannot be directly observed on an exchange, analysts utilize a target capital structure based on public industry peers or optimal leverage ratios.
- Cost of Debt Estimation: Private businesses lack public credit ratings. Analysts estimate the cost of debt (
 ) by examining recent bank borrowing rates, calculating coverage ratios to estimate synthetic credit ratings, or assessing private placement yield spreads.
Comparing Models for Required Rate of Return on Private Company Equity
Financial analysts employ three principal frameworks to calculate the required rate of return on private equity investments: the standard Capital Asset Pricing Model (CAPM), the Expanded CAPM, and the Build-Up Approach.
Capital Asset Pricing Model (CAPM)
The standard CAPM derives the cost of equity based on systematic risk ( ):
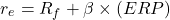
Where  is the risk-free rate and
 is the equity risk premium. For private companies, analysts select public peer companies, unlever their equity betas to eliminate the impact of public firm leverage, and relever the average asset beta using the private firm’s target financial leverage:
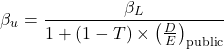
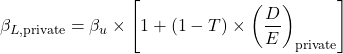
Expanded CAPM
Because standard CAPM accounts only for systematic market risk, it understates the return demanded by private equity investors. The Expanded CAPM introduces explicit adjustments for size and company-specific risks:
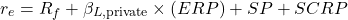
Build-Up Approach
When reliable public peer betas are unavailable or peer business models diverge significantly, analysts deploy the Build-Up Approach. This model bypasses beta entirely and constructs the cost of equity from risk components:
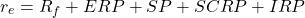
Where  represents an Industry Risk Premium reflecting specific macroeconomic and competitive headwinds facing the firm’s operating sector.
| Feature / Metric | Capital Asset Pricing Model (CAPM) | Expanded CAPM | Build-Up Approach |
| Formula Structure | 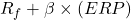 | 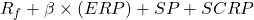 | 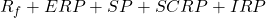 |
| Beta Requirement | Mandatory (Unlevered/Relevered) | Mandatory (Unlevered/Relevered) | Not Required |
| Size Premium () | Excluded | Explicitly Included | Explicitly Included |
| Company Risk () | Excluded | Explicitly Included | Explicitly Included |
| Primary Application | Large-Cap Public Subsidiaries | Mid-Market Private Companies | Small/Micro Private Firms |
Discounts and Premiums in Private Company Valuation
Valuation conclusions depend heavily on the level of control and marketability associated with the subject equity stake. Analysts modify unadjusted equity values using control premiums and marketability discounts.
                  +-----------------------------------+
                  |  Control, Marketable Interest     |
                  +-----------------------------------+
                                    |
                                    | Subtract DLOC
                                    v
                  +-----------------------------------+
                  | Minority, Marketable Interest     |
                  +-----------------------------------+
                                    |
                                    | Subtract DLOM
                                    v
                  +-----------------------------------+
                  | Minority, Non-Marketable Interest |
                  +-----------------------------------+
Control Premium and Discount for Lack of Control (DLOC)
A controlling interest grants an investor the authority to select executive leadership, dictate strategic growth initiatives, allocate capital, execute M&A transactions, declare dividends, or liquidate assets. Consequently, controlling equity commands a higher valuation than a non-controlling (minority) interest.
When a valuation model generates an unadjusted value on a controlling basis, a Discount for Lack of Control (DLOC) must be applied to value a minority position. DLOC is mathematically derived from observed M&A Control Premiums ( ):
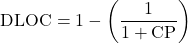
For example, if the average M&A Control Premium observed in an industry is 25%, the corresponding DLOC is calculated as:
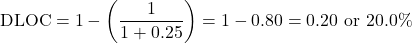
Discount for Lack of Marketability (DLOM)
Even after adjusting for control, private shares cannot be sold immediately on an organized exchange. The Discount for Lack of Marketability (DLOM) compensates investors for holding an illiquid asset. Quantitative models used to estimate DLOM include:
- Restricted Stock Studies: Comparing market prices of publicly traded shares against restricted, non-saleable shares of the same issuing corporation.
- Pre-IPO Studies: Comparing transaction prices of private share transfers prior to an IPO against the ultimate public offering price.
- Option Pricing Models: Utilizing put-option pricing frameworks (such as the Chaffe model or Finnerty model) where marketability is viewed as a protective put option to lock in value over a holding period.
Combined Discounts Application
Discounts are multiplicative rather than additive. Applying a 20% DLOC and a 25% DLOM sequentially yields the total effective discount factor:
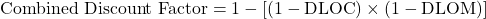
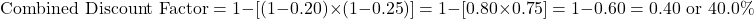
Valuation Approaches: Income, Market, and Asset-Based Methods
Financial analysts evaluate three primary frameworks to determine private business value, selecting the approach that best aligns with the company’s operating profile and data availability.
                       +-------------------------------+
                       |  Private Company Valuation   |
                       +-------------------------------+
                                       |
        +------------------------------+------------------------------+
        |                              |                              |
        v                              v                              v
+---------------+              +---------------+              +---------------+
|    Income     |              |    Market     |              |  Asset-Based  |
|  Approach     |              |   Approach    |              |   Approach    |
+---------------+              +---------------+              +---------------+
| * DCF Model   |              | * GPCM        |              | * Adjusted Net|
| * CCF Model   |              | * GTM         |              |   Asset Method|
|               |              | * Prior Trades|              |               |
+---------------+              +---------------+              +---------------+
Income Approach
The Income Approach establishes value based on the present value of anticipated future economic cash flows generated by the enterprise.
- Discounted Cash Flow (DCF) Method: Utilizes explicit multi-year forecasts of Free Cash Flow to Firm (FCFF) or Free Cash Flow to Equity (FCFE), discounted at WACC or cost of equity, plus a discounted Terminal Value. Best suited for growth companies or businesses with volatile cash flow projections.
- Capitalized Cash Flow (CCF) Method: Capitalizes a single representative normalized cash flow stream assuming a constant perpetual growth rate (
 ). Best suited for stable, mature private enterprises like established regional distributors.
Market Approach
The Market Approach estimates value relative to observed pricing multiples of comparable assets.
- Guideline Public Company Method (GPCM): Applies valuation multiples (e.g., Enterprise Value to EBITDA, Price-to-Earnings) derived from publicly traded peer companies like Tata Group subsidiaries to the normalized metrics of the target firm.
- Guideline Transactions Method (GTM): Utilizes valuation multiples established in historical M&A acquisitions of private or public peer entities.
- Prior Transactions Method: Examines historical arm’s-length equity sales of the target firm’s own capital stock.
Asset-Based Approach
The Asset-Based Approach establishes value by revaluing all tangible and intangible assets and liabilities of the firm to current Fair Market Value (FMV).
- Adjusted Net Asset Method: Calculates value as Adjusted FMV Assets minus Adjusted FMV Liabilities. Primary application areas include asset-heavy holding entities, real estate investment companies, natural resource firms, or distressed companies facing liquidation.
| Valuation Approach | Primary Methodologies | Best Suited For | Main Selection Factors |
| Income Approach | DCF Model, CCF Model | Cash-generative operating firms with clear forecasts | Availability of long-term cash flow projections |
| Market Approach | GPCM, GTM, Prior Trades | Mature operating firms in active M&A industries | Existence of robust, truly comparable peer companies |
| Asset-Based Approach | Adjusted Net Asset Method | Holding companies, real estate, liquidation targets | High tangible asset proportion; low goodwill component |
Income-Based Valuation: Worked Calculation Example
To illustrate the mathematical execution of the Income Approach, we conduct a Free Cash Flow to Firm (FCFF) DCF valuation for Apex Logistics Ltd., a private middle-market transport enterprise.
Valuation Parameters and Cost of Capital Setup
- Base Year Normalized Revenue: USD20,000,000
- Base Year Normalized EBIT: USD3,200,000
- Corporate Tax Rate (
 ): 25.0%
- Expected Explicit Forecast Growth Rate (
 ): 5.0% per year for 5 years
- Perpetual Growth Rate (
 ): 3.0%
- Depreciation & Amortization: USD600,000 in Year 1 (growing at 5.0% annually)
- Capital Expenditures (CapEx): USD800,000 in Year 1 (growing at 5.0% annually)
- Change in Net Working Capital (
 ): USD200,000 in Year 1 (growing at 5.0% annually)
Cost of Capital (WACC) Derivation
- Cost of Equity () via Expanded CAPM:
- Risk-Free Rate (): 4.0%
- Equity Risk Premium (): 5.0%
- Relevered Beta (
 ): 1.10
- Size Premium (): 2.5%
- Specific Company Risk Premium (): 2.0%
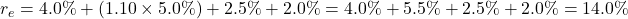
- Risk-Free Rate (
- After-Tax Cost of Debt ():
- Pre-tax interest rate on debt: 7.0%
- After-tax cost of debt:
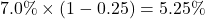
- Target Capital Structure: Debt Weight (
 ) = 20.0%, Equity Weight (
 ) = 80.0%
- WACC Calculation:
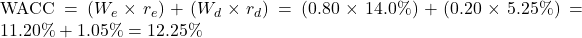
Five-Year FCFF Explicit Forecast Calculation
For each forecast year, 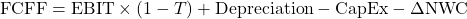 .
- Year 1:
- Year 2:
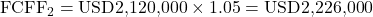
- Year 3:
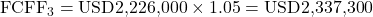
- Year 4:
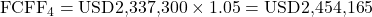
- Year 5:
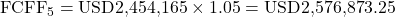
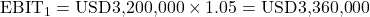
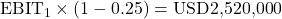
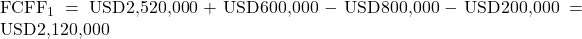
| Metric / Year | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 |
| Normalized EBIT | USD3,360,000 | USD3,528,000 | USD3,704,400 | USD3,889,620 | USD4,084,101.00 |
EBIT  (1 – T) | USD2,520,000 | USD2,646,000 | USD2,778,300 | USD2,917,215 | USD3,063,075.75 |
| + Depreciation | USD600,000 | USD630,000 | USD661,500 | USD694,575 | USD729,303.75 |
| – CapEx | -USD800,000 | -USD840,000 | -USD882,000 | -USD926,100 | -USD972,405.00 |
–  NWC | -USD200,000 | -USD210,000 | -USD220,500 | -USD231,525 | -USD243,101.25 |
| Unadjusted FCFF | USD2,120,000 | USD2,226,000 | USD2,337,300 | USD2,454,165 | USD2,576,873.25 |
Discount Factor ( ) | 0.8908686 | 0.7936468 | 0.7070351 | 0.6298753 | 0.5611362 |
| Present Value of FCFF | USD1,888,641.43 | USD1,766,657.78 | USD1,652,553.14 | USD1,545,818.17 | USD1,445,977.10 |
Cumulative Explicit Period PV
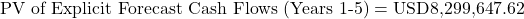
Terminal Value and Total Enterprise Value Bridge
- Year 6 Terminal FCFF:
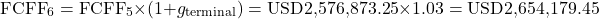
- Terminal Value at Year 5 (
 ):
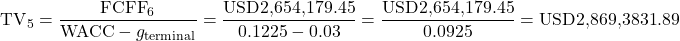
- Present Value of Terminal Value:
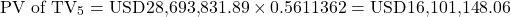
- Total Enterprise Value (EV):
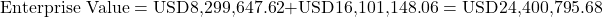
- Bridge to Non-Marketable Minority Equity Value:
- Less Total Outstanding Debt: USD4,000,000
- Plus Non-Operating Cash & Assets: USD1,000,000
- Controlling Interest Equity Value:
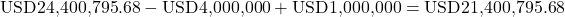
- Apply DLOC (15.0%):
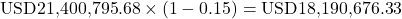
- Apply DLOM (20.0%):
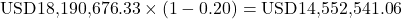
- Final Indicated Non-Marketable Minority Equity Value: USD14,552,541.06
Market-Based Valuation: Worked Calculation Example, Advantages, and Disadvantages
The Market Approach determines value relative to market transactions involving similar enterprises.
Worked Example: Guideline Public Company Method (GPCM)
An analyst evaluates Precision Components Corp., a private firm with Normalized EBITDA of USD10,000,000, interest-bearing debt of USD15,000,000, and cash reserves of USD3,500,000.
- Peer Group Analysis: A peer group of four publicly traded component suppliers yields a median Enterprise Value to EBITDA (
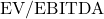 ) multiple of
 .
- Qualitative Multiple Adjustment: Precision Components is smaller and less diversified than public peers, justifying a 10.0% multiple discount.
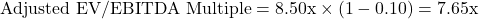
- Indicated Enterprise Value:
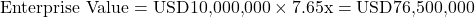
- Equity Value Calculation:
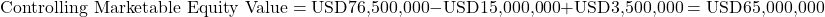
- Application of Marketability Discount: Because public multiples reflect liquid market pricing, a 18.0% DLOM is applied to estimate the non-marketable value:
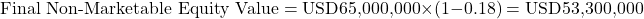
| Market Method | Key Advantages | Major Disadvantages |
| Guideline Public Company Method (GPCM) | Based on observable public market pricing; defensible in court | Public peer comparability is often limited; requires size/risk adjustments |
| Guideline Transactions Method (GTM) | Reflects real M&A transaction prices including full control premiums | M&A data is often historical, confidential, or outdated |
| Prior Transactions Method | Uses actual price data from target firm’s capital history | Prior funding rounds may reflect different rights or preferential terms |
Conclusion
Private Company Valuation requires a clear understanding of financial theory, market dynamics, and accounting normalization techniques. Because private businesses lack continuous market pricing, analysts must adjust financial reporting data, construct build-up or expanded CAPM discount rates, and account for marketability and control differences. By balancing the Income, Market, and Asset-Based approaches, financial analysts, corporate managers, and advisors can establish sound, defensible valuations across non-public enterprises worldwide.
