Understanding the fundamental mechanics of an Asset-Backed Security Instrument and Market Features is vital for corporate treasurers, institutional portfolio managers, risk officers, and financial regulators navigating the global capital markets.
Securitization transforms illiquid, cash-flow-generating financial assets—ranging from residential mortgages and auto loans to credit card receivables and corporate loans—into tradeable debt securities.
By isolating specific asset pools within specialized legal frameworks, securitization enables financial institutions to optimize capital allocation, diversify funding sources, and transfer credit risk to investors seeking tailored risk-return profiles.
Covered Bonds vs. Asset-Backed Securities: Structural Architecture and Risk Profiles
Covered bonds and traditional Asset-Backed Securities (ABS) represent two foundational pillars of debt capital markets. While both instruments are collateralized by pools of underlying financial assets—predominantly residential or commercial mortgages and public-sector loans—their structural mechanics, balance sheet treatments, and investor risk profiles differ fundamentally.
Structural Mechanics and the Dual Recourse Mechanism
The defining characteristic of a covered bond is its dual recourse structure. When an investor purchases a covered bond issued by a financial institution, such as BNP Paribas or Société Générale, the bondholder receives two distinct layers of protection:
- Direct Issuer Recourse: The covered bond remains a senior unsecured obligation of the issuing financial institution. The issuer is legally obligated to make interest and principal payments from its general corporate cash flows.
- Cover Pool Recourse: The bond is backed by a dedicated “cover pool” of high-quality assets (such as prime residential mortgages or public sector debt). If the issuing bank defaults or enters insolvency proceedings, covered bondholders maintain a preferential claim over the assets in the cover pool, which are legally ring-fenced from the issuer’s general bankruptcy estate.
In stark contrast, standard ABS transactions utilize an off-balance-sheet Special Purpose Entity (SPE) or Special Purpose Vehicle (SPV). The originating bank transfers the underlying receivables to the SPE via a bankruptcy-remote “true sale.” Consequently, ABS investors have recourse solely to the cash flows generated by the isolated collateral pool held within the SPE, holding no legal claim against the originating financial institution if asset defaults escalate.
+-----------------------------------------------------------------------------------+
|                                  COVERED BONDS                                    |
|  +-----------------------+                         +---------------------------+  |
|  |  Originating Bank     |<=======================>|  Cover Pool (On-Balance)  |  |
|  |  (Full Issuer Debt)   |  Ring-Fenced Recourse   |  Dynamic Asset Pool       |  |
|  +-----------------------+                         +---------------------------+  |
|              ||                                                                   |
|              || Dual Recourse Protection                                          |
|              \/                                                                   |
|  +-----------------------+                                                        |
|  |  Covered Bond Investors|                                                       |
|  +-----------------------+                                                        |
+-----------------------------------------------------------------------------------+

+-----------------------------------------------------------------------------------+
|                             ASSET-BACKED SECURITIES (ABS)                         |
|  +-----------------------+      True Sale          +---------------------------+  |
|  |  Originating Bank     |------------------------>| Special Purpose Entity    |  |
|  |  (Originator/Servicer)|  Off-Balance Sheet      | (Bankruptcy-Remote SPV)   |  |
|  +-----------------------+                         +---------------------------+  |
|                                                                 ||                |
|                                                     Single      || Cash Flow      |
|                                                     Recourse    \/ Waterfall      |
|                                                    +---------------------------+  |
|                                                    |   ABS Tranche Investors   |  |
|                                                    +---------------------------+  |
+-----------------------------------------------------------------------------------+
Dynamic Cover Pools versus Static Asset Pools
Covered bonds feature dynamic cover pools managed directly on the issuer’s balance sheet. The issuer must continuously monitor the cover pool to ensure that asset values, interest income, and credit quality meet statutory overcollateralization requirements. If an underlying mortgage defaults or pays off early, the issuer is legally required to replace it with a qualifying performing asset.
Traditional ABS collateral pools are typically static or pre-identified at issuance (except in revolving structures like credit card ABS). In a static ABS, degraded collateral is not replaced by the originator unless there was a breach of legal representations and warranties made at the origination date.
Risk Characteristics and Yield Differentials
Because of dual recourse and mandatory dynamic substitution, covered bonds exhibit lower credit risk than traditional ABS notes backed by similar mortgage assets. Major European issuers like Barclays issue regulated covered bonds that almost universally attain AAA credit ratings. Risk factors in covered bonds primarily center on systemic banking sector insolvency, asset-liability mismatches (such as interest rate or currency risk between the cover pool and the debt issued), and regulatory changes governing cover pool administration.
Standard ABS structures trade at wider credit spreads than covered bonds to compensate investors for accepting standalone asset credit risk, prepayment volatility, and structural complexity without corporate backstopping from the originator.
| Structural Feature | Covered Bonds | Asset-Backed Securities (ABS) |
| Recourse Mechanism | Dual recourse (Issuer + Ring-fenced cover pool) | Single recourse (Isolated SPE collateral pool only) |
| Balance Sheet Treatment | On-balance-sheet obligation of issuing bank | Off-balance-sheet transfer via true sale to SPE |
| Collateral Management | Dynamic pool (non-performing assets replaced) | Static pool (or revolving pool defined by strict rules) |
| Credit Rating Drivers | Joint probability of issuer default and pool failure | Standalone collateral quality and credit enhancement |
| Prepayment Risk | Absorbed largely by issuer via pool substitution | Passed through directly to tranche investors |
| Default Redemption | Accelerated payment or pool cover manager payout | Sequential loss allocation down the structural waterfall |
Credit Enhancement Structures in Securitizations
To market structured debt instruments to institutional investors, securitization transactions incorporate credit enhancements. Credit enhancement absorbs underlying credit losses, mitigates cash flow volatility, and elevates the credit ratings of senior note tranches above the average rating of the underlying unrated or non-investment-grade collateral pool. Arrangers like Citigroup and JPMorgan Chase structure credit enhancements through internal and external mechanisms.
Internal Credit Enhancement Mechanisms
Internal credit enhancements rely on the structural design and cash flow distribution rules established within the SPE governing documents.
Subordination and Senior-Subordinated Waterfalls
Subordination creates a prioritized hierarchy of note tranches (often rated AAA down to BB, ending with an unrated equity tranche). Cash flows generated by the asset pool are distributed according to a strict payment waterfall: senior tranches receive interest and principal payments first. Conversely, realized credit losses are absorbed in reverse order, starting with the unrated equity/first-loss tranche and moving up through mezzanine tranches before affecting senior notes.
For example, in a USD1 billion ABS issue:
- Senior Tranche (Class A): USD800 million (80% subordination protection, rated AAA)
- Mezzanine Tranche (Class B): USD120 million (8% subordination protection, rated AA/A)
- Junior Tranche (Class C): USD50 million (3% subordination protection, rated BBB)
- Equity Tranche (Subordinated): USD30 million (First-loss position, unrated)
The Class A notes will not suffer principal losses until aggregate collateral defaults exceed USD200 million (the sum of Classes B, C, and Equity).
Overcollateralization
Overcollateralization (OC) occurs when the total principal balance of the underlying collateral pool exceeds the total par value of the debt securities issued by the SPE. For instance, an originator may transfer USD550 million in consumer loan receivables to an SPE but issue only USD500 million in ABS notes. The USD50 million differential acts as an immediate capital cushion that absorbs initial default losses before any noteholder experiences a principal write-down.
Excess Spread and Reserve Accounts
Excess spread represents the net interest margin generated by the SPE. It is calculated as the total interest collected from the underlying asset pool minus the interest payable to noteholders and all senior servicing, trustee, and administrative fees.
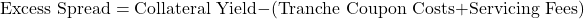
If a collateral pool yields 8.50% per annum, weighted average coupon payments across all issued note classes total 3.20%, and annual servicing fees equal 0.50%, the SPE generates an excess spread of 4.80% per annum (USD48 million annually on a USD1 billion pool).
Excess spread is typically trapped in a cash reserve account managed by the trustee. This reserve account builds up over time to absorb collateral charge-offs. If unused losses remain below specified thresholds, excess spread cash flows may eventually be released to the equity tranche equity holders as residual profit.
External Credit Enhancement Mechanisms
External credit enhancements involve third-party financial institutions providing financial guarantees to backstop SPE payment obligations.
Financial Guarantees and Monoline Insurance
A monoline insurance policy or financial guarantee is an unconditional contract issued by a highly rated specialized insurer. The monoline insurer guarantees the timely payment of interest and ultimate repayment of principal on specific senior ABS tranches. If underlying asset cash flows prove insufficient, the guarantor pays the shortfall directly to the SPE trustee.
Letters of Credit and Bank Guarantees
Commercial banks can issue a Letter of Credit (LOC) or credit facility covering a predetermined dollar amount (e.g., 5% to 10% of total deal par value). The SPE trustee draws upon the LOC if cash flow shortfalls threaten scheduled interest or principal payments on rated tranches.
Cash Collateral Accounts and Liquidity Facilities
A cash collateral account is an external deposit provided at deal inception by a third-party lender or the originator. Held in safe liquid instruments (such as overnight Treasury reverse repos), this fund provides liquidity support during temporary payment delays, such as loan servicer transfer delays or seasonal payment lulls.
| Enhancement Structure | Mechanism Type | Operational Function | Primary Risk / Cost |
| Subordination | Internal | Allocates default losses sequentially from bottom tranches upward | High yield required by junior/equity tranche investors |
| Overcollateralization | Internal | Collateral par value exceeds issued debt face value | Ties up originator capital in unissued equity |
| Excess Spread | Internal | Traps net yield differential to fund credit loss reserves | Reduced residual cash flow return to originator |
| Monoline Guarantees | External | Third-party insurance policy guarantees interest/principal | Exposure to guarantor rating downgrades and premium fees |
| Letter of Credit (LOC) | External | Third-party commercial bank facility covers cash shortfalls | Counterparty risk and ongoing LOC commitment fees |
| Cash Collateral Account | External | Pre-funded cash deposit available for immediate liquidity draw | Cost of funds required to maintain upfront cash balance |
Non-Mortgage Asset-Backed Securities: Types, Cash Flows, and Risk Dynamics
Non-mortgage Asset-Backed Securities represent a substantial portion of global fixed-income trading. The primary non-mortgage ABS sectors include auto loans and leases, credit card receivables, student loans, and commercial equipment leases. Each asset class possesses unique structural features, cash flow profiles, and credit risk factors.
Auto Loan and Lease ABS
Automobile ABS issuances are originated primarily by captive finance subsidiaries of major automakers, such as Ford Motor Credit Company, as well as commercial banks and independent consumer lenders.
+-----------------------------------------------------------------------------------+
|                           AUTO LOAN / LEASE ABS STRUCTURE                         |
|                                                                                   |
|  +--------------------+         Monthly Payments         +---------------------+  |
|  | Retail Consumers   |=================================>| Servicer / Trustee  |  |
|  | (Borrowers/Lessees)| (Principal + Interest + Residual)| (Ford Credit)       |  |
|  +--------------------+                                  +---------------------+  |
|                                                                     ||            |
|                                         Pass-Through Cash Flows     ||            |
|                                                                     \/            |
|  +--------------------+    Amortizing Monthly Payouts    +---------------------+  |
|  | ABS Noteholders    |<=================================| SPE Issue Structure |  |
|  | (Class A, B, C)    |  (Sequential or Pro-Rata)        | (Fully Amortizing)  |  |
|  +--------------------+                                  +---------------------+  |
+-----------------------------------------------------------------------------------+
Cash Flow Mechanics
Auto loan ABS are backed by pools of fully amortizing retail installment sale contracts. Cash flows consist of scheduled monthly principal and interest payments alongside voluntary prepayments. Auto lease ABS include an additional cash flow component: the residual value of the leased vehicles realized at lease expiration through consumer vehicle purchases or wholesale dealer auctions.
Risk Profiles
- Prepayment Risk: Borrowers prepay auto loans due to vehicle sales, trade-ins, refinancing, or total loss insurance payouts. Prepayments in auto ABS are measured using the Absolute Prepayment Speed (ABS) model, which expresses monthly prepayments as a percentage of the original collateral pool balance.
- Credit Risk: Auto loan defaults correlate with consumer macroeconomic stress, unemployment spikes, and falling personal income levels. Subprime auto ABS deals incorporate higher initial subordination and overcollateralization to cushion against charge-offs.
- Residual Value Risk: Exclusive to auto lease ABS, residual value risk arises when the market value of returned vehicles at lease end falls below the contractually predicted residual value set at lease signing. Weak used-car market prices reduce realized sales proceeds at auction, reducing SPE cash flows.
Credit Card Receivable ABS
Credit card receivables represent unsecured revolving lines of credit extended to retail consumers. Originators such as Capital One issue credit card ABS using “Master Trust” issuance vehicles.
Cash Flow Mechanics and Trust Architecture
Credit card ABS receivables do not amortize on a fixed schedule. Instead, cardholders make variable monthly payments comprising interest, finance charges, annual fees, late penalties, and voluntary principal repayments. Master trusts allow card originators to pool billions of dollars in receivables and issue multiple series of notes over time backed by the same overarching asset pool.
Credit card ABS structures divide cash flows into two operational periods:
- Revolving Period: Typically lasting from 1 to 5 years, noteholders receive monthly interest payments only. All principal payments received from consumers are retained by the SPE and reinvested immediately to purchase newly generated credit card receivables from the originator.
- Accumulation or Amortization Period: Following the revolving period, the trust stops purchasing new receivables. Principal collections are accumulated in a controlled distribution account or paid out sequentially to noteholders until the debt classes are fully redeemed.
Early Amortization Triggers and Risk Drivers
Credit card ABS feature early amortization (or payout) triggers designed to protect senior noteholders before severe asset degradation occurs. An early amortization event is triggered if the three-month average excess spread drops below 0%, if borrower default rate spikes exceed specified covenants, or if the originator experiences corporate insolvency. If triggered, the revolving period terminates immediately, and all available cash flows are redirected exclusively to pay down note principal sequentially.
Primary risk factors include:
- Gross Charge-Off Rates: Unsecured credit card receivables carry higher loss rates during economic downturns than secured auto or mortgage loans.
- Payment Rates: The monthly payment rate represents the proportion of total receivables balance repaid by cardholders each month. A decline in payment rates extends the time required to pay off note principal during the amortization phase.
Student Loan ABS (SLABS)
Student Loan ABS are collateralized by pools of higher education loans. These instruments fall into two distinct legal categories: Federal Family Education Loan Program (FFELP) loans and Private Student Loans.
Cash Flow Mechanics
Student loan cash flows feature unique lifecycle phases:
- In-School and Grace Periods: Borrowers are enrolled in degree programs, and loan principal and interest payments are deferred.
- Repayment Period: Borrowers make monthly amortizing principal and interest payments, often spanning 10 to 25 years.
- Deferment and Forbearance Periods: Borrowers facing financial hardship or pursuing graduate education pause payments legally, during which interest may capitalize onto the loan balance.
Risk Factors
FFELP loans carry an explicit government guarantee covering 97% to 100% of defaulted principal and accrued interest, making their credit risk minimal. However, FFELP SLABS face significant maturity extension risk because income-driven repayment plans, extended deferments, and legislative modifications disrupt projected principal amortization timelines.
Private student loans carry no government guarantee and depend on the borrower’s (and co-signer’s) creditworthiness. Private SLABS face elevated default risks during early career entry, macro-economic wage stagnation, and changing federal debt relief policies.
Commercial Equipment Lease ABS
Commercial equipment ABS are backed by pools of leases and installment receivables collateralized by business equipment, including agricultural machinery, construction fleets, commercial aircraft, technology hardware, and medical imaging devices.
Cash Flow Mechanics and Risk Profile
Cash flows consist of fixed monthly lease payments alongside equipment residual values realized at contract maturity. Credit risk depends on commercial obligor creditworthiness and corporate default correlations across specific industrial sectors. Equipment obsolescence poses a key risk; rapid technological advancement can depress secondary market resale values for off-lease equipment, reducing SPE residual recovery cash flows.
| Non-Mortgage ABS Type | Collateral Amortization | Typical Deal Life | Key Risk Factors | Structural Early Warning / Triggers |
| Auto Loans | Amortizing monthly payments | 3 to 5 years | Prepayment speed, consumer default rates | Overcollateralization step-ups upon performance deterioration |
| Auto Leases | Amortizing payments + Residuals | 2 to 4 years | Used car auction price declines, residual shortfalls | Residual value reserve account minimum thresholds |
| Credit Card ABS | Revolving (Non-amortizing) | 3 to 7 years | Charge-off spikes, declining payment rates | Early amortization upon negative 3-month excess spread |
| FFELP Student Loans | Deferred then Amortizing | 10 to 20+ years | Maturity extension, payment deferment | Guaranteed by government; extension risk dominates |
| Private Student Loans | Deferred then Amortizing | 7 to 15 years | Unsecured credit defaults, macro unemployment | Subordination erosion, excess spread trapping |
| Equipment Leases | Amortizing + Residual proceeds | 3 to 6 years | Corporate defaults, equipment obsolescence | Cross-collateralization and residual concentration limits |
Collateralized Debt Obligations: Cash Flow Architecture and Risk Frameworks
Collateralized Debt Obligations (CDOs) are financial instruments backed by a diversified portfolio of debt obligations, such as high-yield corporate bonds, leveraged bank loans, structured finance notes, or emerging market sovereign debt. When the underlying collateral pool consists predominantly of leveraged corporate loans, the security is termed a Collateralized Loan Obligation (CLO); when collateralized by corporate bonds, it is styled a Collateralized Bond Obligation (CBO).
+-----------------------------------------------------------------------------------+
|                        CLO / CDO CASH FLOW ARCHITECTURE                           |
|                                                                                   |
|  +-----------------------------------------------------------------------------+  |
|  |                    Underlying Portfolio Collateral                          |  |
|  |     Broadly Syndicated Leveraged Corporate Loans (150-250 Issuers)          |  |
|  +-----------------------------------------------------------------------------+  |
|                                         ||                                        |
|                                         || Interest + Principal Collections       |
|                                         \/                                        |
|  +-----------------------------------------------------------------------------+  |
|  |                   Collateral Manager / SPE Trustee                          |  |
|  |    Active Reinvestment & Overcollateralization (OC) / IC Test Monitoring    |  |
|  +-----------------------------------------------------------------------------+  |
|                                         ||                                        |
|                                         || Cash Flow Waterfall Distribution       |
|                                         \/                                        |
|  +-----------------------------------------------------------------------------+  |
|  | AAA Senior Notes       (Lowest Coupon / First Claim / Max Protection)        |  |
|  | AA / A Mezzanine Notes (Intermediate Yield / Secondary Claim)              |  |
|  | BBB / BB Junior Notes  (Higher Yield / Subordinated Cash Flow Claim)          |  |
|  | Equity Tranche         (First-Loss / Unrated Residual Excess Spread Claim)  |  |
|  +-----------------------------------------------------------------------------+  |
+-----------------------------------------------------------------------------------+
Arbitrage versus Balance Sheet CDOs
CDO structures are categorized by their originating motive:
- Arbitrage CDOs: Created to capture the interest rate spread between high-yielding underlying collateral assets (such as B/BB-rated leveraged loans yielding SOFR + 450 bps) and the lower weighted average cost of capital required to service rated senior CDO notes (such as AAA notes paying SOFR + 120 bps). The collateral manager manages the portfolio actively to maximize cash distributions to the unrated equity tranche.
- Balance Sheet CDOs: Created by commercial banks to remove loans or credit risk from their balance sheets, reducing regulatory risk-weighted assets (RWA) and freeing up regulatory capital under Basel III frameworks.
Structural Tranches and Payment Waterfalls
A CDO issues multiple debt tranches alongside an equity tranche. The cash flows generated by the underlying debt portfolio are distributed according to strict senior-to-junior payment rules:
- Senior Debt Tranches (AAA/AA): Receive priority payments of interest and principal. They carry substantial subordination and benefit from mandatory coverage tests.
- Mezzanine Debt Tranches (A/BBB/BB): Offer higher coupon yields but absorb default losses once the equity tranche is exhausted.
- Subordinated / Equity Tranche: Holds no credit rating and receives no guaranteed coupon. Instead, equity holders receive all residual interest income (excess spread) after debt tranches and management fees are fully paid. The equity tranche absorbs all initial collateral default losses.
Operational Mechanics and Coverage Tests
Unlike static ABS pools, CLOs and CDOs feature an active reinvestment period (typically 3 to 5 years). During this window, the collateral manager can sell loans and reinvest principal repayments into new qualifying corporate credit facilities, subject to strict portfolio constraints (such as single-issuer limits, industry concentration caps, and weighted average rating factor requirements).
To protect senior noteholders, the SPE agreement mandates continuous compliance with two core coverage tests:
Overcollateralization (OC) Test
The OC test measures the ratio of the total principal balance of performing underlying collateral assets to the outstanding principal balance of a specific debt class and all classes senior to it.
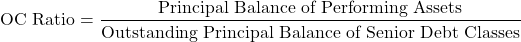
If corporate borrowers default and loan principal is written off, the OC ratio drops. If the ratio falls below the contractual trigger (e.g., 120%), the CDO cash flow waterfall alters automatically. Excess spread that would normally be paid to equity holders is diverted to buy back senior AAA notes or purchase additional eligible collateral until the OC ratio is restored to compliance.
Interest Coverage (IC) Test
The IC test measures the ratio of scheduled interest income generated by the collateral pool to the interest payment obligations of senior debt tranches.

If collateral interest collections decline due to loan defaults or corporate restructuring into non-accrual status, an IC test failure triggers cash diversion to cure the shortfall immediately, prioritizing senior note interest and principal debt reduction over junior and equity payouts.
Risk Characteristics of CDO Structures
- Default Correlation Risk: The primary structural risk in a CDO is default correlation among portfolio obligors. If underlying corporate defaults occur independently, subordination cushions absorb losses predictably. However, during systemic economic crises or sector crashes (such as broad energy or retail sector defaults), simultaneous defaults across multiple portfolio issuers can quickly erode equity and mezzanine tranches, causing losses to breach senior AAA notes.
- Manager Key-Person Risk: Because CLO performance depends on active portfolio selection, trading execution, and workout strategies for stressed assets, manager skill directly impacts investment returns.
- Market Liquidity and Valuation Risk: Underlying leveraged loans and high-yield bonds can experience severe secondary market illiquidity during market downturns. Mark-to-market declines can trigger collateral calls or forced asset liquidation in synthetic or market-value CDO structures.
| CDO Structural Feature | Arbitrage CLO | Balance Sheet CDO | Synthetic CDO |
| Primary Motivation | Capture net interest rate spread for equity holders | Remove assets / Credit risk to reduce Basel RWA | Gain tailored credit exposure using credit derivatives |
| Underlying Collateral | Broadly syndicated corporate leveraged loans | Bank loan portfolios (SME, corporate, trade finance) | Credit Default Swaps (CDS) referencing single names |
| Portfolio Management | Active management within reinvestment rules | Typically static or semi-static portfolio | Static reference portfolio defined at trade execution |
| Capital Source | Full cash funding via note issuance | Cash or synthetic risk transfer via CDS | Funded notes + Unfunded CDS protection seller tranche |
| Default Loss Trigger | Physical corporate default / Failure to pay | Actual loss realized on bank asset portfolio | Credit events under ISDA terms (Failure to pay, bankruptcy) |
Strategic Implications for Structured Finance Markets
The structured finance landscape continues to evolve under global regulatory oversight and changing economic dynamics. Regulatory frameworks—such as risk retention rules (“skin-in-the-game” requirements mandating that originators retain at least 5% of the credit risk of securitized transactions), enhanced disclosure standards under the EU Securitisation Regulation, and stringent capital treatment under Solvency II—have reinforced structural alignment between deal originators and institutional investors.
For institutional treasurers and asset managers, navigating structured debt markets requires matching structural mechanics with specific balance sheet objectives:
- Covered Bonds serve as ultra-safe, highly liquid instruments suitable for liquidity buffers, offering yield pick-up over sovereign bonds with minimal credit risk due to dual recourse protection.
- Non-Mortgage ABS provide diversified exposure to consumer and commercial credit fundamentals. Auto ABS and credit card receivables offer predictable cash flow profiles and high credit quality when protected by robust internal credit enhancements.
- Collateralized Debt Obligations (CLOs) offer attractive risk-adjusted yield premiums for investors equipped to analyze underlying corporate credit correlation, active manager capability, and structural waterfall protection mechanics.
By evaluating underlying asset cash flows, subordination structures, early warning triggers, and legal recourse boundaries, market participants can employ structured finance instruments to optimize yield, diversify risk, and manage capital efficiently across all phases of the credit cycle.
