Understanding the primary Sources of Equity Returns is vital for corporate executives, portfolio managers, and equity analysts seeking to optimize capital allocation and maximize long-term shareholder value. Equity securities generate investment returns through two core financial drivers: cash distributions paid directly to investors and capital appreciation resulting from corporate growth and market re-valuation.
While the ultimate value of an equity security reflects the net present value of its expected future cash flows, executive management teams utilize a variety of capital allocation tools—including cash dividends, stock dividends, share repurchases, forward stock splits, and reverse stock splits—to shape the precise delivery, timing, and structural presentation of these returns.
Analyzing the underlying drivers behind the Sources of Equity Returns requires evaluating both direct income channels and indirect capital adjustments. Corporate board decisions regarding payout policy directly affect shareholder yield, earnings per share (EPS) dilution or accretion, trading liquidity, and share price behavior. This comprehensive analysis examines the mechanisms, strategic rationale, corporate payment timelines, and mathematical frameworks required to quantify price return and total return across equity investments.
Overview of Equity Return Drivers
The total financial gain realized by an equity investor over a given holding period is derived from cash inflows received during the ownership period combined with the change in the market price of the asset. Financial economic theory breaks these drivers into two primary components: dividend yield and capital gains yield. Management decisions regarding capital deployment determine how earnings are split between internal reinvestment—which fuels future capital gains—and direct distributions to equity holders.
| Return Component | Primary Driver | Corporate Mechanism | Impact on Shareholder Position |
| Direct Income (Yield) | Operating cash flows and accumulated retained earnings | Cash dividends (regular or special) | Immediate liquidity; taxable event in most jurisdictions. |
| Capital Appreciation | Earnings growth, margin expansion, and valuation multiple expansion | Retained earnings reinvestment, organic expansion, mergers and acquisitions | Increases per-share market value; deferred tax until realized. |
| Indirect Wealth Distribution | Reduction in total outstanding share count | Share repurchases (buybacks) | Increases percentage ownership per share and boosts EPS. |
| Capital Restructuring | Structural changes to share denominator | Forward stock splits and reverse stock splits | Alters share count and nominal share price without changing total equity value. |
The interaction of these mechanisms governs how investors realize returns across different market environments and business lifecycle stages. Mature enterprises with steady cash flows often emphasize dividend distributions and buybacks, whereas high-growth enterprises prioritize internal reinvestment, deriving investor returns almost exclusively from capital appreciation.
Dividends: Features, Types, and Strategic Corporate Uses
Dividends represent a direct distribution of corporate assets—typically cash—to equity shareholders. Board members declare dividends as a signaling mechanism to demonstrate financial stability, operational maturity, and strong free cash flow generation.
Cash Dividends
Cash dividends are recurring or one-time payments transferred directly from a corporation’s retained earnings or operating cash flow to shareholders. They are categorized into three primary forms:
- Regular Cash Dividends: Scheduled distributions paid on a quarterly, semi-annual, or annual basis. Regular dividends provide predictable income to institutional and retail investors. Companies that consistently raise regular dividends over decades, often referred to as dividend aristocrats, attract income-oriented investors seeking inflation protection.
- Special Cash Dividends: Non-recurring payments executed when a company generates extraordinary windfall profits, completes a major asset sale, or accumulates excess cash reserves that exceed internal investment needs. Special dividends allow management to return excess capital without establishing an unsustainable benchmark for regular dividend expectations.
- Liquidating Dividends: Distributions paid when a business sells off major operating divisions or completely winds up operations. Unlike regular dividends, liquidating dividends represent a return of capital rather than a distribution of profits, reducing the company’s paid-in capital base.
A prominent real-world example of strategic dividend initiation occurred in February 2024, when Meta Platforms, Inc. declared its inaugural quarterly cash dividend of USD0.50 per share (USD2.00 annualized) alongside a USD50 billion share repurchase authorization. This move signaled Meta’s transition into a mature technology leader capable of funding aggressive artificial intelligence infrastructure while simultaneously returning substantial capital to equity investors. Similarly, established technology firms like Microsoft Corporation continue to balance ongoing cloud capital expenditure with steady annual dividend growth.
Stock Dividends
A stock dividend is a distribution of additional shares of common stock to existing shareholders rather than cash. Expressed as a percentage of existing shares (for example, a 5% or 10% stock dividend), this distribution increases the total number of shares outstanding while proportionally reducing the per-share market price.
Because stock dividends do not involve an outflow of corporate cash, the company’s total assets, total equity, and market capitalization remain unchanged. Each shareholder’s proportional ownership percentage in the enterprise stays exactly the same. Corporations utilize stock dividends to satisfy investor expectations for distributions when cash must be preserved for capital expenditures or debt service, while enhancing the market liquidity of the outstanding shares.
Share Repurchases: Strategic Rationale and Value Mechanics
A share repurchase, or stock buyback, occurs when a issuing corporation buys back its own shares from the open market or directly from shareholders, converting those equities into treasury stock or retiring them permanently. Share repurchases serve as an alternative or complementary capital return channel to cash dividends.
Total Shares Outstanding (Decreases) ---> Earnings Per Share (Increases) ---> Share Price Support
Methods of Execution
Corporations execute share repurchases through three main transactions:
- Open Market Repurchases: The most common approach, where the firm buys back shares on the open exchange at prevailing market prices over an extended period. This provides maximum flexibility, allowing management to pause or adjust buyback volumes based on market volatility and internal liquidity needs.
- Tender Offers: The company offers to buy back a fixed number of shares at a specified price—often at a premium to the current market price—within a defined timeframe. Tender offers can be structured as fixed-price offers or Dutch auctions.
- Direct Private Transactions: Repurchases negotiated directly with major institutional shareholders, frequently used to retire large blocks of stock without disrupting exchange liquidity.
Financial and Strategic Rationale
Share buybacks offer distinct financial advantages to managing capital structure and maximizing the fundamental Sources of Equity Returns:
- Earnings Per Share Accretion: By reducing the total share denominator (
 ), buybacks automatically increase Earnings Per Share (
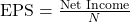 ), assuming net income remains constant.
- Tax Efficiency: In many tax jurisdictions, cash dividends are taxed immediately upon receipt as income. In contrast, share buybacks drive capital appreciation, allowing shareholders to defer capital gains tax until shares are sold.
- Signal of Undervaluation: Management often approves share repurchases when they believe the market is pricing the stock below its intrinsic value, signaling corporate confidence to the broader financial market.
- Capital Allocation Flexibility: Unlike regular cash dividends, which management is reluctant to cut due to potential negative market reactions, share repurchase programs can be scaled up or down based on economic conditions without penalizing stock sentiment.
Corporate giant Apple Inc. represents the world’s largest corporate executor of share buybacks. Over the 12-month period ending late 2025, Apple executed nearly USD97 billion in share repurchases, following a record-setting USD110 billion buyback program authorized in May 2024. By systematically reducing its total share count over the past decade, Apple has driven sustained EPS growth and capital appreciation for long-term investors. Similarly, technology firms such as Alphabet Inc. rely heavily on open-market repurchases to offset share dilution caused by employee stock-based compensation programs.
Stock Splits and Reverse Stock Splits: Restructuring Share Capital
Forward stock splits and reverse stock splits are administrative capital restructurings that alter the number of shares outstanding and the nominal per-share price without changing the total market value of the enterprise or an investor’s ownership percentage.
Forward Split: Share Count Increases  |  Per-Share Price Decreases  | Total Equity Unchanged
Reverse Split: Share Count Decreases  |  Per-Share Price Increases  | Total Equity Unchanged
Forward Stock Splits
In a forward stock split, a company increases its outstanding share count by issuing additional shares to existing holders according to a specific ratio (such as 2-for-1, 5-for-1, 10-for-1, or 50-for-1). The per-share price drops proportionally on the effective date.
- Primary Rationale: High absolute nominal share prices can limit trading accessibility for retail investors, options traders, and employees receiving equity incentives. A forward split lowers the entry price per share, improving order flow liquidity and broadening ownership.
- Real-World Corporate Examples: In June 2024, semiconductor pioneer NVIDIA Corporation executed a 10-for-1 forward stock split after its stock crossed USD1,200 per share, resetting the split-adjusted share price to approximately USD120. That same month, fast-casual restaurant leader Chipotle Mexican Grill completed a historic 50-for-1 stock split—one of the largest in New York Stock Exchange history—bringing its per-share price down from over USD3,000 to around USD60 per share to enhance stock accessibility for employees and retail investors.
Reverse Stock Splits
In a reverse stock split, a company consolidates existing shares into a smaller number of higher-priced shares according to a defined ratio (such as 1-for-5, 1-for-10, or 1-for-20).
- Primary Rationale: Reverse stock splits are primarily defensive. Major stock exchanges (such as the NYSE and Nasdaq) impose minimum bid price requirements (typically USD1.00 per share). If a company’s share price trades below this threshold for an extended period, it risks delisting. Additionally, institutional investment mandates often prohibit portfolio managers from buying stocks priced below USD5.00 per share (“penny stock” territory). A reverse split raises the nominal share price to maintain compliance and preserve institutional eligibility.
- Real-World Corporate Example: Following the 2008–2009 global financial crisis, banking conglomerate Citigroup Inc. executed a 1-for-10 reverse stock split in May 2011. The corporate action successfully elevated Citigroup’s share price from under USD4.50 to over USD45.00 per share, reducing share volatility and restoring institutional investment grade standing.
| Metric / Corporate Action | Cash Dividend | Share Repurchase | Forward Stock Split | Reverse Stock Split |
| Total Equity Value | Decreases by dividend payout amount | Decreases by repurchase cash spent | Unchanged | Unchanged |
| Shares Outstanding | Unchanged | Decreases | Increases proportionally | Decreases proportionally |
| Nominal Share Price | Adjusts downward by dividend amount on Ex-Date | Increases over time due to EPS accretion | Decreases proportionally | Increases proportionally |
| Primary Goal | Direct income distribution | Tax-efficient value return & anti-dilution | Enhance share affordability & liquidity | Prevent exchange delisting & fix penny stock status |
Dividend Payment Chronology: Key Dates and Market Pricing Effects
The administration of corporate cash dividends follows a strict chronological timeline established by contract law and stock exchange regulations. Portfolio managers and corporate financial officers must master these four key operational milestones:
Declaration Date ---> Ex-Dividend Date ---> Record Date ---> Payment Date
- Declaration Date: The date on which the board of directors formally resolves to pay a dividend. The announcement specifies the dividend amount per share, the record date, and the payment date. Upon declaration, the dividend becomes a legal liability of the corporation.
- Ex-Dividend Date (Ex-Date): The first trading day on which a buyer of the stock is not entitled to receive the declared dividend. Because stock settlement cycles take time (under standard T+1 settlement regulations), the Ex-Date is set exactly one business day before the record date. If an investor purchases shares prior to the Ex-Date, they purchase the stock cum-dividend (with dividend). If purchased on or after the Ex-Date, the stock trades ex-dividend, and the seller retains the dividend right.
- Record Date: The date set by the board to determine the official register of shareholders eligible to receive the dividend payout. Only investors logged as official owners on the company’s share register on this date will be remitted payment.
- Payment Date: The date on which the firm physically dispatches dividend funds—via electronic transfer or check—to shareholders of record or their brokerage custodians.
Market Price Adjustments on the Ex-Dividend Date
In a frictionless market without taxes or transaction costs, a company’s share price drops on the Ex-Dividend Date by an amount exactly equal to the cash dividend per share. This occurs because the firm’s cash assets decrease by the total dividend outlay, reducing fundamental net asset value per share.

Where  is the expected price drop at market open on the Ex-Date, and
 is the cash dividend per share.
In real-world markets, tax differentials between dividend income and capital gains can cause the actual price drop to differ slightly from the full nominal dividend amount. If dividend income is taxed at a higher rate than capital gains, the stock price will drop by slightly less than the full dividend amount (), reflecting the lower after-tax value of the cash dividend to the marginal investor.
Calculating Equity Returns: Price Return vs. Total Return
Accurately evaluating the Sources of Equity Returns requires distinguishing between Price Return (which measures capital gains alone) and Total Return (which accounts for both capital gains and dividend income reinvestment).
Price Return (Capital Gains Return)
Price Return ( ) measures the percentage change in the market price of an equity security over a specific holding period. It excludes all cash distributions such as dividends.
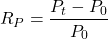
Where:
 = Initial purchase price per share at the beginning of the period.
 = Ending market price per share at time
 .
Total Return
Total Return ( ) reflects the true holistic financial productivity of an equity asset by incorporating both price appreciation and cash income received over the holding period.
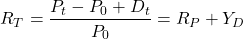
Where:
 = Total cash dividends received per share during period .
 = Dividend yield relative to initial investment price.
The Compounding Power of Dividend Reinvestment
Over multi-year investment horizons, reinvesting dividends to purchase additional fractional or full shares compounds total returns dramatically. Reinvested cash dividends generate their own future dividend streams and capital gains, serving as a primary contributor to long-term equity market performance.
Initial Capital ---> Buys Base Shares ---> Generates Cash Dividends
                          ^                               |
                          |--- Reinvests Cash Income <---|
Comprehensive Numerical Calculation Example
To illustrate these formulas, consider an institutional portfolio manager who purchases shares of an enterprise at 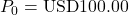 per share. Over a two-year holding period, the following price points and dividend payouts occur:
- Initial Purchase (Year 0): Share price . Initial position = 1,000 shares (Total capital invested = USD100,000.00).
- Year 1: Ending share price
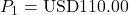 . Annual cash dividend
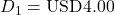 per share.
- Year 2: Ending share price
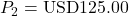 . Annual cash dividend
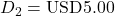 per share.
Scenario A: Calculating Returns Without Dividend Reinvestment
If cash dividends are held as uninvested cash:
- Year 1 Price Return (
 ):
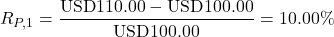
- Year 1 Total Return (
 ):
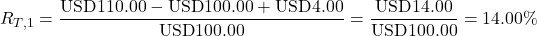
- Cumulative Two-Year Un-Reinvested Total Return:Total dividend cash collected per share over 2 years =
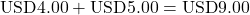 .Total ending portfolio value per share =
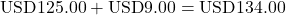 .
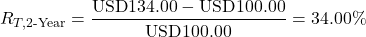
Scenario B: Calculating Returns With Full Dividend Reinvestment
If dividends are immediately reinvested into additional shares at prevailing market prices on the payment date:
- Year 1 Reinvestment:Investor receives
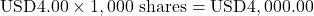 in cash dividends.Reinvested at Year 1 market price of :
Total shares held at start of Year 2 =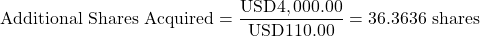
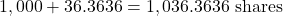 .
- Year 2 Reinvestment:In Year 2, dividend is paid on all
 shares:
Reinvested at Year 2 market price of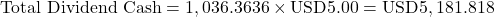 :
Total ending share count =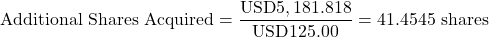
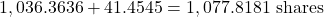 .
- Final Portfolio Valuation and Compounded Total Return:
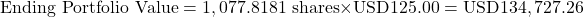
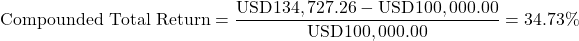
| Performance Metric | Two-Year Price Return | Two-Year Un-Reinvested Total Return | Two-Year Reinvested Total Return |
| Total Return Percentage | 25.00% | 34.00% | 34.73% |
| Ending Value of USD100,000 Portfolio | USD125,000.00 | USD134,000.00 | USD134,727.26 |
| Primary Value Source | Capital gains from share price increase | Share price increase + linear cash dividend accumulation | Share price increase + compounded share count growth |
Strategic Capital Allocation and Implications for Investors
For corporate executives and financial advisors, balancing the fundamental Sources of Equity Returns requires aligning capital deployment choices with company strategy and shareholder priorities.
                        Corporate Operating Cash Flow
                                     |
       +-----------------------------+-----------------------------+
       |                             |                             |
Internal Reinvestment         Cash Distributions             Capital Restructuring
 (R&D, M&A, Capex)          (Dividends & Buybacks)          (Forward & Reverse Splits)
       |                             |                             |
       v                             v                             v
Drives Capital Gains       Generates Current Yield        Optimizes Share Price
 (Future Growth)        & Tax-Efficient EPS Accretion    & Trading Accessibility
- Growth Stage Dynamics: Emerging enterprises should reinvest cash flows internally into high-return research, development, and market expansion. Capital appreciation serves as the primary return engine for growth investors.
- Mature Cash Flow Optimization: As organic reinvestment opportunities moderate, firms must transition toward distributing excess free cash flows through regular cash dividends and share buybacks. Combining regular dividends with opportunistic share buybacks provides an effective capital allocation framework.
- Liquidity Management: Execution of forward splits (such as NVIDIA Corporation‘s 10-for-1 split or Chipotle Mexican Grill‘s 50-for-1 split) maintains per-share affordability, ensuring broad investor access and trading liquidity. Conversely, reverse stock splits protect distressed or restructuring firms (such as Citigroup Inc.) from listing non-compliance.
Evaluating the core Sources of Equity Returns provides market participants with the analytical toolkit required to assess managerial performance, project portfolio growth, and construct resilient investment portfolios.
