Option replication using put–call parity is a fundamental financial engineering technique that allows market participants to construct synthetic derivative positions, enforce market equilibrium, and execute risk-free arbitrage when mispricings occur.
This comprehensive guide explores the mechanics, mathematical foundations, and corporate applications of both standard put–call parity and put–call forward parity for European options, providing financial leaders, portfolio managers, and investors with the analytical framework necessary to navigate modern derivative markets.
Introduction to Option Replication and Derivatives Markets
Derivative instruments form the backbone of modern risk management, enabling corporations and institutional investors to hedge against adverse market fluctuations, optimize capital structures, and enhance portfolio yields. At the heart of equity derivatives pricing lies the principle of no-arbitrage, which dictates that two portfolios with identical future payoffs under all possible scenarios must command the exact same present value. When this condition is violated, sophisticated trading desks step in to exploit the discrepancy, instantly restoring market equilibrium.
Option replication is the practical manifestation of this principle. By combining underlying assets, risk-free bonds, and derivative contracts, traders can synthetically replicate the payoff profile of any target option without necessarily trading that specific instrument directly. This capability is vital for market makers managing complex inventory books, corporate treasurers hedging foreign exchange or equity exposures, and institutional investors seeking cost-effective execution strategies. Understanding how put–call parity governs these relationships is essential for navigating today’s complex financial ecosystems, where major financial institutions such as Goldman Sachs and JPMorgan Chase continuously execute high-frequency replication and hedging strategies.
Understanding Put–Call Parity for European Options
Put–call parity is a foundational theorem in option pricing that establishes a strict mathematical relationship between the price of a European call option and a European put option sharing the exact same underlying asset, strike price, and expiration date. Unlike American options, which can be exercised prematurely, European options can only be exercised at maturity. This unique constraint eliminates early exercise premiums and allows for a clean, deterministic pricing link.
To grasp the intuition behind put–call parity, consider two distinct portfolios constructed with identical expiration horizons. Portfolio A consists of a European call option and a zero-coupon bond with a face value equal to the strike price maturing at option expiration. Portfolio B consists of a European put option and one share of the underlying stock. At maturity, regardless of whether the stock price finishes above or below the strike price, both portfolios deliver identical terminal cash flows. Consequently, their initial costs must be equal to prevent risk-free arbitrage.
The Core Mechanics of Synthetic Positions
The principle of replication allows traders to create synthetic instruments that mimic the exact risk and return profile of target securities. Through put–call parity, market participants can decompose or reconstruct positions in four primary ways:
| Portfolio Component | Long Call Position | Long Put Position | Synthetic Long Stock | Synthetic Short Stock |
| Underlying Stock | Not Held | Long 1 Share | Long 1 Share | Short 1 Share |
| Call Option | Long 1 Contract | Not Held | Long 1 Contract | Short 1 Contract |
| Put Option | Short 1 Contract | Long 1 Contract | Short 1 Contract | Long 1 Contract |
| Risk-Free Bond | Short Bond (Borrow) | Long Bond (Lend) | Long Bond (Lend) | Short Bond (Borrow) |
These synthetic relationships empower institutional desks to manage liquidity constraints. For instance, if liquidity dries up in the listed put option market, a trader can easily construct a synthetic put by buying a call, shorting the underlying stock, and lending the present value of the strike price.
Mathematical Foundations and Proof of Put–Call Parity
To formalize the relationship, let us define the key variables governing European options:


Consider two portfolios at time 

- Portfolio A: One European call option plus a zero-coupon bond that pays the strike price

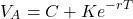
- Portfolio B: One European put option plus one share of the underlying stock. Therefore, the initial value of Portfolio B is:


Examining Terminal Payoffs at Expiration
At time 

Scenario One: The terminal stock price exceeds the strike price (

- The call option is exercised, yielding

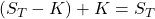
- The put option expires worthless (


Scenario Two: The terminal stock price is less than or equal to the strike price (
- The call option expires worthless (

- The put option is exercised, yielding

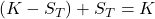

Because the terminal payoffs of Portfolio A and Portfolio B are identical (
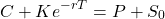

Rearranging this equation allows traders to price any of the four components if the remaining three are known in the marketplace.
Synthetic Positions and Arbitrage Opportunities in Corporate Risk Management
When market inefficiencies occur, put–call parity violations create immediate arbitrage opportunities. Arbitrageurs do not need to take directional bets on the underlying asset; instead, they lock in risk-free profits by exploiting temporary mispricings between options and the underlying stock.
Types of Arbitrage Strategies
When the put–call parity equation 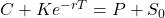

- Cash and Carry Arbitrage (Undervalued Call / Overvalued Put): If the left side of the equation is significantly lower than the right side (
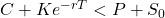
- Reverse Cash and Carry Arbitrage (Overvalued Call / Undervalued Put): If the left side exceeds the right side (
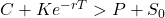
Global financial institutions and proprietary trading firms utilize automated algorithms to monitor these relationships across major exchanges, ensuring that arbitrage windows remain exceptionally narrow. Corporations engaged in large-scale equity repurchases or hedging programs must also account for these pricing boundaries to execute transactions efficiently.
Extending the Framework to Put–Call Forward Parity
While standard put–call parity relies on the spot price of the underlying asset, many financial markets—such as commodities, currencies, and fixed income—rely heavily on forward and futures contracts. To accommodate these markets, financial theorists extend the framework into put–call forward parity.
Put–call forward parity replaces the spot price 


Substituting this into our standard put–call parity equation yields the forward parity form. Alternatively, consider a portfolio consisting of a European call and put with identical strike prices
The put–call forward parity equation is expressed as:
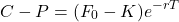

This elegant relationship states that the difference between the price of a European call and a European put is equal to the present value of the difference between the forward price and the strike price.
Advantages of Forward Parity in Commodity and Currency Markets
In markets where carrying costs—such as storage costs for commodities or interest rate differentials for foreign currencies—play a dominant role, forward parity provides distinct operational advantages over spot-based parity:
- Elimination of Immediate Funding Friction: Traders do not need to borrow cash or purchase physical spot assets immediately, reducing repo market friction.
- Cleaner Hedging for Forward Commitments: Multinational corporations managing foreign exchange exposures often deal in forward contracts rather than immediate spot conversions. Forward parity aligns option pricing directly with existing forward book commitments.
Practical Application and Corporate Case Studies
To illustrate how option replication and put–call parity operate in real-world corporate finance, consider major global enterprises managing complex balance sheet risks. While high-tech leaders like Apple primarily manage cash and currency risks through conventional hedging, capital-intensive firms and financial institutions actively deploy synthetic option replication to hedge equity exposures and derivative portfolios.
Corporate Hedging Case Study
Imagine a multinational conglomerate holding a large block of equity shares in a subsidiary valued at USD1,000,000,000. Management wishes to protect against a potential market downturn over the next twelve months without incurring the massive upfront premium required to purchase outright put options.
By applying put–call parity, the corporate treasury department can execute a “collar” or synthetic put strategy:
- They purchase out-of-the-money European put options to establish a downside price floor.
- To fund the purchase of these puts, they simultaneously sell out-of-the-money European call options, creating a zero-cost or low-cost collar.
- If market volatility causes discrepancies between the implied volatility of the calls and puts, treasury desks utilize put–call forward parity to verify whether synthetic replication via forward contracts offers a more cost-effective execution path than trading the options outright.
Through precise mathematical replication, the corporation achieves the exact risk-mitigation objective while optimizing capital allocation and minimizing unnecessary interest expense.
Conclusion and Strategic Implications for Financial Leaders
Option replication using put–call parity is far more than a theoretical academic exercise; it is an indispensable operational tool for modern financial management. By establishing unbreakable mathematical bridges between puts, calls, underlying assets, and risk-free bonds, put–call parity ensures market integrity and unlocks sophisticated synthetic trading strategies.
For corporate executives, treasurers, and institutional investors, mastering both standard put–call parity and put–call forward parity enables superior risk management, cost reduction in hedging mandates, and the ability to capitalize on market inefficiencies. As global derivatives markets continue to evolve in complexity and speed, a rigorous grounding in option replication remains a critical core competency for financial leadership.

