Welcome to the definitive resource on the Pricing and Valuation of Interest Rate and Other Swaps. In the complex architecture of modern global financial markets, derivative instruments play an indispensable role in hedging risk, managing liquidity, and optimizing capital structure.
Among these, interest rate swaps, currency swaps, and commodity swaps dominate over-the-counter (OTC) trading volumes.
For corporate treasurers, investment bankers, financial analysts, and institutional investors, understanding how these agreements are priced at inception and valued over their lifecycle is critical.
This comprehensive guide explores the structural mechanics of swaps, examines their theoretical connection to a series of forward contracts, and clearly contrasts the concepts of swap price and swap value using professional financial principles and real-world corporate examples.
Understanding Swaps and Their Role in Global Finance
A swap is a customized derivative contract through which two counterparties agree to exchange cash flows based on a specific notional principal amount over a predetermined period. While plain vanilla interest rate swaps involve exchanging fixed-rate interest payments for floating-rate interest payments, other variations include cross-currency swaps, commodity swaps, and total return equity swaps. Multinational corporations, such as Microsoft Corporation and Apple Inc., routinely utilize these instruments to convert floating-rate debt obligations into fixed-rate liabilities or to hedge against foreign exchange volatility across international jurisdictions.
To master derivative analytics, financial professionals must distinguish between setting up a contract and evaluating its ongoing market worth. The foundational mechanics begin by examining how swap agreements relate to simpler forward contracts.
Similarities Between Swap Contracts and a Series of Forward Contracts
At their core, swaps can be conceptualized and mathematically decomposed as a portfolio of individual forward contracts. This fundamental equivalence bridges linear derivatives and multi-period swap agreements.
The Cash Flow Exchange Mechanism
Both a forward contract and a swap involve bilateral commitments to exchange cash flows at future specified dates based on underlying market variables, such as interest rates or foreign exchange rates. In a single-period forward rate agreement (FRA), party A agrees to pay a fixed rate and receive a floating rate on a future settlement date. A multi-period interest rate swap is essentially a strip of individual forward rate agreements maturing at each subsequent coupon payment date.
Market Risk Exposure
Both instruments expose counterparties to market risk driven by fluctuations in benchmark rates, such as the Secured Overnight Financing Rate (SOFR) or the Euro Interbank Offered Rate (Euribor). As benchmark interest rates shift, the intrinsic value of both a forward contract and an individual future settlement date within a swap contract fluctuates accordingly. Furthermore, both instruments are typically traded over-the-counter, exposing participants to counterparty credit risk, which necessitates robust credit support annexes and collateral management practices managed by major financial institutions like JPMorgan Chase and Citigroup.
Key Differences Between Swaps and Forward Contract Strips
Despite their structural similarities, significant institutional and mechanical differences separate a continuous swap contract from an independent sequence of forward contracts.
Contractual Execution and Liquidity
A forward contract is a single, discrete agreement settled on one specific future date. Conversely, an interest rate swap is executed as a single overarching master agreement (typically governed by International Swaps and Derivatives Association documentation) that binds multiple future cash flow exchanges into one unified legal and financial instrument. This single-contract wrapper significantly reduces legal friction, transaction overhead, and settlement complexity compared to executing a rolling series of independent forward contracts.
Credit Risk and Netting Efficiencies
In a strip of forward contracts, cash flows are settled independently across different dates without bilateral netting across the entire maturity spectrum unless specifically structured under a master netting agreement. A swap contract inherently embeds multi-period cash flow netting, where fixed and floating obligations on identical payment dates are netted into a single net settlement amount. This dramatically lowers the gross credit exposure and potential future exposure for corporations and banking partners like Bank of America.
Flexibility and Embedded Optionality
Swaps frequently incorporate embedded structures, such as amortizing notional balances, accreting schedules, or cancellable options (swaptions), which are far more complex to bundle cleanly into a standard sequence of discrete forward contracts.
| Feature | Forward Contract Strip | Interest Rate Swap |
| Legal Structure | Multiple distinct bilateral agreements | Single unified master contract |
| Cash Flow Settlement | Settled independently per maturity date | Net payment calculated per payment date |
| Credit Exposure | Higher gross exposure across maturities | Lower net exposure via bilateral cash netting |
| Customization | Tailored per settlement date | Integrated across an entire yield curve |
The Core Distinction: Price Versus Value in Swaps
One of the most common conceptual hurdles in fixed-income analytics is differentiating between the price of a swap and the value of a swap. In introductory finance, price and value are often used interchangeably, but in derivative pricing theory, they represent entirely different economic realities.
Defining Swap Price
The price of a swap refers to the specific terms—most notably the fixed interest rate (the swap rate)—agreed upon at the inception of the contract that sets the initial net present value of the agreement to zero. When a corporate treasury executes a standard five-year interest rate swap, the fixed rate determined by the dealing desk (e.g., 4.25 percent) is the swap price. At inception, neither party pays a premium to enter the contract because the present value of the fixed-rate leg exactly equals the present value of the expected floating-rate leg.
Defining Swap Value
The value of a swap represents the mark-to-market net present value (NPV) of the remaining cash flows of the contract at any point during its active lifecycle. While a newly executed swap always has a value of zero, market interest rates evolve continuously after inception. Consequently, the value of the swap fluctuates above or below zero for each counterparty. If benchmark interest rates rise significantly after a fixed-rate payer enters a contract, the fixed-rate obligation becomes favorable in a higher-rate environment, giving that position a positive market value.
Pricing Interest Rate and Other Swaps
Pricing a swap involves determining the fixed rate (or spread) such that the contract initiates with a net present value of zero. This pricing methodology relies heavily on no-arbitrage principles and yield curve construction.
The Par Swap Rate Formula
For a standard vanilla interest rate swap, the fixed swap rate (

Therefore, the fixed swap rate is determined by the equation:
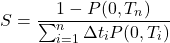

Where:


Global corporations and institutional dealers utilize sophisticated quantitative pricing engines to bootstrap discount curves from money market instruments, futures, and overnight index swap (OIS) rates to derive these exact pricing inputs.
Valuation Mechanics of Interest Rate and Currency Swaps
Once a swap is active, ongoing valuation requires discounting all future projected cash flows back to the current valuation date using up-to-date discount factors.
Valuing Interest Rate Swaps
The mark-to-market value (

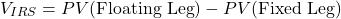

- Floating Leg Valuation: The expected future floating cash flows are projected using forward rates implied by the current yield curve, and then discounted back to the present using the corresponding discount factors.
- Fixed Leg Valuation: The fixed cash flows (determined by the original swap price) are known with certainty and are discounted back using the current discount curve.
Valuing Cross-Currency Swaps
Cross-currency swaps involve exchanging principal and interest payments in two different currencies. Valuation requires projecting and discounting cash flows in each respective currency stream using currency-specific yield curves, and then converting the net present value into a common reporting currency using the prevailing spot exchange rate. Major multinational conglomerates, such as Toyota Motor Corporation and Nestlé, rely heavily on cross-currency swap valuations to manage international debt portfolios denominated in USD, EUR, and JPY.
Real-World Business Applications and Corporate Examples
To contextualize theoretical pricing and valuation, examining how global enterprises manage interest rate and currency risk in practice is illuminating.
Corporate Debt Restructuring at Siemens
Consider Siemens AG, a global industrial manufacturing leader. When Siemens issues long-term bonds in international capital markets, market conditions might favor fixed-rate debt issuance, but corporate policy might target a floating-rate liability structure to match incoming floating-rate revenues. Siemens enters into a receive-fixed, pay-floating interest rate swap. At inception, the swap price is established at the prevailing par swap rate, ensuring a zero net present value. Over subsequent quarters, as European Central Bank and Federal Reserve interest rates shift, the valuation of this swap fluctuates. If interest rates drop, the swap carries a negative mark-to-market value for Siemens on its financial statements, requiring regular fair value accounting adjustments under International Financial Reporting Standards (IFRS) or US GAAP.
Currency Risk Mitigation at Unilever
Multinational consumer goods giant Unilever generates revenues and incurs expenses across dozens of emerging and developed markets. To insulate balance sheets from foreign exchange shocks, Unilever executes cross-currency interest rate swaps. These agreements lock in favorable exchange rates for future principal redemptions while swapping high-yield local currency interest obligations into stable USD or EUR liabilities. Regular valuation of these swaps ensures accurate treasury reporting and efficient collateral postings with counterparty investment banks.
Conclusion
Mastering the Pricing and Valuation of Interest Rate and Other Swaps is essential for financial professionals navigating modern capital markets. While swaps share structural and risk similarities with a strip of forward rate agreements, their unified legal framework, multilateral cash flow netting, and operational flexibility set them apart. Crucially, distinguishing between the initial swap price—which anchors the contract at a net present value of zero—and the ongoing swap value, which fluctuates dynamically with shifting yield curves and exchange rates, underpins sound corporate treasury management. By applying rigorous quantitative models and adhering to no-arbitrage valuation principles, institutions and corporations can effectively harness derivatives to mitigate financial risk and optimize global capital structures.

