Curve-Based and Empirical Fixed-Income Risk Measures provide institutional investors, portfolio managers, and corporate treasurers with the analytical tools necessary to navigate complex interest rate environments, evaluate structural cash flow optionality, and protect capital against yield curve volatility.
Introduction to Curve-Based and Empirical Fixed-Income Risk Measures
In contemporary global financial markets, managing interest rate risk requires analytical sophistication that extends far beyond traditional bond mathematics. Fixed-income securities represent a cornerstone of corporate finance, sovereign debt management, and institutional asset allocation. However, standard risk metrics such as Macaulay duration and modified duration often prove inadequate when confronted with complex securities, embedded options, and non-parallel yield curve shifts.
Curve-Based and Empirical Fixed-Income Risk Measures bridge this analytical gap. By incorporating rigorous pricing models, scenario-based rate shifts, key rate sensitivities, and historical statistical regressions, financial professionals can accurately quantify price volatility. This comprehensive examination explores why effective duration and effective convexity are vital for options-embedded bonds, details percentage price change calculations, defines key rate duration, and contrasts analytical duration with empirical duration.
Understanding Interest Rate Risk in Bonds with Embedded Options
Bonds featuring embedded options—such as callable corporate bonds, puttable bonds, and mortgage-backed securities—exhibit cash flows that change contingent upon prevailing market interest rates. Traditional analytical duration measures fail when applied to these instruments because they assume that cash flows are fixed and independent of yield changes.
When interest rates drop significantly, a callable bond issued by a corporation like Ford Motor Company (https://www.ford.com) or Microsoft Corporation (https://www.microsoft.com) faces a high probability of being called by the issuer seeking to refinance high-coupon debt at lower market rates. Consequently, its price appreciation is constrained, resulting in negative convexity. Traditional duration calculations assume linear price behavior that does not account for this cash flow re-routing.
Similarly, puttable bonds grant the investor the right to sell the bond back to the issuer at a predetermined price prior to maturity. When interest rates rise, the price of a standard fixed-rate bond drops sharply. However, a puttable bond’s price is cushioned because the investor can exercise the put option to recover par value. Because these optional features alter the expected life and cash flow profile of the bond, standard modified duration calculations overestimate price drops in falling rate environments for callable bonds and underestimate price resilience for puttable bonds. Therefore, specialized curve-based measures are required.
Effective Duration and Effective Convexity Mechanics
Effective duration and effective convexity measure price sensitivity by evaluating how a bond’s price changes when the benchmark yield curve shifts uniformly up and down. Unlike modified duration, which requires a derivative of price with respect to yield assuming fixed cash flows, effective duration uses matrix pricing or binomial tree pricing models to re-evaluate the bond’s price under parallel yield shifts.
The mathematical formulation for effective duration is expressed as:
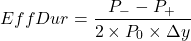

Where:


Similarly, effective convexity captures the curvature of the price-yield relationship, accounting for the acceleration of price changes when yields move:
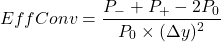

For callable bonds, effective convexity is often negative at lower yields because price gains are capped by the call price, whereas for puttable bonds or standard bullet bonds, convexity is positive. Negative convexity introduces severe reinvestment and price risk for portfolio managers, making effective convexity an indispensable metric for risk governance.
Calculating Bond Percentage Price Changes Using Duration and Convexity
To demonstrate how portfolio managers at institutions like JPMorgan Chase (https://www.jpmorganchase.com) evaluate risk, let us calculate the percentage price change of a corporate bond given its effective duration and effective convexity.
Suppose a corporate bond has the following characteristics:
- Initial Price (
- Effective Duration: 6.5 years
- Effective Convexity: 45.0
- Benchmark yield change (
Using the second-order Taylor series expansion, the percentage price change approximation is:
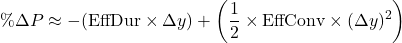

Let us calculate each component step-by-step:
- Linear duration effect:
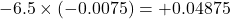

- Convexity adjustment effect:
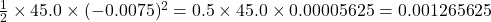


Total estimated percentage price change:
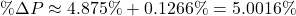

The new estimated bond price is:
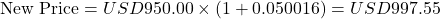

The following table summarizes the valuation inputs and calculated price impact:
| Valuation Parameter | Input Value / Result |
| Initial Bond Price | USD950.00 |
| Effective Duration | 6.50 Years |
| Effective Convexity | 45.00 |
| Yield Change | -0.75% (-75 Basis Points) |
| Duration Price Effect | +4.8750% |
| Convexity Price Effect | +0.1266% |
| Total Percentage Price Change | +5.0016% |
| Estimated New Bond Price | USD997.55 |
Key Rate Duration and Yield Curve Shift Sensitivity
While effective duration assumes parallel shifts in the yield curve, real-world yield curves frequently experience non-parallel shifts—steepening, flattening, or humping. To measure price sensitivity to specific segments of the yield curve, fixed-income analysts utilize key rate duration (also known as partial duration).
Key rate duration measures the percentage price change of a security in response to a small, isolated shift in the yield at a specific maturity point on the benchmark yield curve, keeping all other maturity rates constant. For example, global industrial conglomerates like Toyota Motor Corporation (https://global.toyota) manage extensive debt portfolios spanning various maturities across international capital markets. By analyzing key rate durations across the 2-year, 5-year, 10-year, and 30-year benchmark points, corporate treasurers and risk managers can construct immunized portfolios that withstand twists and curvature changes in the yield curve, rather than relying solely on parallel shift assumptions.
If a bond portfolio has high key rate duration at the 10-year maturity vertex, it is particularly vulnerable to a bear steepening where 10-year yields rise faster than short-term yields. Key rate duration allows portfolio managers to pinpoint structural vulnerabilities and hedge specific maturity exposures using interest rate swaps or targeted Treasury futures.
Empirical Duration Versus Analytical Duration
Analytical duration (such as modified duration or effective duration) is a theoretical measure derived mathematically from bond cash flows, pricing models, and yield formulas. In contrast, empirical duration (also known as historical or regression duration) is calculated statistically by regressing historical percentage price changes of a bond or portfolio against historical changes in benchmark market yields over a specific lookback period.
Understanding the distinction between these two methodologies is critical for risk managers seeking to reconcile theoretical model outputs with observed market behavior.
| Dimension | Analytical Duration | Empirical Duration |
| Calculation Method | Mathematical derivative or pricing model valuation under shifted yields | Statistical linear regression of historical price returns against yield changes |
| Data Source | Theoretical cash flows, coupon schedules, and pricing models | Actual market prices, historical trades, and observed yield data |
| Market Friction Sensitivity | Assumes frictionless markets and instantaneous repricing | Captures real-world market imperfections, liquidity constraints, and trading lags |
| Primary Application | Portfolio construction, theoretical immunization, and structured bond pricing | Macro risk monitoring, historical backtesting, and empirical stress testing |
Empirical duration often diverges from analytical duration during periods of market stress, liquidity crunches, or credit spread widening. For instance, during systemic liquidity shocks, lower-rated corporate bonds may experience price drops driven by credit contagion rather than risk-free rate movements, leading to empirical durations that differ substantially from their analytical counterparts.
Real-World Corporate Applications and Risk Management
Financial institutions, asset managers, and corporate treasuries integrate curve-based and empirical risk measures into daily risk governance frameworks. Value-at-Risk (VaR) models and stress-testing protocols rely heavily on key rate durations and effective convexity to simulate extreme macroeconomic scenarios.
Furthermore, comparing analytical duration with empirical duration allows risk oversight committees to identify liquidity premiums, model misalignments, and structural hedging errors in fixed-income portfolios. By utilizing these advanced metrics, organizations ensure that their hedging strategies remain robust against both parallel benchmark shifts and complex yield curve deformations.
Conclusion
Curve-Based and Empirical Fixed-Income Risk Measures are indispensable for modern financial management. By moving beyond traditional Macaulay duration to embrace effective duration, effective convexity, key rate duration, and empirical duration, market participants can accurately gauge interest rate risk, navigate embedded option complexities, and ensure robust portfolio resilience across shifting economic landscapes.

