The valuation of fixed-income instruments forms the cornerstone of modern debt capital markets. Understanding how bond prices and yields interact, how cash flows are calculated between settlement dates, and how non-liquid bonds are priced using matrix pricing provides investors, corporate CFOs, and portfolio managers with the necessary tools to navigate global debt markets.
Executive Summary
Fixed-income valuation rests on the principle that a bond’s price equals the present value of its future cash flows, discounted at an appropriate yield-to-maturity (YTM). This analysis examines the mechanism for pricing bonds on and between coupon payment dates, details the fundamental structural relationships governing price-yield dynamics, and explores matrix pricing as a primary valuation technique for illiquid fixed-income issues.
1. Calculating a Bond’s Price Given a Yield-to-Maturity
Evaluating a bond requires discounting expected cash flows—periodic coupon payments and the principal return at maturity—to the settlement date.
Bond Pricing on Coupon Payment Dates
When a settlement date falls exactly on a coupon payment date, the bond price calculation uses discrete discounting periods. The price of a flat-coupon bond is derived using the standard present value equation:
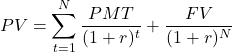

Where:


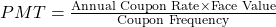


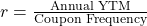


Corporate Valuation Example: Apple Inc. Bond
Consider a hypothetical corporate bond issued by Apple Inc. with a face value of USD1,000, paying a 5.00% annual coupon semiannually, maturing in exactly 5 years. Assuming an annual yield-to-maturity of 4.00%:
| Parameter | Value |
| Face Value ( | USD1,000 |
| Annual Coupon Rate | 5.00% |
| Coupon Frequency | Semiannual ( |
| Periodic Coupon ( | USD25.00 |
| Years to Maturity | 5 years |
| Total Periods ( | 10 periods |
| Annual Yield-to-Maturity (YTM) | 4.00% |
| Periodic Discount Rate ( | 2.00% |

Calculating the Present Value:
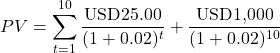

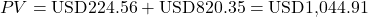

Because the annual coupon rate (5.00%) exceeds the YTM (4.00%), the bond trades at a premium over par value.
Bond Pricing Between Coupon Dates
When settlement occurs between coupon dates, cash flows must account for fractional periods and accrued interest.
       Last Coupon Date             Settlement Date            Next Coupon Date
--------------|----------------------------|--------------------------|
              <----- Accrued Days (t) ----->
              <------------------ Total Days (T) --------------------->
Full Price vs. Clean Price
- Full Price (Dirty Price): The total cash consideration paid by the buyer to the seller on the settlement date, representing the total present value of future cash flows.
- Accrued Interest: The portion of the upcoming coupon payment earned by the seller for holding the bond from the last coupon date to the settlement date.
- Clean Price (Flat Price): The quoted price of the bond, equal to the full price minus accrued interest. Quoting clean prices prevents artificial price jump discontinuities on coupon payment dates.
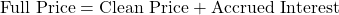

Fractional Period Formula
Let 


The full price on fractional settlement date 

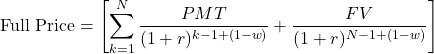

Alternatively, compound the full price from the most recent coupon date (

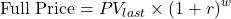

Accrued interest is computed on a linear basis using the specific day-count convention:
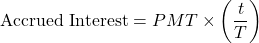

Day-Count Conventions
Different fixed-income sectors utilize distinct standards to calculate
| Market Sector | Day-Count Convention | Description |
| Government Bonds | Actual/Actual (ICMA) | Uses actual calendar days between dates and actual days in the period. |
| Corporate Bonds | 30/360 (Bond Basis) | Assumes twelve 30-day months and a 360-day year. |
| Money Market Instruments | Actual/360 or Actual/365 | Uses actual days elapsed divided by a 360-day or 365-day year. |
2. Structural Relationships: Price, Coupon, Maturity, and YTM
Bond valuation exhibits inverse and convex dynamic relationships across yields, maturities, and coupon rates.
Bond Price
    ^
    |      / Premium (Coupon Rate > YTM)
    |     /
--- Par -/----------------------------- (Coupon Rate = YTM)
    |   /
    |  / Discount (Coupon Rate < YTM)
    +----------------------------------> Yield-to-Maturity (YTM)
The Inverse Price-Yield Relationship
A fundamental property of fixed-income instruments is that bond prices move inversely to yield-to-maturity. As market interest rates rise, the present value of fixed future cash flows declines, lowering the bond’s market price.
       Price Increases
            ^
            |
  Yield <---+---> Yield
  Falls     |     Rises
            v
       Price Decreases
Premium, Par, and Discount Relationships
The relationship between coupon rate, current yield, and YTM determines whether a bond trades at a premium, at par, or at a discount:
| Bond Trading Status | Condition | Price Relationship |
| Premium Bond | Coupon Rate > YTM | Full Price > Par Value |
| Par Bond | Coupon Rate = YTM | Full Price = Par Value |
| Discount Bond | Coupon Rate < YTM | Full Price < Par Value |
The Convexity Property
The price-yield relationship is non-linear; it is convex toward the origin. As a result:
- For a given basis point drop in YTM, the percentage price increase is greater than the percentage price decrease resulting from an equivalent basis point rise in YTM.
- Capital gains from falling interest rates exceed capital losses from rising interest rates of identical magnitude.
Price Change (+)  ▲     / (Price gain for yield drop)
                  |    /
                  |   /
                  |  /
          0 ------+-------------------- Yield Change
                  | \
                  |  \  (Price loss for yield rise)
Price Change (-)  ▼   \
Maturity Effects on Price Sensitivity
Holding the coupon rate constant, longer-maturity bonds display greater price sensitivity to interest rate changes than shorter-maturity bonds.
- Maturity Effect: A 30-year bond experiences a larger percentage price swing for a 100-bps change in YTM than a 5-year bond.
- Diminishing Marginal Sensitivity: While price sensitivity increases with maturity, it increases at a decreasing rate.
Coupon Effects on Price Sensitivity
Holding maturity constant, lower-coupon bonds exhibit higher percentage price sensitivity to changes in YTM than higher-coupon bonds.
- Coupon Effect: Zero-coupon bonds exhibit the maximum percentage price volatility for a given shift in yield-to-maturity because all cash flow is concentrated at maturity.
- Higher coupon payments offer earlier cash inflows, shortening the weighted average time to payment arrival (Macaulay Duration) and insulating the bond’s total value from yield fluctuations.
3. Matrix Pricing
Many corporate, municipal, and private-placement fixed-income issues trade infrequently in secondary markets. Matrix pricing provides an estimation methodology to value unquoted or illiquid bonds using market yields from liquid benchmark securities with comparable credit risk and maturity characteristics.
[Target Illiquid Bond] <--- Interpolate Yield ---> [Liquid Benchmark Bonds]
                                                            |
                                                            v
                                                   Adjust for Credit Spread
                                                            |
                                                            v
                                                  Estimated Target Yield
                                                            |
                                                            v
                                                  Discount Cash Flows
                                                            |
                                                            v
                                                  Estimated Fair Price
The Matrix Pricing Methodology
- Identify Comparable Benchmarks: Select liquid bonds issued by companies with identical or similar credit ratings and comparable capital structures.
- Determine Interpolated Yields: Use linear interpolation across benchmark maturities to establish a base yield corresponding to the target bond’s exact term to maturity.
- Incorporate Credit Spreads: Add credit risk spreads (or benchmark yield spreads) associated with the specific credit rating class over government benchmark yields (e.g., U.S. Treasury yields).
- Discount Target Cash Flows: Calculate the estimated price of the target bond by discounting its cash flows at the interpolated yield-to-maturity derived from the matrix.
Matrix Pricing Example: Evaluating an Illiquid Corporate Bond
A corporate finance analyst needs to estimate the fair market value of an illiquid 6-year bond issued by a private manufacturing enterprise rated BBB. Liquid corporate issues from peers like Microsoft Corporation or similar entities are monitored across 3-year, 5-year, and 10-year maturities:
| Benchmark Issue | Credit Rating | Maturity | Quoted Yield-to-Maturity (YTM) |
| Corporate Peer A | BBB | 5.0 Years | 4.50% |
| Corporate Peer B | BBB | 10.0 Years | 5.50% |
Step 1: Linear Interpolation for a 6-Year Yield
Using linear interpolation between the 5-year and 10-year benchmark yields to find the estimated YTM for a 6-year maturity:
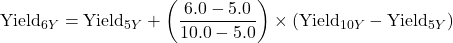

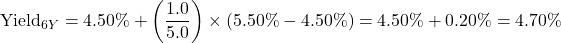

Step 2: Pricing the Target Bond
Assuming the target illiquid bond pays an annual coupon of 5.25%, has a face value of USD1,000, and matures in 6 years:
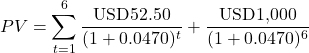

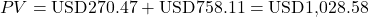

The matrix pricing model provides an estimated fair value of USD1,028.58 for the illiquid 6-year bond.
Applications of Matrix Pricing
- Underwriting New Debt Issues: Investment banks use matrix pricing to establish appropriate yield spreads and initial offer prices for corporate bonds entering primary markets.
- Portfolio Marking-to-Market: Asset management institutions and mutual funds use matrix pricing algorithms to value illiquid fixed-income holdings for daily Net Asset Value (NAV) reporting.
- Yield Spread Analysis: Fixed-income strategists isolate specific risk premiums (such as liquidity, term, or credit spreads) across market segments by comparing matrix pricing yields against benchmark yield curves.
Comparative Overview of Fixed-Income Valuation Concepts
| Valuation Concept | Primary Focus | Key Inputs | Practical Application |
| Full Price Calculation | Settlement value on or between coupon dates | Coupon rate, YTM, settlement date, day-count convention | Executing actual market trades and portfolio accounting |
| Price-Yield Sensitivities | Risk assessment and duration metrics | Maturity, coupon rate, YTM level | Portfolio risk management, interest rate hedging |
| Matrix Pricing | Fair value estimation for illiquid assets | Peer bond yields, credit spreads, benchmark yield curves | NAV calculations, new issue pricing, mark-to-market valuation |

