Credit risk remains one of the most critical challenges facing contemporary financial markets, influencing everything from corporate borrowing costs to global macroeconomic stability.
This comprehensive guide explores credit risk and its core components, the functions and limitations of credit rating agencies, and the complex macroeconomic, market, and issuer-specific factors driving yield spread dynamics for global institutions like JPMorgan Chase and Ford Motor Company.
Understanding Credit Risk Fundamentals
At its core, credit risk is the financial loss incurred if a borrower or counterparty fails to meet its obligations in accordance with agreed-upon terms.
Whether dealing with corporate bonds, sovereign debt, syndicated loans, or over-the-counter derivatives, market participants must constantly evaluate and price credit risk to ensure adequate capital reserves and sustainable profitability. In modern corporate finance, managing credit risk effectively allows financial institutions to allocate capital efficiently, support productive enterprise expansion, and insulate the broader financial system against systemic contagion.
For Chief Executive Officers, chief risk officers, and institutional investors, understanding the anatomy of credit risk is essential for strategic decision-making. When a firm extends credit or purchases fixed-income securities, it essentially sells an implicit insurance policy against default. The compensation for taking on this risk is the credit spread—the yield premium offered over risk-free benchmark rates, such as United States Treasury securities. Evaluating this spread requires a granular understanding of the underlying building blocks that constitute total expected credit losses.
Deconstructing Credit Risk Components
To quantify and manage credit risk accurately, financial institutions and regulatory frameworks rely on three fundamental components: Probability of Default, Loss Given Default, and Exposure at Default. Together, these variables form the bedrock of modern credit risk modeling, including internal ratings-based approaches under international banking frameworks.
A. Probability of Default
The Probability of Default represents the likelihood that a borrower will default on its financial obligations over a specific time horizon, typically one year or the lifetime of the loan. Estimating the Probability of Default involves analyzing historical default frequencies, macroeconomic projections, and borrower-specific financial ratios. For instance, a mature, cash-generative technology giant like Apple exhibits an extremely low Probability of Default, whereas a cyclical manufacturing firm experiencing severe liquidity pressure might carry a significantly elevated Probability of Default.
Quantitative models used to estimate the Probability of Default generally fall into three categories:
- Statistical scoring models, such as logistic regression and credit scoring matrices used in retail and small-business lending.
- Reduced-form models, which treat default as an unpredictable event driven by external market and macroeconomic variables.
- Structural models, pioneered by Robert Merton, which view default as an endogenous event occurring when the market value of a firm’s assets falls below the face value of its liabilities.
B. Loss Given Default
Loss Given Default measures the economic loss suffered by a lender if the borrower actually defaults, expressed as a percentage of the total exposure at the time of default. Loss Given Default is fundamentally determined by the recovery rate, calculated simply as one minus the recovery rate. If a corporate bond defaults and investors recover USD40 cents on the dollar through bankruptcy reorganization or asset liquidation, the Loss Given Default is sixty percent.
Several factors heavily influence Loss Given Default:
- Seniority of the claim in the corporate capital structure, where senior secured debt holders enjoy priority over unsecured bondholders and equity holders.
- Collateral quality and legal enforceability, including real estate, equipment, or accounts receivable pledged to secure the credit facility.
- Jurisdiction and efficiency of local bankruptcy laws, which dictate the duration and cost of debt restructuring processes.
C. Exposure at Default
Exposure at Default represents the total gross financial amount outstanding when the borrower defaults. For term loans and fixed-rate bonds, the Exposure at Default is straightforward, corresponding to the amortized principal balance. However, for revolving credit facilities, commercial letters of credit, and derivative contracts, Exposure at Default is dynamic and uncertain.
Lenders utilize credit conversion factors to estimate the portion of undrawn credit lines that borrowers are likely to draw down prior to defaulting. By multiplying the three core components together, risk managers derive Expected Loss:
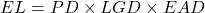

This mathematical relationship serves as the foundational equation for provisioning loan losses and pricing commercial credit facilities globally.
The Role and Limitations of Credit Rating Agencies
Credit rating agencies play a pivotal institutional role in global capital markets by synthesizing complex financial data into standardized letter-grade ratings. Major agencies, including S&P Global and Moody’s, provide independent assessments of creditworthiness for corporate issuers, municipal entities, and sovereign governments. These ratings facilitate transparent capital allocation, allowing institutional investors, pension funds, and asset managers to navigate fixed-income markets efficiently.
Uses of Credit Ratings in Global Finance
Credit ratings serve multiple vital functions across the financial ecosystem:
- Reducing information asymmetry between corporate borrowers and retail or institutional investors who lack the resources to conduct exhaustive proprietary credit analysis.
- Establishing regulatory compliance baselines, as many institutional mandates and regulatory statutes restrict investment portfolios to investment-grade securities, defined typically as BBB- or Baa3 and above.
- Determining collateral eligibility for central bank discount window operations and repo market transactions, ensuring smooth monetary policy transmission and liquidity management.
- Facilitating efficient benchmark pricing for primary debt issuances, where a borrower’s rating directly dictates its initial credit spread and cost of capital.
Limitations and Structural Flaws of Credit Ratings
Despite their widespread utility, credit rating agencies possess notable limitations that have been exposed during major financial crises. Recognizing these vulnerabilities is essential for modern risk management:
- Rating Agency Conflicts of Interest: The dominant business model relies on the issuer-pays principle, where the corporate entity issuing the debt pays the rating agency for the assessment. This creates an inherent conflict of interest, as agencies may face commercial pressure to award favorable ratings to retain clients.
- Lagging Indicator Nature: Credit ratings are often reactive rather than proactive. Agencies tend to adjust ratings after deterioration has already occurred, sometimes resulting in sudden, multi-notch cliff downgrades during severe liquidity shocks.
- Model and Assumption Blind Spots: Historical default data may fail to capture unprecedented systemic risks, tail events, or complex structured finance products, as famously witnessed during the subprime mortgage crisis.
- Procyclicality: Mass downgrades by rating agencies during economic downturns can exacerbate credit crunches, forcing institutional investors to dump downgraded bonds into illiquid secondary markets and depressing asset prices further.
Macroeconomic, Market, and Issuer-Specific Factors Influencing Yield Spreads
Yield spreads represent the additional compensation demanded by investors to hold risky debt over risk-free benchmarks. The level and volatility of these spreads fluctuate constantly in response to a multifaceted array of macroeconomic, market, and issuer-specific drivers.
| Factor Category | Primary Drivers | Impact on Yield Spreads |
| Macroeconomic | GDP growth, inflation, monetary policy, central bank interest rate cycles | Expands spreads during economic contractions; compresses spreads during expansionary phases. |
| Market-Specific | Market liquidity, systemic volatility indices, investor risk appetite, supply-demand dynamics | Widens spreads during liquidity freezes or heavy new issuance supply overhangs. |
| Issuer-Specific | Leverage ratios, operating cash flow stability, business model resilience, management quality | Narrows spreads for pristine balance sheets; widens spreads for distressed or over-leveraged corporations. |
Macroeconomic Drivers
Macroeconomic conditions exert a dominant gravitational pull on credit spreads across all rating tiers. During periods of robust economic expansion, corporate revenues surge, default rates remain subdued, and investor confidence drives yield spreads to cyclical tight levels. Conversely, when central banks tighten monetary policy aggressively to combat inflation—pushing benchmark rates higher—borrowing costs escalate. This puts immense strain on highly leveraged companies, causing credit spreads to widen dramatically as default expectations rise.
Inflation also erodes the real value of fixed-income cash flows, while macroeconomic uncertainty forces investors to demand higher risk premiums, elevating overall yield volatility.
Market-Specific Influences
Market structure and liquidity conditions dictate the day-to-day pricing and volatility of credit spreads. Market liquidity refers to the ease with which fixed-income securities can be bought or sold without causing significant price disruptions. In times of market stress, dealer inventories shrink, secondary market liquidity evaporates, and bid-ask spreads widen significantly.
Systemic risk sentiment, captured by volatility measures like equity market volatility indices, directly spills over into credit markets. Furthermore, heavy primary market supply—such as a wave of corporate debt issuance following favorable regulatory announcements or refinancing cycles—can saturate investor demand, forcing issuers to offer wider concessions and higher yield spreads to clear transactions.
Issuer-Specific Determinants
While macro and market factors set the broad environment, issuer-specific fundamentals determine relative value and idiosyncratic credit differentiation. Key metrics evaluated by investors include:
- Leverage ratios, such as total debt to earnings before interest, taxes, depreciation, and amortization.
- Interest coverage ratios, which measure a firm’s ability to service its debt obligations from operating earnings.
- Cash flow stability and working capital management, ensuring the business can withstand temporary revenue shocks without facing liquidity shortfalls.
- Corporate governance, strategic vision, and capital allocation discipline.
For example, industrial manufacturers undergoing capital-intensive transitions, such as Ford Motor Company reallocating capital toward electric vehicle platforms, experience heightened scrutiny regarding cash burn and debt sustainability, directly impacting their credit spread volatility compared to asset-light technology corporations.
Conclusion
Credit risk management is a dynamic discipline requiring rigorous quantitative analysis, comprehensive qualitative evaluation, and continuous monitoring of macroeconomic and market variables. By thoroughly understanding the components of credit risk—Probability of Default, Loss Given Default, and Exposure at Default—financial professionals can accurately price risk and structure resilient portfolios.
At the same time, recognizing the dual utility and limitations of credit rating agencies prevents over-reliance on external benchmarks. Ultimately, mastering the complex interplay of macroeconomic, market, and issuer-specific drivers of yield spreads enables executives, investors, and advisors to navigate volatile credit cycles and foster sustainable financial performance across global markets.

