Evaluating investment performance and corporate valuation requires selecting the appropriate financial metric tailored to an entity’s underlying capital structure, business model, and accounting realities.
While Earnings Per Share (EPS) serves as the standard earnings baseline for general corporations, specialized corporate entities—such as Real Estate Investment Trusts (REITs) and Master Limited Partnerships (MLPs)—rely on non-GAAP cash metrics like Funds From Operations (FFO), Adjusted Funds From Operations (AFFO), and Distributable Cash Flow (DCF).
Evaluating operating performance and dividend sustainability requires matching each asset class to its true economic earnings base.
Evaluating Capital Structure and Industry Realities
Traditional corporate accounting operates under the assumption that long-term physical assets degrade over time, deducting non-cash depreciation and amortization (D&A) to arrive at GAAP Net Income and EPS. However, capital-intensive asset-owning businesses face unique accounting distortions:
- Real Estate (REITs): Real estate assets historically hold or appreciate in value rather than steadily declining on a straight-line basis. Subtracting substantial non-cash real estate depreciation artificially depresses GAAP EPS, masking true operating cash flow.
- Energy & Infrastructure (MLPs): Master Limited Partnerships operate long-lived energy infrastructure assets (such as pipelines, storage, and processing plants) that require heavy initial capital outlays but maintain durable cash flows over decades.
- General Corporations: C-Corporations across technology, manufacturing, and consumer sectors convert profits into shareholder value primarily through reinvestment in growth, making net profitability (EPS) and free cash flow (FCF) the standard measures of health.
Comparing Sector-Specific Earnings Baselines
| Asset Class | Primary Earnings Metric | Primary Valuation Multiple | Core Purpose & Adjustments |
| General Corporations | Earnings Per Share (EPS) | Price / Earnings (P/E) | Measures GAAP net income attributable to common equity divided by diluted share count. |
| REITs (Baseline) | Funds From Operations (FFO) | Price / FFO (P/FFO) | Adjusts GAAP net income by adding back real estate depreciation and subtracting property sale gains. |
| REITs (Refined) | Adjusted FFO (AFFO) | Price / AFFO (P/AFFO) | Deducts recurring maintenance capex and tenant improvement costs from FFO to reflect true distributable cash flow. |
| MLPs / Energy Infrastructure | Distributable Cash Flow (DCF) | Price / DCF or Yield | Measures net cash flow generated by operations available for distribution to unitholders after maintenance capex and debt service. |
Standard Corporate Entities: Earnings Per Share (EPS)
For general C-Corporations, GAAP Net Income divided by diluted share count provides the foundational metric for equity valuation.
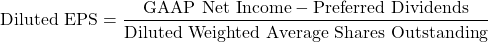

When EPS Applies Best
- Capital-Light Companies: Software and services businesses where capital expenditures and depreciation burdens are minimal relative to revenue.
- Growth and Reinvestment Models: Corporations that retain the vast majority of their earnings to reinvest in research, acquisitions, or operational scaling rather than distributing dividends.
Limitations of EPS
- Non-Cash Distortions: Heavy non-cash charges (depreciation, amortization of intangibles, stock-based compensation) can obscure cash generation.
- Capital Structure Sensitivity: Highly leveraged companies can report volatile EPS due to fixed interest expense, making Enterprise Value multiples (e.g., EV/EBITDA) necessary supplements.
Real Estate Investment Trusts: FFO vs. AFFO
REITs are legally required to distribute at least 90% of their taxable income to shareholders, shifting investor focus from GAAP earnings to ongoing dividend-paying capacity.
1. Funds From Operations (FFO)
Defined by the National Association of Real Estate Investment Trusts (Nareit), FFO removes accounting noise caused by real estate depreciation and one-time sales.
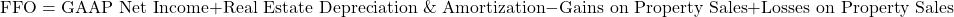

2. Adjusted Funds From Operations (AFFO)
While FFO addresses non-cash depreciation, it fails to account for the ongoing capital required to maintain physical properties. AFFO (also referred to as Cash Available for Distribution) adjusts for recurring capital expenditures, tenant improvement (TI) allowances, leasing commissions, and straight-line rent adjustments.
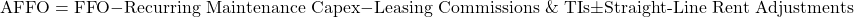

+-------------------------------------------------------+
|                   GAAP Net Income                     |
+-------------------------------------------------------+
                           |
                           v  (+) Real Estate Depreciation & Amortization
                           |  (-) Gains on Sales of Property
+-------------------------------------------------------+
|             Funds From Operations (FFO)               |
+-------------------------------------------------------+
                           |
                           v  (-) Recurring Maintenance Capex & Leasing Costs
                           |  (+/-) Straight-Line Rent Adjustments
+-------------------------------------------------------+
|        Adjusted Funds From Operations (AFFO)          |
+-------------------------------------------------------+
Sector Adjustments Across REIT Sub-Types
- Triple-Net Lease REITs (e.g., Realty Income, Store Capital): Tenants pay property taxes, insurance, and maintenance. Maintenance capex is minimal, causing FFO and AFFO to closely converge.
- Office and Retail REITs (e.g., Boston Properties, Simon Property Group): Require significant ongoing tenant improvements and leasing commissions upon lease renewals. AFFO is substantially lower than FFO and serves as the primary gauge of dividend safety.
Master Limited Partnerships: Distributable Cash Flow (DCF)
MLPs operate primarily as pass-through entities in the midstream energy and pipeline infrastructure space. Because MLPs pay out distributions rather than corporate dividends, investors focus on Distributable Cash Flow (DCF).
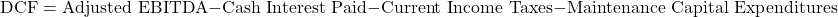

Key Metrics for MLP Analysis
- Distribution Coverage Ratio: Evaluates the safety margin of cash payouts to unitholders.
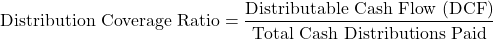

- A coverage ratio above


- Maintenance vs. Growth Capex: MLPs explicitly separate maintenance capex (spending required to preserve existing asset throughput) from expansion capex (discretionary spending on new pipeline infrastructure). Only maintenance capex is deducted to arrive at DCF.

Comparing Financial Metrics Across Models
| Metric | Cash vs. Non-Cash | Deducts Maintenance Capex? | Standard Usage Context |
| EPS | Mixed (includes non-cash D&A) | No (D&A acts as proxy) | General Corporate Profitability |
| FFO | Cash-focused | No | Standardized REIT Operational Performance |
| AFFO | Pure Residual Cash | Yes | REIT Dividend Capacity & Valuation |
| DCF | Pure Residual Cash | Yes | MLP Distribution Safety & Coverage |
Selecting the Correct Metric
- For General Corporations: Use EPS and Free Cash Flow (FCF) to evaluate profitability and reinvestment potential.
- For Quick REIT Screenings: Use FFO for standardized comparisons across peers, as Nareit rules keep the calculation consistent.
- For REIT Dividend Underwriting: Use AFFO to analyze true cash generation after property upkeep and tenant acquisition costs.
- For MLPs & Energy Infrastructure: Use DCF and the Distribution Coverage Ratio to verify that operational cash flow covers unitholder payouts after interest and maintenance spending.

