The Valuation of Contingent Claims forms the bedrock of modern quantitative finance, derivative pricing, and institutional risk management.
A contingent claim is a financial asset whose payoff depends directly on the future value or state of an underlying variable, such as an equity share price, benchmark interest rate, foreign currency exchange rate, or commodity index.
Financial institutions like Goldman Sachs and derivative exchanges like CME Group rely on the Valuation of Contingent Claims to establish fair no-arbitrage prices, construct dynamic hedge positions, and manage balance sheet risk across volatile global markets.
Foundations of Contingent Claim Valuation and the Binomial Framework
A contingent claim provides its holder with a payoff contingent on future market outcomes. Options are the most pervasive form of contingent claims, categorized as European options (exercisable strictly at expiration) or American options (exercisable at any point up to expiration).
The discrete-time foundation for option pricing is the binomial option valuation model. Developed by Cox, Ross, and Rubinstein, this model assumes that over a discrete time step 


The Binomial Model Parameters and Component Terms
To prevent riskless arbitrage in the asset market, the inequality 


- Up Factor (


- Down Factor (

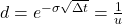
- Risk-Neutral Probability (


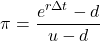

For discrete compounding over time step
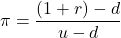

- Risk-Neutral Discount Factor: The term


Option Value as the Present Value of Expected Risk-Neutral Payoff
In a risk-neutral world, investors are indifferent to risk, meaning all assets earn the risk-free rate of return 

For a one-period option with payoffs 


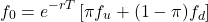

This risk-neutral valuation framework does not require estimating actual market risk premiums or real-world probabilities of asset price appreciation. The option value is dictated entirely by no-arbitrage replication.
Identifying Arbitrage Opportunities and Arbitrage Execution
An arbitrage opportunity exists whenever a contingent claim’s market price deviates from its synthetic replication cost. A replicating portfolio combines 


The hedge ratio
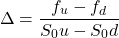

The required risk-free borrowing or lending amount
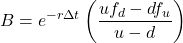

If an option is mispriced relative to its theoretical value 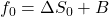

- Overvalued Option (

- Undervalued Option (


Two-Period Binomial Valuation for Equity and Interest Rate Options
Extending the binomial model to multiple periods allows quantitative analysts at firms such as JPMorgan Chase to price complex path-dependent and early-exercisable securities.
No-Arbitrage Values of European and American Options
Consider a two-period binomial model for an equity stock currently trading at 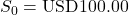


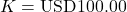


First, we calculate the risk-neutral probability
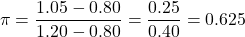

The down-probability is 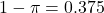

The underlying stock price tree across two periods develops as follows:
| Period 0 (t=0) | Period 1 (t=1) | Period 2 (t=2) |
| 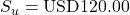 | 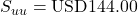 |
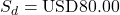 | 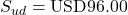 | |
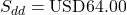 |


European Call Option Valuation
At expiration (
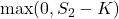






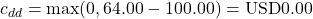
Working backward to Period 1 (

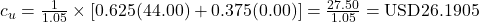

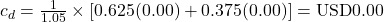
At Period 0 (


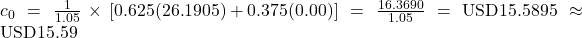
European and American Put Option Valuation
At expiration (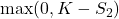

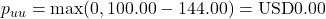

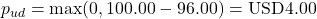

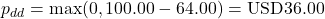
For a European Put Option, discounting back to Period 1:

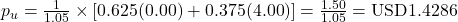

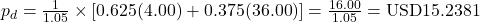
At Period 0 (


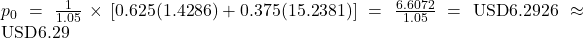
For an American Put Option, early exercise is evaluated at each node by comparing the intrinsic exercise value (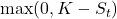

- At Node


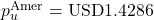
- At Node
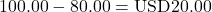

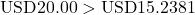
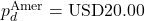


At Period 0 (

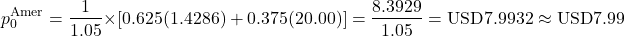

The early exercise feature adds 



| Option Type | Node d Value (t=1) | Node u Value (t=1) | Initial Option Value (t=0) |
| European Call | |  |  |
| European Put |  |  |  |
| American Put |  | |  |


Two-Period Binomial Interest Rate Option Valuation
Interest rate options differ from equity options because the underlying asset is a short-term interest rate or bond price, where interest rates exhibit mean-reverting dynamics and volatility structures.
Consider a 2-period interest rate model where short-term one-period interest rates evolve under risk-neutral probabilities 


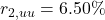
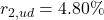
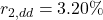


We evaluate a 1-year interest rate caplet with strike rate 
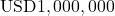


At 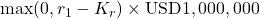


- If rate rises to
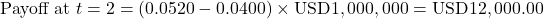

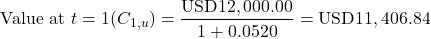

- If rate falls to
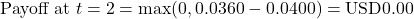

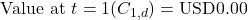

Discounting back to
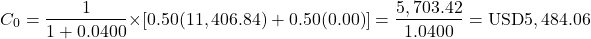

The present value of the interest rate caplet is 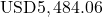

The Continuous-Time Framework: Black-Scholes-Merton Model
The Black-Scholes-Merton (BSM) model extends option valuation into continuous time, establishing analytical closed-form pricing formulas for European contingent claims.
Assumptions of the Black-Scholes-Merton Model
The validity of the BSM model relies on explicit ideal market conditions:
- Log-Normal Stock Returns: Stock prices follow continuous Geometric Brownian Motion with constant drift

- Continuous Trading: Trading occurs continuously in time with zero transaction costs, market impact, or tax friction.
- Constant Risk-Free Rate: The short-term risk-free interest rate
- Short Selling Permitted: Short sales are allowed without restrictions, receiving full interest credit on cash proceeds.
- No Dividend Leakage: The underlying stock pays no cash dividends during the option’s lifespan (adjusted in modified models).
- No Early Exercise: Options are European-style, exercisable only at expiration date
- No Arbitrage: Financial markets are perfectly efficient, preventing riskless arbitrage.

BSM Call Option Formula and Leveraged Position Interpretation
The BSM formula for a European call option pricing on a non-dividend paying equity 


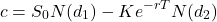

where:
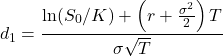

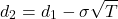

and 

Financial managers interpret the BSM call formula as a leveraged long position in the underlying asset:


Consequently, buying a call option is equivalent to purchasing
BSM Extensions: Equities with Dividend Yields and Currency Options
To value options on dividend-paying equities or foreign exchange contracts, the core BSM formulation is adjusted for continuous yield structures.
Options on Equities Paying a Continuous Dividend Yield
When an equity index or stock pays a continuous dividend yield 

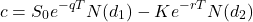

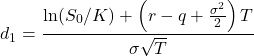

European Currency Options (Garman-Kohlhagen Model)
In foreign exchange markets utilized by international banks like HSBC, holding a foreign currency earns the foreign risk-free interest rate 

Under the Garman-Kohlhagen model, where
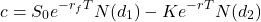

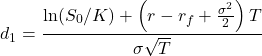

The Black Model for Futures, Fixed Income, and Swaptions
Fischer Black modified the BSM continuous framework to price options where the underlying asset is a futures contract, forward contract, or interest rate instrument.
Black Model for Options on Futures
Futures options trade heavily on derivative markets managed by CME Group. Because entering a futures contract requires zero upfront capital outlay, the cost of carry is embedded entirely within the futures price 
The price of a European call option on a futures contract under the Black model is:
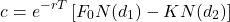

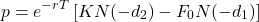

where:
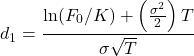

Here, 

Black Model for Interest Rate Options and Swaptions
Fixed income desks use the Black model to price European interest rate options (caps and floors) and swaptions.
European Interest Rate Caps and Floors
An interest rate cap is a portfolio of individual European options called caplets. A caplet setting at time 


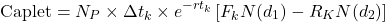

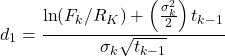

An interest rate floor is similarly decomposed into floorlets priced using European put mechanics.
European Swaptions
A swaption is an option to enter into an interest rate swap. A payer swaption gives the holder the option to pay a fixed swap rate
Using the Black model, the value of a payer swaption with exercise date 


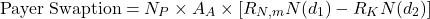

where the annuity factor
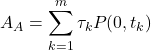

Here 


Option Greeks, Dynamic Delta Hedging, and Gamma Risk
Risk management requires understanding how option values respond to changing market parameters, measured by the option “Greeks.”
Interpretation of Option Greeks
| Greek | Mathematical Definition | Financial Interpretation | Typical Sign |
| Delta ( |  | Change in option price per USD1.00 change in underlying price. Acts as hedge ratio. | Call:  Put:  |
Gamma ( |  | Rate of change of Delta per USD1.00 change in underlying price. Measures non-linear acceleration. | Always Positive for Long Options |
Vega ( | 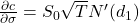 | Change in option value per 1.00% (100 bps) change in implied volatility. | Always Positive for Long Options |
Theta ( |  | Time decay; rate of decline in option value as expiration approaches, assuming all else constant. | Generally Negative for Long Options |
Rho ( | 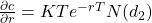 | Sensitivity of option value to a 1.00% (100 bps) shift in risk-free interest rates. | Positive for Calls Negative for Puts |


Execution of a Delta Hedge
A delta-hedged portfolio insulates an equity trading desk against small directional moves in the underlying asset.
Suppose an institutional market maker at Deutsche Bank writes (shorts) 1,000 OTC call options contracts on Apple stock (representing 100,000 shares). The options currently have a Delta (

To create a delta-neutral portfolio:
- Calculate Total Short Delta:
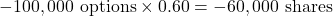
- Execute Initial Hedge: Buy

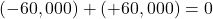
- Dynamic Rebalancing: Delta changes continuously as stock prices move and time elapses.
- If Apple share price rises, option

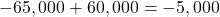

- If Apple share price falls, option

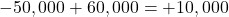

- If Apple share price rises, option


Dynamic rebalancing forces a short option hedger to “buy high and sell low,” creating rebalancing costs known as the cost of hedging gamma.
The Role of Gamma Risk in Options Trading
Gamma (
- At-the-Money Concentration: Gamma reaches its maximum for at-the-money options close to expiration.
- Short Gamma Exposure: Traders who short options are short gamma. Large underlying price gaps generate convex losses, as delta shifts against the position faster than rebalancing can occur.
- Pin Risk: Near expiration date
Implied Volatility, Volatility Smiles, and Market Application
While BSM model parameters such as stock price, strike, interest rates, and time to maturity are directly observable, asset price volatility (
Definition and Extraction of Implied Volatility
Implied Volatility (IV) is the annual standard deviation parameter 

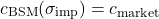

Because the BSM equation cannot be inverted analytically for
Volatility Smiles, Skews, and Surfaces
The theoretical BSM model assumes constant volatility across all strike prices and maturities. However, empirical market prices derived after the 1987 equity crash reflect a distinct non-flat volatility surface:
- Volatility Skew (Equity Markets): Out-of-the-money (OTM) put options exhibit significantly higher implied volatility than OTM call options. This downward-sloping skew reflects institutional demand for downside tail-risk protection (crash phobia).
- Volatility Smile (Foreign Exchange): Deep OTM call options and deep OTM put options both command higher implied volatilities than ATM options, reflecting fat-tailed probability distributions (kurtosis) in currency markets.
Trading Volatility in Institutional Derivatives Markets
Institutional participants utilize implied volatility for structural strategy execution:
- Relative Value Volatility Trading: Identifying mispriced options by comparing implied volatility across strikes (skew trading) or against realized historical volatility.
- Volatility as an Asset Class: Positioning directly in volatility using index derivatives such as VIX futures and options on CME Group.
- Vega Hedging: Constructing multi-leg option strategies (straddles, variance swaps) to isolate pure volatility movement while neutralizing directional delta risk.
Strategic Implications for Executive Decision-Makers
The Valuation of Contingent Claims provides senior management and corporate decision-makers with quantitative tools that extend far beyond listed option trading desks.
+---------------------------------------------------------------------------------------------------+
|                            APPLICATIONS OF CONTINGENT CLAIMS VALUATION                            |
+------------------------------------+--------------------------------+-----------------------------+
| Real Options Analysis              | Corporate Capital Structure    | Executive Compensation      |
+------------------------------------+--------------------------------+-----------------------------+
| • Capital Budgeting Flexibility    | • Merton Model Debt Valuation  | • Performance Option Grants |
| • Delay & Expansion Options        | • Default Option Analysis      | • Risk-Incentive Alignment  |
| • Abandonment Valuations           | • Credit Risk Spreads          | • Restrictive Stock Units   |
+------------------------------------+--------------------------------+-----------------------------+
Capital Budgeting and Real Options Analysis
Traditional Net Present Value (NPV) techniques ignore managerial flexibility in multi-stage corporate investments. Corporate strategic planners apply contingent claim valuation principles through Real Options Analysis:
- Option to Delay: Valuing the strategic capability of companies like Shell to defer major capital expenditure investments until market demand uncertainty resolves.
- Option to Expand or Abandon: Pricing the embedded flexibility within industrial facilities to expand capacity or liquidate assets under adverse conditions.
Corporate Debt Valuation and Credit Risk (Merton Structural Model)
Under the Merton structural model of corporate credit risk, a company’s capital structure is framed as contingent claims on total enterprise assets
- Corporate Debt: Equivalent to holding a risk-free bond minus a short put option on company assets with strike equal to the face value of debt

- Corporate Equity: Equivalent to a European call option on total firm assets

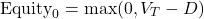

If firm asset value 

Managerial Recommendations
To optimize corporate financial strategy using contingent claim methodology, executive leaders should:
- Integrate Real Options into Strategic Planning: Supplement static discounted cash flow models with binomial decision trees for flexible capital projects.
- Mitigate Non-Linear Balance Sheet Risks: Corporate treasurers must monitor gamma risk when hedging commercial exposures with option overlay structures.
- Calibrate Executive Incentive Compensation: Design executive stock option schemes using modern option pricing adjustments to prevent excessive risk-taking driven by vega incentives.

