This comprehensive analysis of fixed-income active management: credit strategies evaluates the core analytical models, portfolio positioning techniques, liquidity management practices, and risk mitigation tools utilized by institutional asset managers across corporate and structured credit markets.
Introduction
In institutional asset management, fixed-income active management: credit strategies serve as a primary mechanism for generating alpha above traditional benchmark indices, such as the Bloomberg Global Aggregate Corporate Index.
Global institutional investors, including BlackRock and PIMCO, employ sophisticated credit strategies to exploit market inefficiencies, mispriced credit risk, and macroeconomic structural shifts. Active credit managers navigate a dynamic landscape where credit spreads reflect not only fundamental default probabilities and expected recovery rates, but also systemic liquidity conditions, regulatory frameworks, and broader macroeconomic cycles.
Achieving consistent, superior risk-adjusted returns requires a rigorous integration of top-down economic forecasting, bottom-up fundamental credit selection, derivative-based risk overlays, and advanced quantitative risk modeling.
Risk Considerations in Spread-Based Fixed-Income Portfolios
Managing a spread-based fixed-income portfolio requires identifying, quantifying, and mitigating multiple distinct categories of credit-related risk. Spread risk represents the sensitivity of a bond’s price to changes in its credit spread relative to a benchmark risk-free yield curve.
- Default Risk and Loss Given Default: Default risk is the probability that an issuer fails to make timely principal or interest payments. Active managers evaluate expected loss by multiplying the Probability of Default (PD) by Loss Given Default (LGD), where LGD equals one minus the recovery rate.
- Credit Migration Risk: Also known as downgrade risk, this reflects the probability that a credit rating agency downgrades an issuer’s credit rating. Downgrades typically trigger immediate spread widening and price depreciation, forcing institutional mandates with strict investment-grade criteria to liquidate holdings at depressed valuations.
- Credit Spread Volatility Risk: Spreads fluctuate continuously due to shifts in broader market sentiment, investor risk appetite, and liquidity conditions, independent of changes in an issuer’s fundamental credit quality.
- Liquidity Risk: Credit instruments trade primarily over-the-counter (OTC). Liquidity risk arises when a manager cannot execute large transactions promptly without incurring significant execution slippage or wide bid-ask spreads.
- Spread Duration and Interest Rate Risk: While benchmark interest rate risk (measured by Effective Duration) captures sensitivity to risk-free rate movements, Spread Duration measures price sensitivity to changes in the credit spread itself.
- Tail Risk and Correlation Breakdown: During systemic financial crises, historical asset return correlations frequently break down, causing credit spreads across disparate sectors to widen simultaneously and creating severe drawdown risk.
Evaluating Credit Spread Measures and the Supremacy of Option-Adjusted Spread
Accurate pricing of credit risk requires evaluating various spread metrics, each designed to capture specific yield differentials while controlling for underlying curve shapes and embedded option features.
| Spread Measure | Calculation Methodology | Primary Advantages | Primary Disadvantages |
| Nominal Spread | Bond Yield minus Benchmark Government Bond Yield | Simple to compute; universally quoted in primary markets. | Ignores the shape of the yield curve and option embeddedness. |
| Zero-Volatility Spread (Z-Spread) | Constant spread added to each spot rate on the Treasury yield curve | Accounts for the full term structure of risk-free spot rates. | Assumes cash flows are static; fails to price embedded options. |
| Option-Adjusted Spread (OAS) | Spread resulting from stripping embedded option values via option pricing models | Isolates true credit and liquidity risk; enables cross-asset comparisons. | Model-dependent; highly sensitive to interest rate volatility assumptions. |
| Asset Swap Spread | Fixed coupon spread paid over floating benchmark (e.g., SOFR) via interest rate swap | Directly reflects economic returns for floating-rate funded institutions. | Distorted by swap market supply/demand dynamics and bank balance sheet costs. |
| CDS Basis | Single-Name CDS Premium minus Cash Bond Z-Spread / OAS | Identifies arbitrage opportunities between derivative and cash markets. | Subject to funding constraints, short-sale restrictions, and legal deliverability risk. |
Why Option-Adjusted Spread is the Most Appropriate Measure
Option-Adjusted Spread (OAS) is considered the definitive metric for spread-based fixed-income portfolios containing callable or putable corporate bonds. Standard corporate bonds, such as those issued by industrial borrowers like AT&T or Ford Motor Company, frequently feature embedded call options that allow the issuer to refinance debt when interest rates decline.
Because an embedded call option benefits the issuer at the expense of the bondholder, traditional yield spreads and Z-spreads artificially overstate the credit compensation offered by callable securities. OAS uses an interest rate tree or Monte Carlo simulation framework to model potential future interest rate paths, value the embedded options at each node, and dynamically adjust the bond’s expected cash flows. By removing the compensation associated with option volatility, OAS isolates the pure credit risk and liquidity premium. This enables portfolio managers to make fair, normalized relative-value comparisons across callable bonds, non-callable issues, and agency mortgage-backed securities.
Bottom-Up Approaches to Credit Strategies
Bottom-up credit strategies focus on security-level research and individual issuer selection, seeking to identify mispriced bonds relative to their intrinsic fundamental credit risk.
- Fundamental Credit Analysis: Portfolio managers evaluate an issuer’s financial strength through rigorous balance sheet analysis, focusing on key leverage metrics (such as Total Debt to EBITDA), interest coverage ratios (EBITDA to Interest Expense), free cash flow conversion, and liquidity profile.
- Industry and Competitive Positioning: Managers assess an issuer’s business profile, market share, pricing power, regulatory exposure, and operational barriers to entry to determine cash flow stability across economic cycles.
- Capital Structure Relative Value: Issuers often maintain complex capital structures with multiple debt tiers, including senior secured bank loans, senior unsecured bonds, subordinated debt, and preferred equity. Bottom-up managers evaluate the relative risk-reward trade-off across these capital tiers to identify mispriced tranches.
- Cross-Issuer Curve Analysis: By comparing the spread curves of issuers within the same industry sector and rating category, managers identify structural pricing anomalies along the maturity spectrum.
- Event-Driven Credit Opportunities: Bottom-up strategies exploit corporate restructurings, leveraged buyouts, spin-offs, and merger activity where debt re-profiling or rating changes create tactical entry points.
Top-Down Approaches to Credit Strategies
Top-Down credit strategies emphasize macroeconomic forecasting, market cycle identification, and top-level portfolio beta management to capitalize on broad market trends.
- Macroeconomic and Business Cycle Analysis: Portfolio managers analyze real GDP growth, corporate earnings trends, inflation patterns, monetary policy trajectories, and fiscal policies to determine the current phase of the credit cycle.
- Credit Cycle Positioning: During early expansion phases, top-down managers increase overall portfolio credit risk (beta) to capture spread compression. Conversely, in late-cycle or contractionary environments, managers de-risk portfolios by increasing quality allocations and shortening spread duration.
- Sector Allocation and Rotation: Managers tactically tilt portfolios toward sectors expected to outperform based on macro trends. For instance, defensive, non-cyclical sectors (e.g., healthcare and utilities) are favored during economic downturns, whereas consumer discretionary and industrial issuers are prioritized during early economic expansions.
- Quality Allocation (IG vs. High Yield): Top-down managers adjust portfolio weightings between Investment Grade (IG) and High Yield (HY) segments based on macroeconomic forecasts, default expectations, and risk premiums. For example, when US High Yield option-adjusted spreads compress significantly below historical averages—such as reaching USD270 basis points—managers may scale back lower-tier credit exposure in favor of high-quality corporate issues.
- Global Macro Interventions: Institutional investment houses like JPMorgan Chase and Goldman Sachs utilize top-down framework adjustments to capture regional credit cycle divergences between North American, European, and Emerging Market economies.
Liquidity Risk and Mitigation Frameworks in Credit Markets
Liquidity risk in corporate credit markets is intrinsically linked to the decentralized over-the-counter (OTC) market structure. Unlike exchange-traded equities, thousands of individual corporate bond issues trade infrequently, leading to market fragmentation and execution challenges during periods of market volatility.
+-----------------------------------------------------------------------------------+
|                        CREDIT PORTFOLIO LIQUIDITY MANAGEMENT                      |
+-----------------------------------------------------------------------------------+
                                          |
          +-------------------------------+-------------------------------+
          |                               |                               |
          v                               v                               v
+-------------------+           +-------------------+           +-------------------+
|  PRIMARY BUFFERS  |           |  DERIVATIVE PROXIES|           | STRUCTURAL TOOLS  |
+-------------------+           +-------------------+           +-------------------+
| • Cash Equivalents|           | • CDX / iTraxx    |           | • Maturity Ladder |
| • On-the-Run      |           |   Index Swaps     |           | • Issuer/Sector   |
|   Treasuries      |           | • Total Return    |           |   Caps            |
| • Agency MBS      |           |   Swaps (TRS)     |           | • Portfolio Trade |
|                   |           | • Liquid Bond ETFs|           |   Facilities      |
+-------------------+           +-------------------+           +-------------------+
To manage liquidity risk effectively without sacrificing structural portfolio yield, active fixed-income active management: credit strategies employ multi-layered liquidity buffers and execution frameworks:
- Cash and Cash-Equivalent Buffers: Maintaining a dedicated allocation to highly liquid assets, such as short-dated Treasury bills and short-term repo facilities, provides immediate cash flow for investor redemptions or tactical opportunistic purchases.
- Liquid Proxy Overlays: Utilizing credit default swap indices (such as CDX or iTraxx) and liquid credit exchange-traded funds (ETFs) allows managers to adjust portfolio credit beta instantly without executing costly transactions in illiquid single-name cash bonds.
- Staggered Maturity Structures: Designing maturity ladders creates predictable cash inflows from maturing bonds, reducing the necessity of forced secondary market liquidations.
- Portfolio Trading and Electronic Execution: Leveraging portfolio trading facilities hosted by major liquidity providers, such as Barclays, enables managers to execute multi-bond baskets efficiently at competitive execution costs.
Assessing and Managing Tail Risk in Credit Portfolios
Tail risk represents the probability of extreme, asymmetric downside losses occurring in the far left tail of a return distribution. Traditional linear risk models often underestimate tail risk because credit returns exhibit negative skewness and excess kurtosis (fat tails).
Quantitative Assessment Tools
While standard Value at Risk (VaR) measures maximum expected loss at a given confidence level (e.g., 99% over a 10-day horizon), it fails to quantify the magnitude of losses beyond that threshold. Active credit managers utilize Expected Shortfall (ES)—also termed Conditional VaR (CVaR)—to calculate the average loss incurred when the threshold is breached. Furthermore, managers employ Extreme Value Theory (EVT) to parameterize fat-tail behavior and model joint default distributions during systemic crashes.
Tail Risk Mitigation Strategies
- Credit Index Put Options: Purchasing out-of-the-money (OTM) put options on CDX or iTraxx credit indices provides explicit, capped-cost protection against systemic spread blowouts.
- Swaption Strategies: Payer swaptions grant the manager the right to enter into a credit default swap as a protection buyer at a specified strike spread, hedging severe credit deterioration.
- Macro Factor Hedging: Structuring long/short tail positions using interest rate swaptions, equity volatility index (VIX) options, or cross-currency put positions hedges against systemic liquidity contractions.
- Scenario Stress Testing: Conducting forward-looking stress tests that simulate historical liquidity shocks (e.g., the 2008 Global Financial Crisis or the March 2020 market dislocation) helps managers evaluate portfolio survival capacity under extreme stress.
Credit Default Swap Strategies in Active Portfolio Management
Credit Default Swaps (CDS) are essential derivative instruments in fixed-income active management: credit strategies, offering unfunded, highly liquid mechanisms for managing credit exposure, executing relative value trades, and implementing macro views.
                     +---------------------------------------+
                     |        PROTECTION BUYER (LONG CDS)    |
                     +---------------------------------------+
                                   |           ^
       Pays Periodic Premium       |           |  Contingent Credit Payment
       (e.g., 100 bps / 500 bps)   |           |  (Par minus Recovery Value)
                                   v           |  Upon Default Event
                     +---------------------------------------+
                     |        PROTECTION SELLER (SHORT CDS)  |
                     +---------------------------------------+
Core CDS Active Management Applications
- Synthetic Credit Beta Adjustments: Selling protection via CDX or iTraxx indices increases portfolio credit exposure rapidly without the settlement delays or balance sheet demands associated with physical cash bond purchases.
- Single-Name CDS Hedging: Buying single-name CDS protection allows managers to hedge default risk on specific high-conviction holdings without triggering taxable capital gains or disrupting long-term client-issuer relationships.
- Basis Trading: The CDS-bond basis measures the difference between single-name CDS spreads and cash bond option-adjusted spreads (
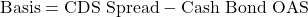
- Positive Basis Trade: When CDS spreads exceed cash bond OAS, managers buy the cash bond and buy CDS protection to lock in a riskless yield spread.
- Negative Basis Trade: When cash bond OAS exceeds CDS spreads, managers sell the cash bond short (or enter a payer swap) and sell CDS protection.
- Curve Trades: Managers exploit shifts in the steepness of CDS credit curves by pairing long and short CDS positions across different maturities (e.g., buying 3-year protection while selling 5-year protection to capitalize on curve flattening).

Portfolio Positioning Strategies for Credit Spread Views
When active managers form a explicit outlook on credit spreads, they implement targeted portfolio positioning strategies to maximize total return while controlling benchmark tracking risk.
- Bullet vs. Barbell Curve Positioning:
- Bullet Strategy: Concentrates holdings in a narrow maturity bucket along the credit curve. This structure is optimal when spreads in a specific curve segment are expected to compress rapidly relative to the rest of the curve.
- Barbell Strategy: Combines short-dated and long-dated credit instruments. A barbell benefits from rolling down a steep short curve while capturing high coupon income at the long end, offering flexibility during asymmetric curve shifts.
- Credit Curve Steepeners and Flatteners:
- Curve Flattener: Implemented when managers expect long-term credit spreads to compress relative to short-term spreads (often during early-stage economic recoveries).
- Curve Steepener: Implemented when late-cycle pressures elevate long-term default and refinancing risks, prompting managers to underweight long-duration credit relative to short-duration issues.
- Compression vs. Decompression Trades:
- Compression Trade: In benign, liquidity-rich environments, high-yield credit spreads compress toward investment-grade spreads. Managers go long lower-rated securities (e.g., BBB or BB credits) and short higher-rated benchmarks (e.g., Single-A credits).
- Decompression Trade: During economic downturns, credit quality differentiation widens. Managers go long high-quality credits and short lower-rated, vulnerable issuers to capitalize on widening spread differentials.
- Rating Migration and “Fallen Angel” Strategies: Active managers buy prospective “Fallen Angels”—investment-grade bonds transitioning to high yield—after initial forced selling depresses their prices, anticipating post-downgrade price recoveries.
International and Cross-Border Credit Market Considerations
Constructing global credit portfolios introduces multidimensional complexity due to regional macro divergences, structural market nuances, regulatory variations, and currency volatility. Institutional entities such as BNP Paribas operate across international jurisdictions to capitalize on cross-border relative value.
Currency Risk and Covered Interest Rate Parity
Cross-border credit investing requires managing foreign exchange (FX) volatility. Holding unhedged foreign currency corporate bonds exposes portfolios to FX movements that can completely negate underlying credit yields. Managers utilize FX forward contracts and cross-currency basis swaps to hedge currency risk back to the portfolio’s base currency.
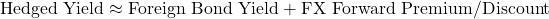

The cross-currency basis reflects balance sheet funding costs and structural dollar demand. A wider negative USD cross-currency basis increases hedging costs for non-US investors purchasing US dollar-denominated debt, directly influencing cross-border capital flows.
Regional Dynamics and Regulatory Considerations
- Market Structure Divergence: The US corporate bond market is highly disintermediated, with corporate debt representing a dominant share of business funding. In contrast, European corporate finance historically relies more heavily on bank lending, creating distinct supply dynamics and secondary market liquidity profiles.
- Sovereign Risk Ceiling: Credit analysis in emerging market corporate debt must account for the sovereign ceiling—the principle that an issuer’s rating is typically constrained by the sovereign rating of its home country due to transfer and convertibility risks.
- Legal and Insolvency Frameworks: Restructuring rights, creditor seniority, and bankruptcy enforcement procedures vary across legal jurisdictions, altering expected Loss Given Default (LGD) metrics for global assets.
Structured Financial Instruments as Alternatives to Corporate Bonds
Structured financial instruments offer active credit managers yield enhancement, tailored risk profiles, and structural bankruptcy remoteness as viable alternatives to conventional corporate bonds.
+-----------------------------------------------------------------------------------+
|                        COLLATERALIZED LOAN OBLIGATION (CLO)                       |
+-----------------------------------------------------------------------------------+
                                          |
                      Generates Leveraged Loan Pool Cash Flows
                                          |
                                          v
+-----------------------------------------------------------------------------------+
|                              CASH FLOW WATERFALL                                  |
+-----------------------------------------------------------------------------------+
|   AAA Senior Tranche        | Low Risk / Floating Rate Yield                      |
|   AA-A Mezzanine Tranche    | Medium Risk / Enhanced Spread                       |
|   BBB-BB Subordinated       | Elevated Risk / High Yield                          |
|   Equity Tranche (First Loss)| First-Loss Absorber / Residual Yield               |
+-----------------------------------------------------------------------------------+
Core Asset Classes
- Collateralized Loan Obligations (CLOs): Securitized vehicles backed by diversified pools of senior secured, floating-rate leveraged bank loans. With the global CLO market exceeding USD1.83 trillion, CLOs represent a primary source of floating-rate yield.
- Asset-Backed Securities (ABS): Bonds collateralized by pools of consumer loans, auto loans, credit card receivables, or equipment leases, offering short duration and predictable amortization schedules.
- Mortgage-Backed Securities (MBS): Includes both Agency MBS (guaranteed against credit default by government-sponsored entities) and Non-Agency Commercial/Residential MBS (CMBS/RMBS), which carry credit and prepayment risks.
Structural Advantages and Mechanics
- Credit Enhancement Features: Structured notes rely on internal credit enhancements, including overcollateralization (holding assets exceeding debt liabilities), subordination (junior tranches absorbing losses first), and excess spread interest buffers.
- Yield Pickup and Structural Protection: Mezzanine CLO tranches (rated AA to BBB) frequently offer substantial yield premiums compared to similarly rated corporate bonds, compensating for structural complexity while retaining strong credit enhancement profiles.
- Floating-Rate Protection: Because collateralized loan obligations feature variable-rate reference rates (e.g., SOFR), they insulate portfolios against benchmark duration losses during monetary tightening cycles.
Analytical Tools and Quantitative Frameworks for Portfolio Management
Modern fixed-income active management: credit strategies depend on sophisticated quantitative models to evaluate portfolio risk, run factor attribution, and execute algorithmic portfolio construction.
| Framework Component | Key Variables / Inputs | Analytical Outputs | Practical Portfolio Application |
| Spread Analytics | Credit Spread, OAS, Benchmark Spot Curve | Spread Duration, DTS (Duration Times Spread) | Quantifies spread risk across maturities and sector sub-groups. |
| Curve Risk Analytics | Key Rate Duration, Shift/Twist/Butterfly Factors | Key Rate Duration Profile | Identifies non-parallel yield curve vulnerabilities. |
| Credit Risk Engine | Default Probability (PD), Recovery Rate (LGD), Correlations | Expected Shortfall (CVaR), Marginal Contribution to Risk (MCR) | Establishes capital allocation and concentration limits. |
| Factor Attribution Model | Rates, Spreads, Sector Weights, Currency, FX Hedging | Alpha Attribution, Tracking Error Decomposition | Isolates manager skill from benchmark factor returns. |
Duration Times Spread (DTS) as the Standard Metric
Traditional Spread Duration measures absolute price sensitivity to a 100-basis-point spread change. However, it fails to capture the empirical reality that credit spreads move proportionally rather than in absolute terms. Duration Times Spread (DTS) solves this by multiplying Spread Duration by the current Option-Adjusted Spread:
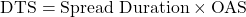

DTS provides a unified, accurate risk metric that correctly reflects the higher volatility of wider-spread, lower-rated bonds relative to tight, investment-grade issues, serving as the industry standard metric for factor exposure management.
Critical Considerations and Model Risks
Active managers must remain vigilant regarding quantitative model limitations:
- Estimation Risk: Structural shifts in economic regimes invalidate historical covariance matrices, causing historical VaR or tracking error models to understate risk during crisis periods.
- Illiquidity Pricing Lag: Evaluated pricing services frequently mark illiquid cash bonds using matrix pricing rather than live transactions, artificially smoothing reported portfolio volatility.
- Correlation Breakdown: In stress scenarios, historical default and correlation assumptions break down, triggering sudden contagion across previously uncorrelated asset classes.
Conclusions
Fixed-Income Active Management: Credit Strategies require a disciplined, holistic investment approach that balances return generation with structured risk management. Achieving consistent long-term alpha demands the seamless combination of top-down credit cycle positioning and bottom-up fundamental credit analysis. Active managers must utilize advanced spread measures, particularly Option-Adjusted Spread (OAS) and Duration Times Spread (DTS), to accurately price credit risk and eliminate embedded option distortions across global markets.
Furthermore, integrating derivative overlays—such as Credit Default Swaps (CDS)—and structured instruments—such as Collateralized Loan Obligations (CLOs)—provides active portfolios with essential liquidity, yield enhancement, and downside tail protection. As global credit markets continue to evolve alongside changing macroeconomic regimes and regulatory standards, institutional portfolio managers who effectively integrate rigorous quantitative analytics, proactive liquidity management, and multi-asset risk mitigation will remain best positioned to deliver superior risk-adjusted returns.

