The term structure of interest rates forms the foundational framework for pricing financial assets, hedging macro risks, and managing fixed-income portfolios. Understanding the dynamic relationships between spot rates, forward rates, yield to maturity, and swap curves allows portfolio managers and financial institutions to extract market-implied expectations and construct alpha-generating strategies.
An authoritative examination of term structure mechanics, detailing the quantitative interplay between spot and forward rates, curve construction via bootstrapping, swap spreads, risk metrics, and active portfolio management strategies such as rolling down the yield curve.
Fundamental Yield Concepts and Rate Dynamics
Fixed income analysis relies on distinct yield metrics, each serving a unique analytical role:
- Spot Rates (


- Forward Rates (


- Yield to Maturity (YTM): The single internal rate of return (IRR) that equates the present value of a bond’s future cash flows (coupons and principal) to its current market price. YTM represents a complex, weighted average of the spot rates corresponding to each cash flow date.


Mathematical Relationship Between Spot and Forward Rates
The forward rate is derived from spot rates through the principle of no-arbitrage. Investing in a long-term spot bond must yield the same return as investing in a shorter-term spot bond and rolling the proceeds into a forward contract over the remaining period.
In discrete compounding, the relationship between a 1-period spot rate 


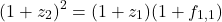

Solving for the one-period forward rate starting at period 

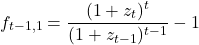

Under continuous compounding, the relationship simplifies to an exact linear identity where the long-term spot rate is the arithmetic average of current and implied forward rates:
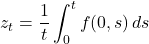

Yield Level (%)
   ^
   |                      / Implied Forward Curve f(t)
   |                     /
   |                    /-- Spot Rate Curve z(t)
   |                   //
   |                  //--- Par Yield Curve
   |                 //
   +--------------------------------------------------> Maturity (Years)
   Upward-Sloping Yield Curve Mechanics: Forward Rate > Spot Rate > Par Rate
Shape of the Yield Curve and Rate Hierarchy
The relative position of spot rates, forward rates, and par yields depends entirely on the slope of the yield curve:
- Upward-Sloping (Normal) Yield Curve: To pull the average (spot rate) up as maturity increases, the marginal rate (forward rate) must sit above the spot rate. Similarly, because coupon bonds have intermediate cash flows discounted at lower spot rates, the par yield sits below the spot rate.
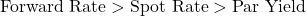
- Downward-Sloping (Inverted) Yield Curve: Marginal forward rates pull the spot curve downward.
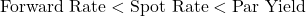
- Flat Yield Curve: Spot rates across all maturities are identical.
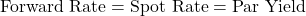

Expected vs. Realized Returns on Bonds
A bond’s expected return equals its YTM at purchase only if two strict conditions are met:
- The bond is held to maturity (eliminating price risk).
- All intermediate coupon payments are reinvested at an interest rate exactly equal to the original YTM.
The realized return will diverge from the expected YTM if intermediate coupons are reinvested at higher or lower prevailing spot rates (reinvestment risk) or if the bond is sold prior to maturity at a price determined by prevailing market yields (price/market risk).
Constructing the Spot Curve via Bootstrapping
Because zero-coupon government bonds (such as U.S. Treasury STRIPS) often exhibit liquidity pockets or tax distortions, market practitioners construct the spot curve using benchmark coupon-bearing government debt—a process known as bootstrapping.
  Par Coupon Bonds (Market Quotes)
                │
                ▼
┌─────────────────────────────────────────┐
│  Step 1: Solve Shortest Maturity Spot   │  ---> z_1 = YTM_1 (for 1-period zero)
└─────────────────────────────────────────┘
                │
                ▼
┌─────────────────────────────────────────┐
│  Step 2: Discount Known Intermediate    │  ---> Discount Coupon 1 using z_1
│          Cash Flows                     │
└─────────────────────────────────────────┘
                │
                ▼
┌─────────────────────────────────────────┐
│  Step 3: Isolate Final Cash Flow        │  ---> Solve for z_2 using Par Price
└─────────────────────────────────────────┘
                │
                ▼
  Iterate across all maturities (z_3, z_4, ... z_N)
Step-by-Step Bootstrapping Algorithm
- Short-End Spot Rates: For a short-term bill paying no coupons, the spot rate equals its yield to maturity:

- Intermediate Spot Rates: Consider a par bond with maturity


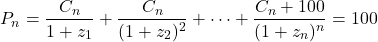
- Solving for

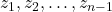
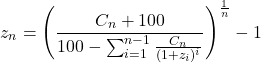


Quantitative Bootstrapping Example
Consider three annual-pay par Treasury bonds trading at USD100.00:
| Bond Maturity | Par Coupon Rate | Price (USD) |
| 1 Year | 3.00% | USD100.00 |
| 2 Years | 4.00% | USD100.00 |
| 3 Years | 5.00% | USD100.00 |
Year 1 Spot Rate (
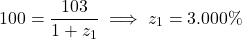

Year 2 Spot Rate (
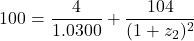

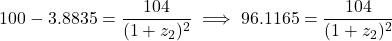

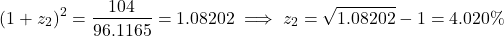

Year 3 Spot Rate (
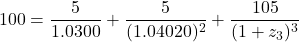

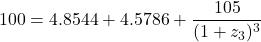

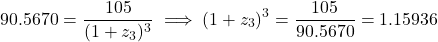

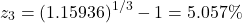

The bootstrapped spot curve (3.000%, 4.020%, 5.057%) lies above the par curve (3.000%, 4.000%, 5.000%), reflecting the upward-sloping yield environment.
Spot Rate Evolutions and Active Bond Management
Active bond portfolio management revolves around testing current market pricing against independent interest rate forecasts.
The Pure Expectations Assumption
Under the Unrated Pure Expectations Hypothesis (PEH), the forward rate 


- The expected total return across all investment horizons is identical (investors cannot earn systematic excess returns).
- Forward rates cannot be used to generate alpha because future spot rates will rise/fall to match current forward projections.
Active Management and Market Inefficiencies
Active managers generate alpha by identifying discrepancies between implied forward rates and their proprietary forecasts:
- If
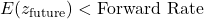
- If
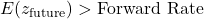

The Rolling Down the Yield Curve Strategy
When the yield curve is upward-sloping and static (i.e., market yield curves do not change over the investment horizon), an investor can exploit the shape of the curve to earn excess returns over a cash benchmark. This strategy is known as rolling down the yield curve or riding the yield curve.
Yield (%)
   ^
   |        Buy 5-Year Bond at Yield Y_5
   |        *  (Higher Yield, Lower Relative Price)
   |         \
   |          \   As time passes (e.g., 1 Year), the bond
   |           \  becomes a 4-Year Bond and "rolls down"
   |            v
   |             * Sold at Yield Y_4 (Lower Yield, Higher Price)
   |
   +----------------------------------------------------> Maturity (Years)
                  <--- Time Passes (1 Year) ---
Mechanics of the Roll-Down Strategy
- Purchase Phase: An investor purchases a longer-term bond (e.g., a 5-year bond yielding 4.84%).
- Holding Period: The investor holds the bond for a shorter duration (e.g., 1 year).
- Sale Phase: As time elapses, the bond’s remaining maturity decreases (e.g., to 4 years). Under a static yield curve, shorter-maturity bonds trade at lower yields (e.g., 4.68%).
- Return Generation: Total return consists of two components:
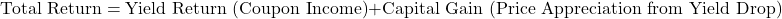

Risks of Riding the Yield Curve
The primary risk to this strategy is an upward shift or flattening of the yield curve. If spot rates increase over the holding period, the bond’s price will decline, offsetting or exceeding the roll-down capital gain.
The Swap Rate Curve and Valuation Frameworks
A Plain Vanilla Interest Rate Swap is an over-the-counter contract where Party A pays a fixed interest rate (the swap rate) and receives a floating reference rate (traditionally LIBOR, now transitionally anchored to overnight risk-free rates such as SOFR in the US, SONIA in the UK, and ESTER in the Eurozone).
Why Market Participants Prefer the Swap Curve
While government bond yields were historically used as the universal discount benchmark, market participants heavily utilize the swap rate curve for corporate asset valuation and risk management for several key structural reasons:
- Credit Uniformity: Government curves reflect sovereign credit risk, local tax treatments, and supply-demand imbalances (e.g., flight-to-safety flows). The swap curve reflects a consistent financial-sector counterparty risk profile.
- No Supply Constraints: Government bond issuance depends on Treasury borrowing needs, leading to scarcity premiums in specific maturities (on-the-run bonds). Swaps are synthetic derivative contracts with virtually unlimited supply.
- Granular Maturity Structure: Swaps trade liquidly across non-standard maturities, providing smooth curve interpolation.
Valuation via the Swap Curve
To value a swap or a private corporate instrument, market participants derive swap zero-coupon discount factors 


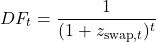

The fixed swap rate 

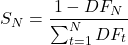

Corporate cash flows are then discounted using these swap-derived zero rates adjusted for specific credit spreads.
Swap Spreads: Calculation and Interpretation
The swap spread is a critical indicator of market liquidity and systemic credit risk within the financial sector.
Definition and Calculation
The swap spread for a given maturity 


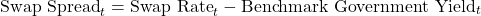

Quantitative Interpretation
Historically, swap rates exceeded government yields (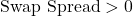

- Widening Swap Spreads: Signals increasing credit risk in the banking sector or deteriorating market liquidity.
- Negative Swap Spreads: Occurs when sovereign bond yields exceed swap rates. This anomaly can happen during periods of heavy government debt issuance coupled with regulatory balance-sheet constraints on bank dealers (e.g., leverage ratios restricting Treasury absorption) alongside structural hedging demand from pension funds receiving fixed swap rates.
Short-Term Interest Rate Spreads and Macro Risk Gauges
Fixed income analysts track specific short-term spreads to evaluate interbank credit conditions and systemic financial stress:
  Short-Term Credit & Liquidity Risk Metrics
  │
  ├─ TED Spread = 3M LIBOR / Short-Term Rate  ─  Treasury Yield
  │  └─ Gauges pure interbank counterparty default risk.
  │
  ├─ OIS Spread = Term Benchmark Rate  ─  Overnight Index Swap
  │  └─ Isolates credit risk from monetary policy expectations.
  │
  └─ SOFR-Treasury Spread = Repo Benchmark Rate  ─  T-Bill Yield
     └─ Measures money-market collateral shortages and dealer capacity.
The TED Spread
Historically defined as the difference between the 3-month LIBOR and the 3-month Treasury bill rate:
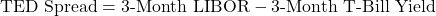

Because Treasury bills are backed by sovereign guarantees while LIBOR represented unsecured commercial bank borrowing, a widening TED spread signals counterparty credit distress in the banking system.
The LIBOR-OIS (or Term SOFR-OIS) Spread
The Overnight Index Swap (OIS) rate reflects market expectations of central bank policy rates derived from geometric averages of overnight cash rates (such as the Fed Funds rate or SOFR). The spread between a term lending rate and the OIS rate isolates counterparty credit risk and term liquidity risk from monetary policy expectations:
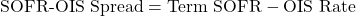

A spike in the OIS spread indicates a reluctance among banks to lend unsecured funds on a term basis due to liquidity hoarding.
Commercial Paper vs. Treasury Spreads
Measures the yield difference between 3-month prime commercial paper issued by corporations and short-term Treasury bills. A widening spread indicates tightening credit conditions for industrial and financial borrowers.
Traditional Theories of the Term Structure of Interest Rates
Classical economics presents four primary theories to explain why yield curves exhibit specific shapes and how forward rates relate to future spot expectations:
| Theory | Core Assumption | Forward Rate Interpretation | Implied Yield Curve Shape |
| Pure Expectations Theory | Investors are risk-neutral; systemic liquidity premiums do not exist. | 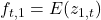 Forward rates are unbiased forecasts of future spot rates. | Slopes up if rates are expected to rise; slopes down if rates are expected to fall. |
| Liquidity Preference Theory | Investors are risk-averse and prefer short-term liquidity; longer bonds require a premium ( | 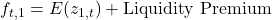 Forward rates upwardly bias future spot expectations. | Naturally upward-sloping even if future spot rates are expected to remain flat. |
| Segmented Markets Theory | Institutional investors are constrained by legal/asset-liability requirements to specific maturity buckets. | Forward rates reflect supply and demand within independent market segments, not expectations. | Yield curve shape is determined purely by supply and demand dynamics per maturity segment. |
| Preferred Habitat Theory | Investors prefer specific maturities but will cross segments if offered a sufficient yield premium. | 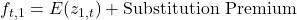 | Yield curve shape reflects rate expectations modified by systemic supply imbalances across maturities. |


Factor Models, Key Rate Durations, and Yield Curve Risk Management
Modern fixed-income portfolio risk cannot be fully captured by a single parallel shift metric (such as effective duration). Empirical research demonstrates that yield curve movements are driven by three primary orthogonal factors derived from Principal Component Analysis (PCA):
Yield Shift (%)
   ^
   |  ======================================== Parallel Shift (~80-90% variance)
   |  ------------------- /------------------- Steepening/Flattening (~5-10%)
   |  ~~~~\____________/~~~~~~~~~~~~~~~~~~~~~~ Curvature (~1-3%)
   +------------------------------------------------------------> Maturity
The Three Dominant Yield Curve Factors
- Level (Parallel Shift): Accounts for 80% – 90% of yield curve variance. Rates across all maturities move up or down by a similar magnitude.
- Slope (Steepening/Flattening): Accounts for 5% – 10% of variance. Short-term rates move in the opposite direction or at a different magnitude than long-term rates.
- Curvature (Butterfly Shift): Accounts for 1% – 3% of variance. Short-term and long-term rates move in one direction while intermediate-term rates move in the opposite direction.
Measuring Risk Exposure: Key Rate Duration
To manage non-parallel curve shifts, portfolio managers track Key Rate Duration (KRD). KRD measures a bond portfolio’s price sensitivity to a 100 basis point shift in a specific maturity segment while keeping yields at all other key maturity points constant.
The percentage change in portfolio value (

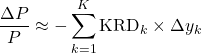

Where 


Managing Curve Risks: Immunization and Positioning
Portfolio managers adjust KRD profiles based on structural market views:
- Bullet Portfolio: Cash flows and duration are concentrated around a single maturity node (e.g., 10 years). Highly sensitive to parallel shifts, less sensitive to curvature shifts.
- Barbell Portfolio: Cash flows are split between short-term and long-term maturities (e.g., 2 years and 30 years), matching the effective duration of a bullet portfolio. Benefits from steepening or increased curvature shifts.
Maturity Structure of Yield Volatilities and Price Volatility
Interest rate volatility is not uniform across the maturity spectrum. Understanding how yield volatility varies by maturity is critical for pricing bond options, embedded caps/floors, and swaptions.
The Term Structure of Yield Volatility
Empirically, short-term interest rates exhibit significantly higher yield volatility than long-term interest rates. This downward-sloping yield volatility curve occurs because:
- Short-term rates are directly impacted by central bank monetary policy shifts, inflation shocks, and economic indicators.
- Long-term rates reflect multi-decade structural growth and inflation expectations, which evolve more smoothly over time.
Vol Volatility (%)
   ^
   |   * (High Short-End Volatility: Central Bank Policy Shocks)
   |    \
   |     \
   |      \____
   |           \====================== (Lower Long-End Volatility: Anchored Long-Term Expectations)
   +------------------------------------------------------------------------> Maturity (Years)
Impact on Price Volatility
While yield volatility is higher at the short end of the curve, a bond’s price volatility depends on the product of yield volatility and bond duration:
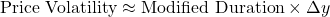

Even though short-term yields experience larger percentage swings (

Macroeconomic Drivers of Benchmark Rates and Spreads
Establishing a cohesive fixed-income strategy requires linking macroeconomic fundamentals to yields, spreads, and yield curve dynamics.
Monetary Policy and Inflation Dynamics
Central bank policy rates directly anchor the short end of the yield curve. Inflation expectations heavily dictate long-end yields through the Fisher equation:
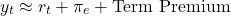

Where 

Fiscal Policy and Sovereign Debt Supply
Large government deficits increase the supply of sovereign bonds. Excessive supply puts upward pressure on long-term yields, widening the term premium and steepening the yield curve.
Economic Growth and the Business Cycle
- Early Expansion: Monetary policy is accommodating (low short rates). Growth picks up, causing long rates to rise in anticipation of future tightening. Result: Yield curve steepens (Bull Steepening / Bear Steepening).
- Late Expansion: Inflation pressures build. Central banks hike short rates aggressively. Result: Short rates rise faster than long rates, causing the yield curve to flatten or invert (Bear Flattening).
- Recession: Economic activity contracts. Central banks cut rates rapidly. Result: Short rates collapse, causing the yield curve to steepen sharply (Bull Steepening).
┌───────────────────────────────────────────────────────────────────────────────────┐
│                          Macroeconomic Scenario Analysis                          │
├───────────────────────┬─────────────────────────────┬─────────────────────────────┤
│ Economic Environment  │ Yield Curve Reaction        │ Optimal Portfolio Strategy  │
├───────────────────────┼─────────────────────────────┼─────────────────────────────┤
│ Central Bank Hikes    │ Bear Flattening             │ Shorten Duration;           │
│ (Late Cycle)          │ (Short Rates Rise Faster)   │ Reduce Spread Exposure      │
├───────────────────────┼─────────────────────────────┼─────────────────────────────┤
│ Rate Cuts Imminent    │ Bull Steepening             │ Long Barbell;               │
│ (Recessionary Shock)  │ (Short Rates Fall Faster)   │ Receive-Fixed Swaps         │
├───────────────────────┼─────────────────────────────┼─────────────────────────────┤
│ Fiscal Expansion      │ Bear Steepening             │ Underweight Long Duration;  │
│ (Heavy Treasury Supply)│ (Long Rates Rise Faster)   │ Overweight Intermediate KRD │
└───────────────────────┴─────────────────────────────┴─────────────────────────────┘
By systematically combining quantitative term-structure models—such as bootstrapped spot curves, key rate duration profiles, and swap market metrics—with macro-level yield drivers, fixed-income professionals can structure portfolios that manage risk while capturing excess returns across changing economic cycles.

