Time-series analysis in investment provides financial analysts, portfolio managers, and corporate decision-makers with the rigorous quantitative tools necessary to model historical asset dynamics, project future financial performance, and systematically quantify risk across global capital markets.
Introduction to Time-Series Analysis In Investment
Time-series analysis in investment represents one of the foundational disciplines of quantitative finance and econometrics. By examining chronological sequences of data points—such as quarterly corporate earnings, daily stock prices, macroeconomic indicators, or foreign exchange rates—investors seek to extract underlying patterns, decompose trends, and project future valuations. In modern capital markets, accurate predictive modeling is essential for dynamic asset allocation, risk management, derivative pricing, and corporate budgeting.
This comprehensive guide explores the core methodologies of time-series analysis in investment. We cover linear and log-linear trend models, covariance stationarity requirements, autoregressive (AR) models, residual autocorrelation testing, mean reversion, out-of-sample forecasting evaluation using root mean squared error (RMSE), random walk processes, unit root testing, seasonal adjustments, autoregressive conditional heteroskedasticity (ARCH), and cointegration. Through practical formulas, empirical evaluations, real-world corporate case studies, and structured tables, financial professionals can master the application of time-series econometric techniques.
Linear and Log-Linear Trend Models
Trend models predict a time-series variable based solely on time 

Calculating and Evaluating Trend Models
A linear trend model assumes that the dependent variable changes by a constant absolute dollar amount per unit of time. The model is specified as:
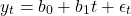

Where:


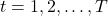


The predicted trend value 


A log-linear trend model assumes that the dependent variable changes at a constant percentage rate per unit of time, reflecting exponential growth. It is specified as:
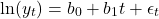

To determine the predicted value
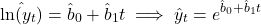

Numerical Comparison of Trend Models
Consider a financial analyst modeling quarterly revenues over 24 periods (

- Linear Model:
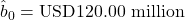
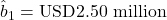
- Log-Linear Model:


To forecast period 

- Linear Forecast:
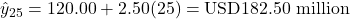
- Log-Linear Forecast:
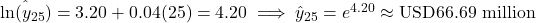


| Feature | Linear Trend Model | Log-Linear Trend Model |
| Growth Assumption | Constant absolute dollar change per period ( | Constant percentage change per period ( |
| Mathematical Equation | 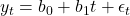 | 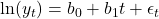 |
| Predicted Value Formula |  |  |
| Primary Use Cases | Stable mature industries, fixed interest expenses | Compound growth, earnings of growing firms, stock indexes |


Selection Criteria and Model Limitations
Determining whether to employ a linear or log-linear trend depends primarily on the visual plot and theoretical properties of the time series:
- Constant Dollar Growth: If historical plot inspection reveals linear growth in fixed dollar steps, choose a linear trend.
- Exponential Growth: If the data exhibits compounding growth (curvature when plotted against time, but linear when plotted on a semi-log scale), choose a log-linear model. Global growth firms like Tesla, Inc. or Amazon.com, Inc. display exponential revenue expansion suitable for log-linear modeling.
Limitations of Trend Models:
- Serial Correlation: Residuals from simple trend regressions frequently suffer from autocorrelation, violating basic Ordinary Least Squares (OLS) assumptions.
- Structural Breaks: Shifts in policy, technological disruption, or macroeconomic crises alter underlying coefficients, invalidating long-term trend extrapolation.
- Lack of Dynamic Structure: Trend models treat time as the sole explanatory variable, ignoring structural economic interactions.
Covariance Stationarity in Time Series
Statistical inference in time-series analysis in investment relies on the assumption of covariance stationarity (also termed weak stationarity).
Requirements for Covariance Stationarity
A time series 

- Constant Expected Value: The mean of the series is constant and finite over time:

- Constant Variance: The variance of the series is constant and finite over time:
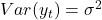
- Constant Autocovariance: The covariance of


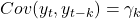


Significance of Non-Stationary Series
If a time series is non-stationary (e.g., displaying a trending mean or time-varying variance):
- OLS regression statistics—such as t-values, standard errors, and

- Regression between two independent non-stationary series often yields a high


Autoregressive (AR) Models
An autoregressive model predicts a dependent variable using its own historical lagged values.
Structure of an AR(p) Model
An autoregressive model of order 

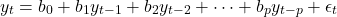

Where 


Multi-Period Forecasting with an AR(1) Model
For an AR(1) model: 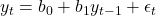

The one-period-ahead forecast at time 

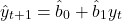

The two-period-ahead forecast at time 


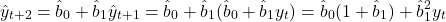

Worked Example of AR(1) Forecasting
Assume an AR(1) model estimated for the operating margin of Toyota Motor Corporation yields 


- 1-Period-Ahead Forecast (
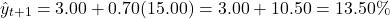
- 2-Period-Ahead Forecast (

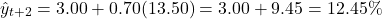


Testing AR Model Specification Using Residual Autocorrelations
To ensure an autoregressive model is correctly specified, the residual error terms must be white noise (i.e., display zero serial correlation).
Diagnostic Testing Procedure
- Estimate the AR Model: Fit an AR(

- Calculate Residual Autocorrelations: Compute residual sample autocorrelations

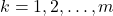
- Compute Standard Errors: Under the null hypothesis of no autocorrelation, the standard error of residual autocorrelation is


- Conduct Test of Significance: Calculate the test statistic:
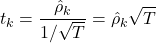
- Evaluate Model Fit: Compare


Mean Reversion and Mean-Reverting Level
A key property of covariance stationary AR processes is mean reversion—the tendency of the series to gravitate back toward its long-run statistical average over time.
Calculating the Mean-Reverting Level
For a stationary AR(1) model 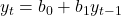

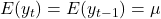


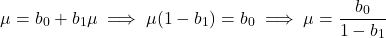

For covariance stationarity, 

Interpretation of Mean Dynamics
- If

- If


Using the previous Toyota Motor Corporation example where
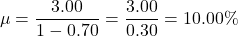

Since current 
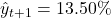
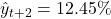


In-Sample vs. Out-of-Sample Forecast Evaluation and RMSE
Evaluating forecasting accuracy requires distinguishing between model fitting and predictive power.
In-Sample vs. Out-of-Sample Forecasts
- In-Sample Forecasts: Forecasts generated for data points within the sample period used to estimate model parameters. They measure how well the model fits historical data.
- Out-of-Sample Forecasts: Forecasts generated for periods outside the estimation window (e.g., holding out the last 20% of historical data). They measure true predictive accuracy on unseen data.
Root Mean Squared Error (RMSE) Criterion
The Root Mean Squared Error (RMSE) quantifies out-of-sample forecast accuracy:
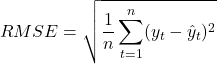

Where 

Instability of Coefficients in Time-Series Models
A critical risk in time-series analysis in investment is coefficient instability. Estimated coefficients (

Causes of Coefficient Instability
- Structural Breaks: Major regime changes—such as geopolitical shocks, central bank monetary policy shifts, financial crises, or regulatory overhauls—change market dynamics.
- Technological Disruption: Paradigm shifts alter corporate revenue trajectories and cost structures.
- Sample Period Sensitivity: Model parameters estimated over an economic expansion may fail completely during a contraction.
Financial analysts test for structural instability using Chow tests or rolling-window regressions. If instability is detected, models must be re-estimated over shorter, homogenous historical windows.
Random Walk Processes vs. Covariance Stationary Processes
A random walk is a time series where the current value equals the previous period’s value plus an unpredictable white noise disturbance.
Mathematical Specification
- Simple Random Walk:
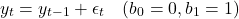
- Random Walk with Drift:
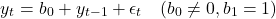


Where
Random Walk Process:        y_t = b_0 + 1.0 * y_{t-1} + e_t  ---> Non-Stationary (Unit Root)
Stationary AR(1) Process:   y_t = b_0 + b_1 * y_{t-1} + e_t  ---> Stationary if |b_1| < 1
Structural Comparison
| Characteristic | Covariance Stationary Process | Simple Random Walk | Random Walk with Drift |
| Slope Coefficient ( | |  | |
| Mean Value | Finite and constant ( | Undefined /  | Increases/decreases by |
| Variance Over Time | Finite and constant | Increases infinitely ( | Increases infinitely ( |
| Mean Reverting Level | Exists ( | Does not exist | Does not exist |
| Statistical Validity | OLS regression valid | Non-stationary (OLS invalid) | Non-stationary (OLS invalid) |


Stock prices, such as shares of Apple Inc. or foreign exchange rates, often approximate random walks, making raw price series unsuitable for standard linear regression without transformation.
Implications of Unit Roots and Transformations
When an autoregressive model has a lag coefficient equal to 1 (
Implications of Unit Roots
- A series with a unit root is non-stationary.
- The variance grows as time
- Shocks to the series are permanent; shocks do not decay over time.
Transforming Unit Root Series
To transform a unit root series into a covariance stationary process, take the first difference of the data (

For a random walk 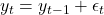

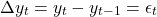

Because 

Dickey-Fuller Unit Root Testing
To determine statistically whether a series contains a unit root, analysts use the Dickey-Fuller test.
Dickey-Fuller Test Steps
- Start with AR(1) Model:
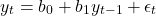
- Subtract

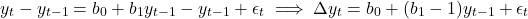
- Define Transformation Parameter

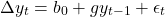
- Formulate Hypotheses:
- Null Hypothesis (


- Alternative Hypothesis (


- Null Hypothesis (
- Execute Test Statistic Evaluation: Calculate the t-statistic for


Augmented Dickey-Fuller (ADF) Test
If the error terms
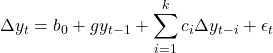

Testing and Correcting for Seasonality in AR Models
Seasonality refers to periodic patterns that repeat at predictable regular intervals within a time series, such as quarterly sales surges for retailers like Walmart Inc. during Q4 holiday seasons.
Detecting Seasonality
To detect seasonality in an AR model, inspect the residual autocorrelations
Modifying the AR Model with Seasonal Lags
Correct seasonality by incorporating a seasonal lag term. For quarterly data exhibiting a 4-quarter cycle, an AR(1) model with a seasonal lag is specified as:
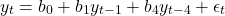

Forecast Calculation with Seasonal Lag
Suppose an analyst models quarterly sales for luxury conglomerate LVMH using an AR(1) model with a 4th-quarter seasonal lag:

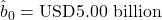


Given historical quarter data:
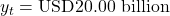
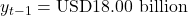
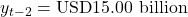
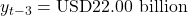


To forecast period
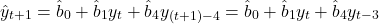

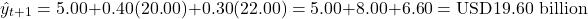

Autoregressive Conditional Heteroskedasticity (ARCH)
Standard time-series models assume homoskedasticity—that the variance of residual errors is constant over time. However, financial market returns display volatility clustering: high-volatility periods group together, and low-volatility periods group together.
Structure of an ARCH(1) Model
Autoregressive Conditional Heteroskedasticity (ARCH) models time-varying variance. An ARCH(1) process defines residual variance 

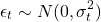

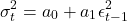

Where 


Residual Errors (e_t) ---> Square Errors (e_t^2) ---> Regress e_t^2 on e_{t-1}^2 ---> Predict Volatility (sigma_t^2)
Testing and Predicting Volatility
- Testing for ARCH: Estimate the primary AR model, extract residuals

If the estimated slope parameter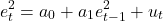

- Applications in Financial Risk Management: If an ARCH effect exists, standard errors of OLS AR parameters are incorrect, requiring Generalized Least Squares (GLS) or ARCH/GARCH estimation. Global investment banks such as JPMorgan Chase & Co. use ARCH modeling to forecast Value-at-Risk (VaR), price options options contracts, and adjust portfolio margins during periods of market stress.


Analyzing Nonstationarity and Cointegration in Linear Regression
When estimating a linear regression combining multiple time series (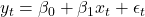

Decision Matrix for Multi-Series Regression
| Series yt Status | Series xt Status | Cointegration Status | Modeling Approach |
| Stationary | Stationary | N/A | Fit OLS linear regression directly |
| Stationary | Non-Stationary | No | Invalid regression; transform  |
| Non-Stationary | Non-Stationary | Not Cointegrated | Invalid (spurious regression); first-difference both series ( |
| Non-Stationary | Non-Stationary | Cointegrated | Regress |

Testing for Cointegration
Two non-stationary series (integrated of order 1, denoted 

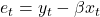


Engle-Granger Cointegration Test Procedure:
- Regress non-stationary
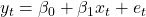
- Extract regression residuals

- Run an ADF unit root test on the residual series
- If the null hypothesis of a unit root in residuals is rejected, the residuals are stationary. Conclude that


Selection Framework for Investment Time-Series Models
To determine the appropriate model for an investment problem, analysts follow a systematic diagnostic evaluation pipeline:
[Time Series Data]
       │
       ▼
Is data Covariance Stationary?
 ├── NO ──► Check for Unit Root (ADF Test)
 │             ├── Has Unit Root ──► First Difference Data (\Delta y_t)
 │             └── Has Linear/Exp Trend ──► Use Linear or Log-Linear Model
 └── YES
       │
       ▼
Are Residuals Autocorrelated? (AR(p) Diagnostic)
 ├── YES ──► Add Lagged Terms / Seasonal Lags (AR(p+s))
 └── NO
       │
       ▼
Are Residuals Conditionally Heteroskedastic? (ARCH Test)
 ├── YES ──► Use ARCH/GARCH Volatility Model
 └── NO  ──► Model Specified correctly (Execute Forecast)
| Step | Investment Problem Scenario | Primary Diagnostic Tool | Recommended Model Structure | Justification |
| 1 | Predict continuous long-term compounding revenues for tech firm | Semi-log scatter plot & constant growth check | Log-Linear Trend Model (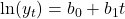 | Captures exponential compound percentage growth cleanly. |
| 2 | Forecast quarterly sales displaying holiday surges | Residual autocorrelation check at lag 4 | AR(1) with 4th Seasonal Lag (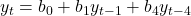 | Eliminates seasonal autocorrelation in residual terms. |
| 3 | Model equity index price movements with unit roots | ADF Test ( | First-Differencing / AR(1) on Returns (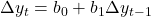 | Transforms non-stationary price series into stationary return series. |
| 4 | Forecast financial market volatility and option pricing risk | ARCH test on squared residuals ( | ARCH(1) / GARCH Model (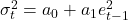 | Adjusts standard errors for time-varying volatility clustering. |
| 5 | Analyze long-run equilibrium between two non-stationary commodities | Engle-Granger residual ADF test | Cointegrated Regression / Error Correction Model | Avoids spurious regression while preserving long-run equilibrium. |


Conclusion
Time-series analysis in investment provides financial professionals with a quantitative framework for modeling structural market dynamics, forecasting corporate performance, and managing risk. By applying trend models, ensuring covariance stationarity, structuring autoregressive architectures, evaluating out-of-sample RMSE, testing for unit roots, correcting for seasonality, and modeling ARCH dynamics, quantitative analysts build robust empirical models that inform modern investment strategies.

